Each month I write an article for ICAEW on the monthly public sector finance release. Here are my most recent articles:
Public sector net debt hits £3tn ahead of budget
Rising inflation and budget overruns provide a difficult backdrop for John Healey as he prepares for his first fiscal event. The Chancellor is under pressure to provide more support for rising energy bills, but the challenges to balance spending are mounting.
Budget overrun widens as public finances disappoint
The triple whammy of geopolitical uncertainty, persistent inflation and rising gilt yields are squeezing the public purse as the Chancellor prepares for his first budget.
Read More
www.icaew.com
UK net debt in touching distance of £3.0tn
Latest data confirms that the UK’s public finances remain weak, despite taxpayers facing the highest tax burden since the 1960s. The Chancellor faces significant challenges if he is to increase public spending, says ICAEW.
Our chart this week looks at how the five-year fiscal forecasts have consistently proved too optimistic in recent years, something to bear in mind as the budget approaches.
Read More
www.icaew.com
Chart of the week: disposable income
Our chart this week looks at how income is distributed across UK households with a median equivalised household disposable income of £3,265 per month and an equivalised average of £3,800 per month.
Read More
www.icaew.com
Chart of the week: UK productivity remeasured
Our chart this week looks at how the ONS is changing how it calculates labour productivity – one of the most important factors driving economic growth.
Read More
www.icaew.com
Chart of the week: public sector workforce
Our chart this week looks at how one third of the 6.2m public sector workforce work for the NHS while 9% work for the Civil Service.
Read More
www.icaew.com
Chart of the week: OBR long-term fiscal forecast
Our chart this week shows how alternative scenarios go off the chart in the OBR’s latest long-term fiscal projections.
Read More
www.icaew.com
Chart of the week: long-term interest rates
Our chart this week highlights how long-term borrowing costs have changed over the past year in Japan, Germany, France, the US and the UK.
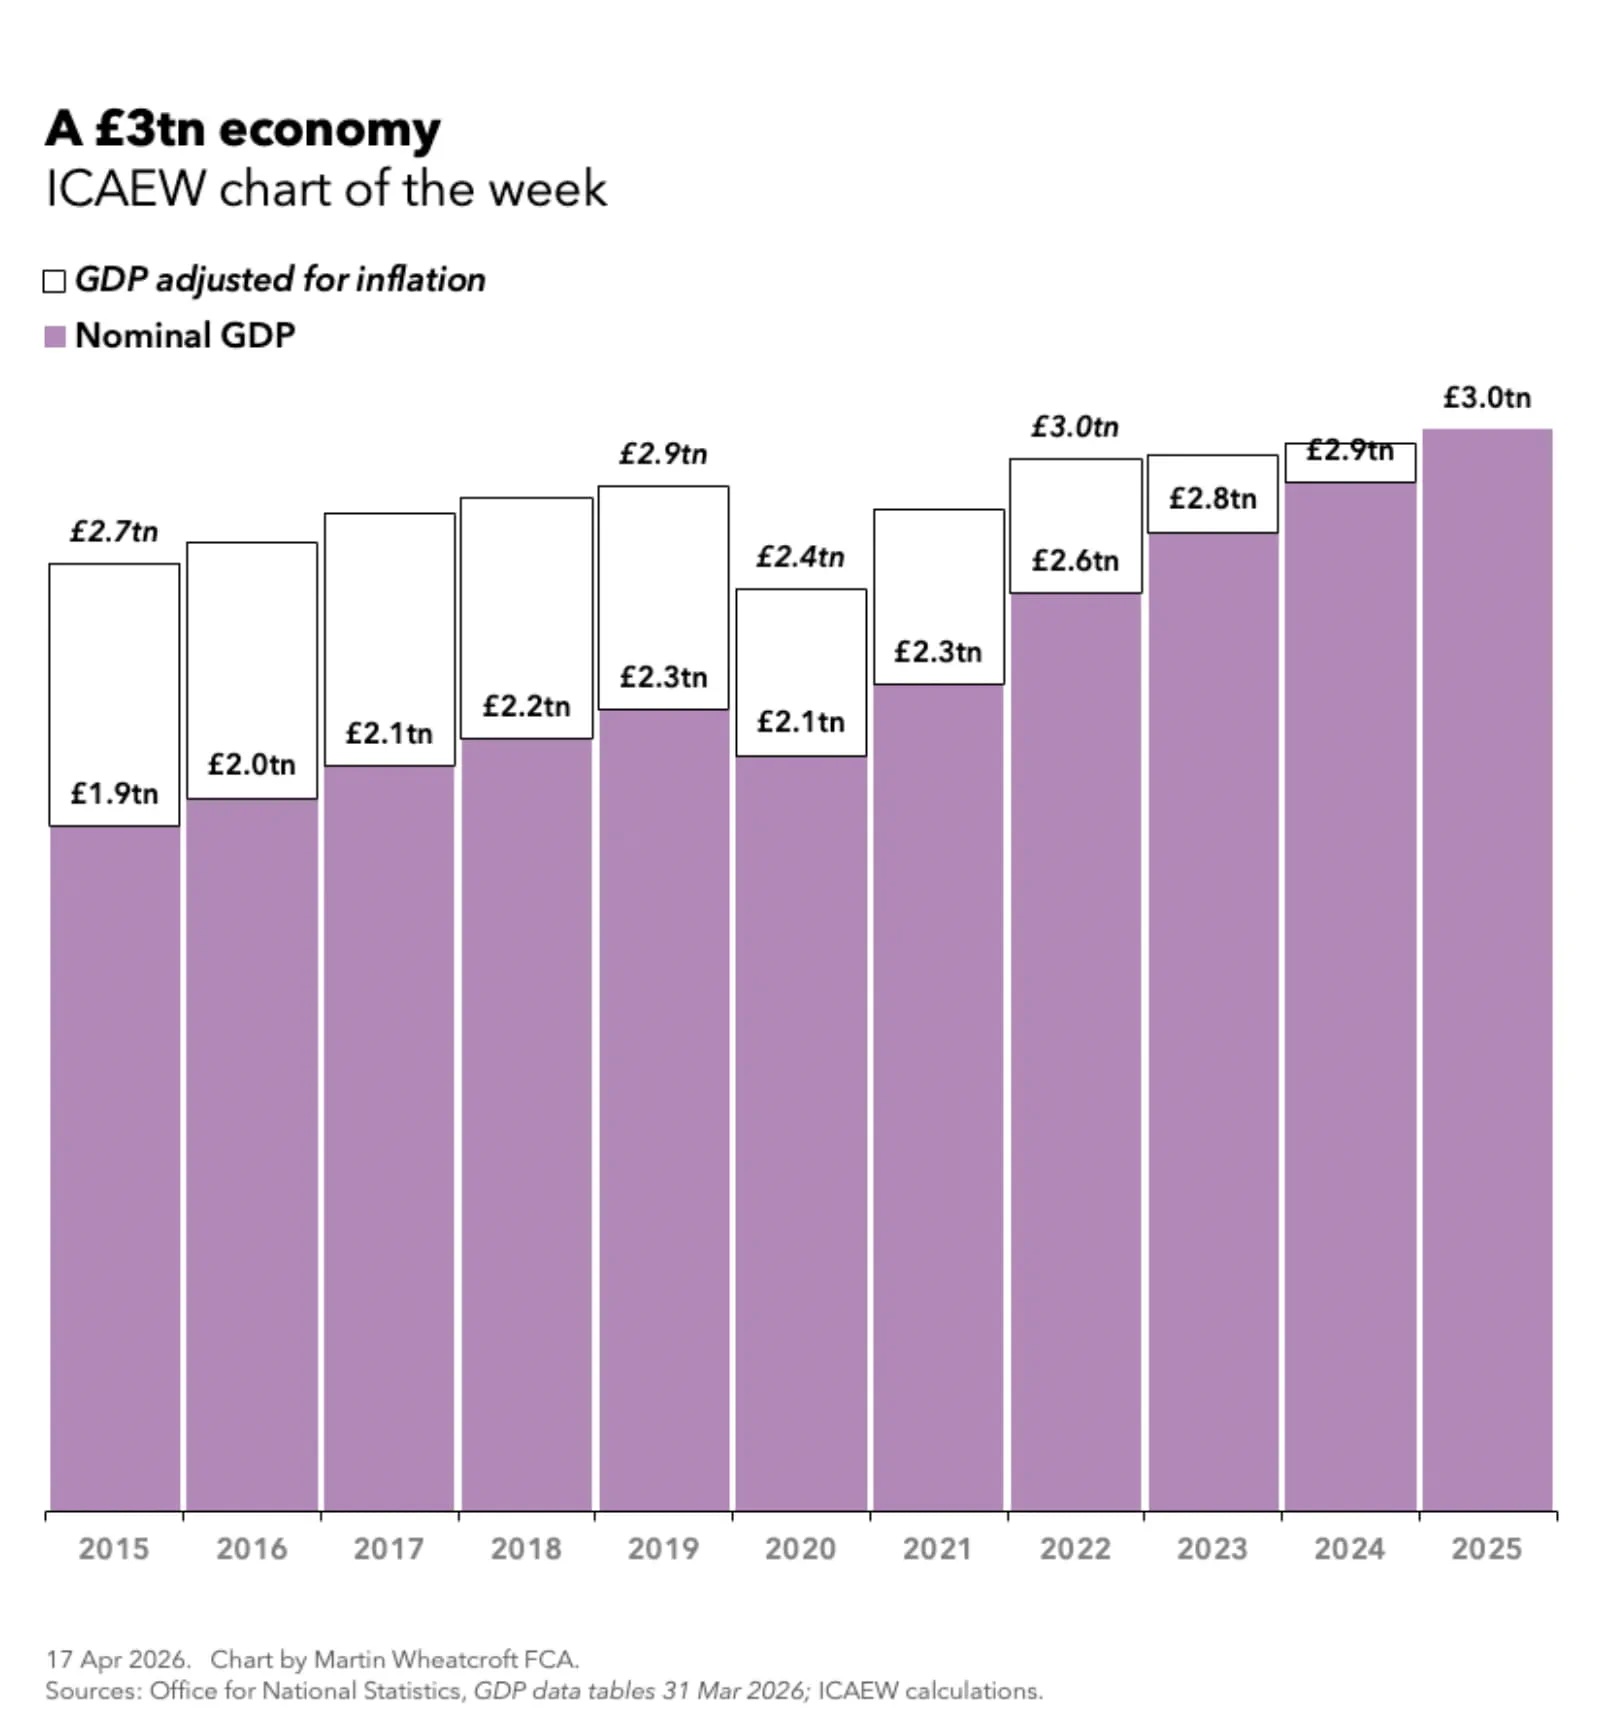
My chart this week for ICAEW is on how GDP for the UK reached £3.0tn for the first time in 2025. This is a 58% increase over the course of a decade, mostly driven by a combination of inflation and a rising population, resulting in a relatively small amount of per capita economic growth.
My chart of the week for ICAEW is on gross domestic product (GDP), the principal measure used by statisticians and economists to assess the size of the economy.
The chart shows how nominal GDP (GDP at market prices in current values) was £1.9tn in 2015, rising to £2.0tn in 2016, £2.1tn in 2017, £2.2tn in 2018 and then £2.3tn in 2019. Nominal GDP fell to £2.1tn in 2020 (the first year of the pandemic) and then rose to £2.3tn in 2021, £2.6tn in 2022, £2.8tn in 2023, £2.9tn in 2024 and then £3.0tn in 2025.
This is a cumulative increase of 58% over 10 years (or 4.7% a year on average), based on nominal GDP of £1,928bn in 2015 and £3,040bn in 2025.
The chart also shows the increase is much less dramatic using GDP adjusted for inflation (GDP at market values on a chained volume basis or ‘real GDP’). Recalculated into 2025 values, GDP adjusted for inflation was £2.7tn in 2015, £2.9tn in 2019, £2.4tn in 2020 and just under £3.0tn in 2022.
As ever with economic statistics these numbers are all subject to revision as the ONS obtains new or updated data and, every so often, revises its methodology.
Analysing the increase
The 58% increase in nominal GDP over the 10 years to 2025 can be analysed as a cumulative 38% increase from inflation (using the GDP deflator ‘all economy’ measure of inflation) and cumulative economic growth of 14%, with the latter being further analysed into a cumulative 7% increase in the size of the population, and a cumulative 7% increase in average economic activity per person.
This is equivalent to a 4.7% per year average annual increase in nominal GDP over the decade, comprising 3.3% per year in average annual inflation and 1.3% per year in economic growth. The latter comprises a 0.7% per year annual rise in population and a 0.7% increase in average per capita economic activity.
Economic growth has been particularly weak over the past three years in particular, with a cumulative increase of 17.8% in nominal GDP comprising cumulative inflation of 14.6% and a cumulative increase of 2.8% in GDP adjusted for inflation (from £2,958bn in 2022 adjusted to 2025 prices to £3,040bn in 2025).
As the population is estimated to have increased by 2.7% between 2022 and 2025, per capita economic activity over the same period has in effect been flat over the last three years.
Unfortunately, the outlook for the economy is far from rosy given recent international developments and there is now a risk that nominal GDP could fall back below £3.0tn in 2026, despite what is likely to be a higher rate of inflation than previously anticipated.
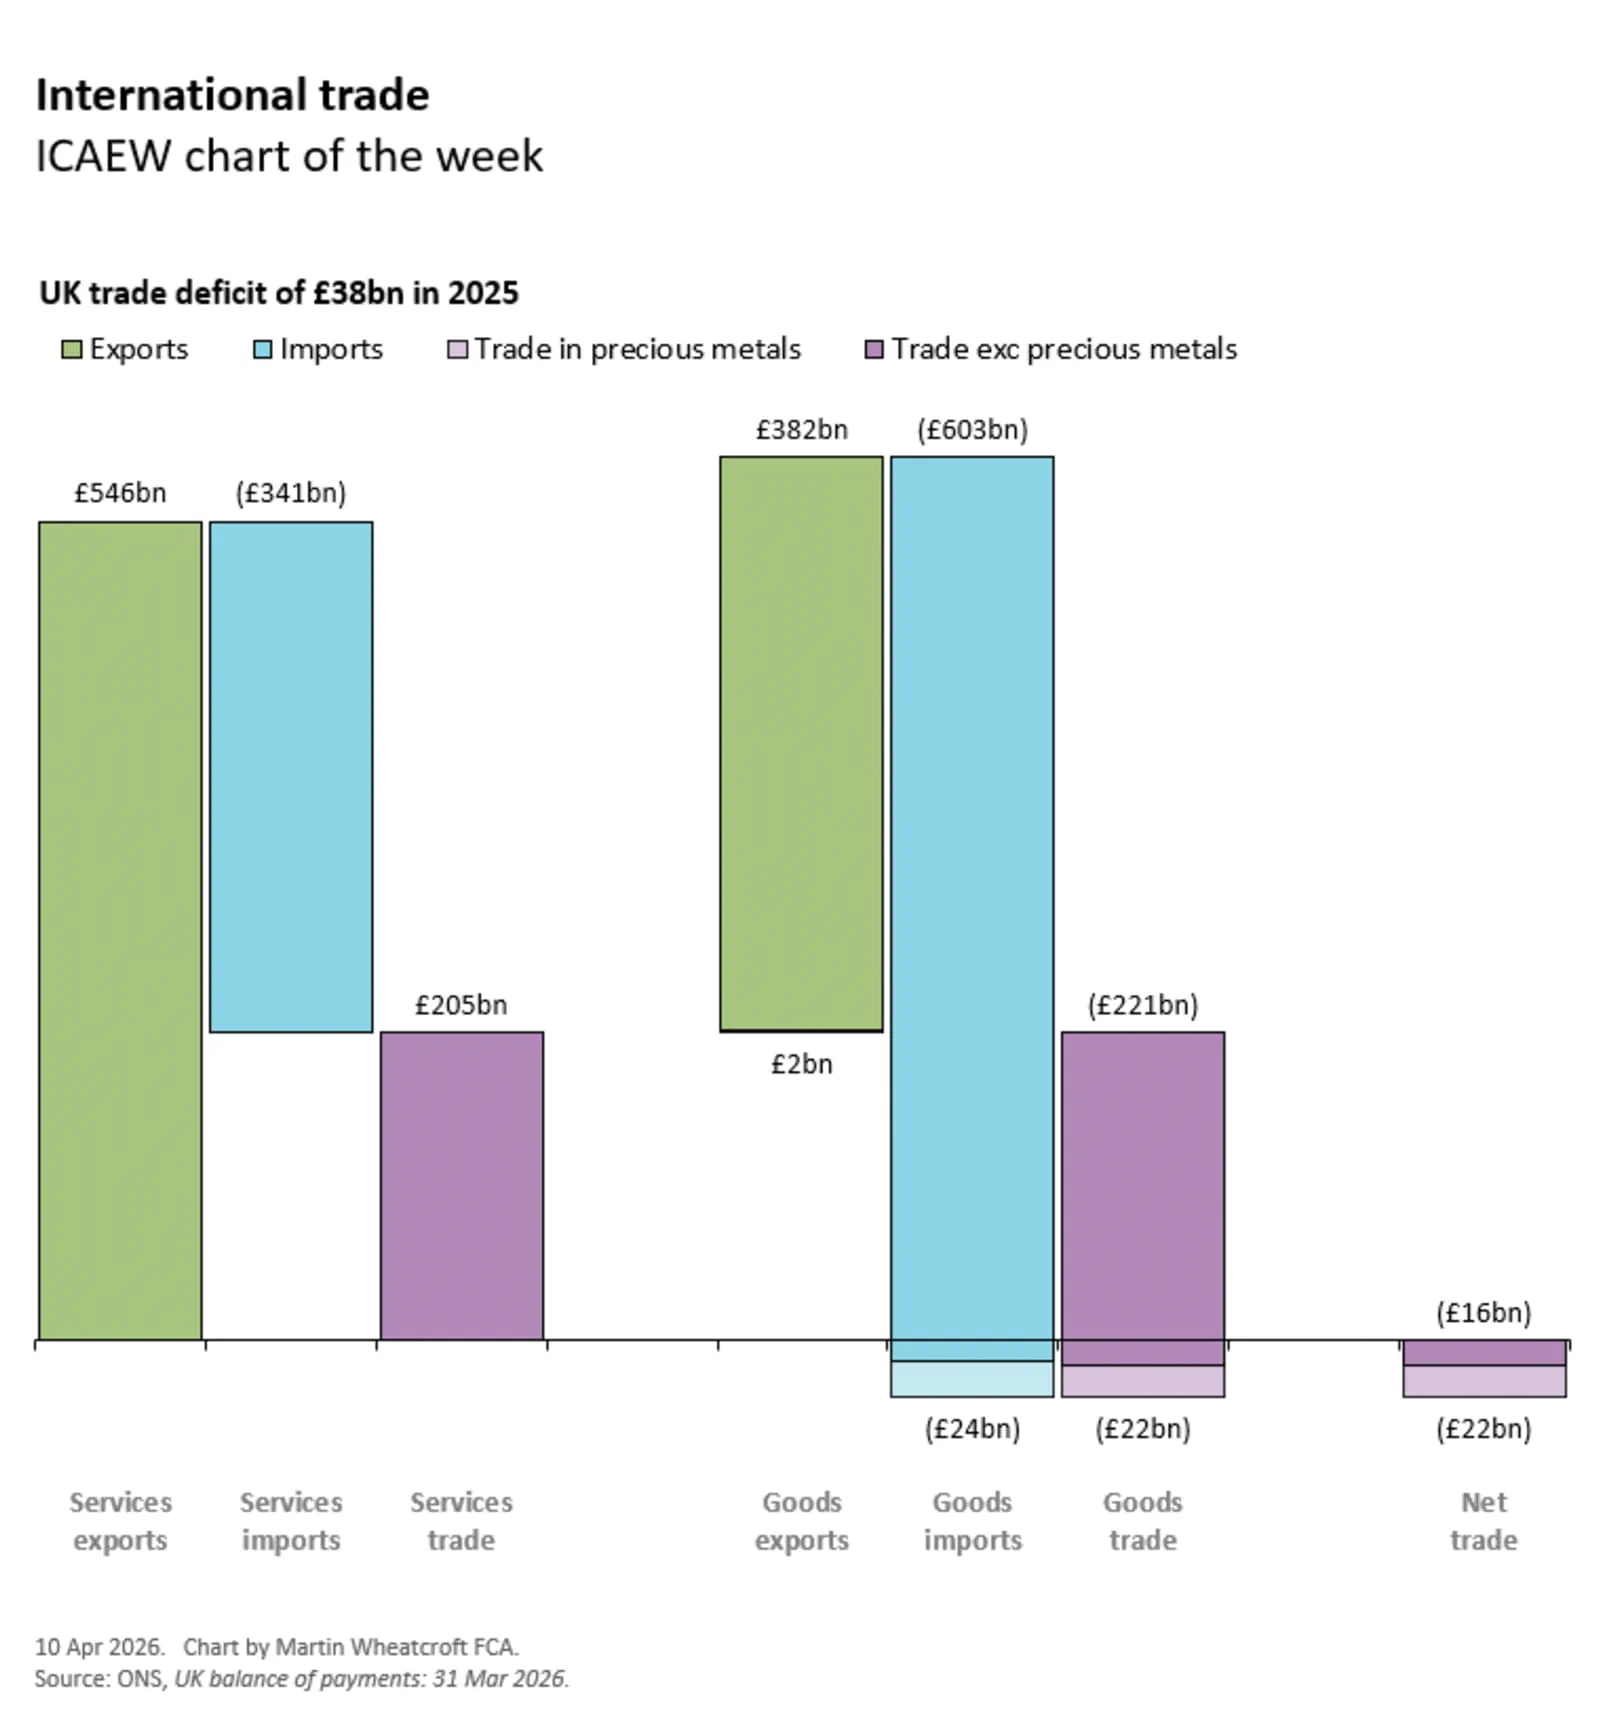
This week’s chart for ICAEW illustrates how a £205bn surplus on trade in services was offset by a £243bn deficit on trade in goods to result in a net trade deficit of £38bn in 2025 – or £16bn if trade in precious metals is excluded.
My chart this week for ICAEW is on the principal components of the UK’s £38bn trade deficit in the 2025 calendar year.
The chart starts with a £205bn surplus on trade in services (comprising a £546bn cash inflow from services exports less a £346bn cash outflow to pay for services imports) followed by a £221bn deficit on trade in goods excluding precious metals (comprising £382bn generated from goods exports less £603bn to pay for goods imports), and a £22bn deficit on trade in precious metals (comprising £2bn from exports less £24bn on imports).
Together these result in an overall trade deficit of £38bn, of which £16bn is a deficit on trade in goods and services excluding precious metals and £22bn relates to precious metals.
This is equivalent to a net trade deficit of 1.3% of GDP, comprising a surplus on trade in services of 6.7% of GDP (17.9% from exports – 11.2% on imports) less a deficit on trade in goods excluding precious metals of 7.3% of GDP (12.6% from exports – 19.9% on imports) and a deficit on trade in precious metals of 0.7% of GDP (0.1% from exports – 0.8% on imports).
The ONS publishes trade statistics that exclude precious metals because a large proportion of the value of this trade are sales and purchases of gold between UK and international holders that are really financial flows, often without any physical movement of the gold concerned. Not only can the volume and value of such transactions be quite volatile, but the trade deficit excluding precious metals of £16bn in 2025 is probably more representative of trade flows in that year than the overall trade deficit of £38bn.
The balance of payments
Not shown in the chart are the other components of the current account deficit of £74bn in 2025 and a capital account deficit of £5bn.
The former comprised a primary income or ‘earnings’ deficit of £19bn (being £417bn investment income coming to the UK and £2bn foreign compensation of UK-based employees less £435bn investment income going abroad and £3bn compensation of foreign employees) and a secondary income deficit or ‘net transfers’ of £17bn (£1bn UK government receipts £1bn and £30bn remittances and other inward transfers less £12bn UK government payments abroad and £36bn remittances and other outward transfers) in addition to the trade deficit of £38bn. The latter consisted of £2bn from international sales of non-produced non-financial assets less £7bn in purchases.
The chart also doesn’t show the £79bn surplus in 2025 on the other side of the balance of payments, being an £86bn surplus on financial transactions (£678bn in financial investments in the UK less £592bn in outbound financial investments) less £7bn in statistical errors and omissions.
The trade deficit over time
The trade deficits excluding precious metals of £17bn in 2024 and £16bn in 2025 were a little lower than the £24bn average over the last quarter of a century and were less than the net £19bn average over the previous four years that were distorted by the pandemic and the energy crisis (trade surpluses excluding precious metals of £14bn and £7bn in 2020 and 2021 followed by deficits of £50bn and £47bn in 2022 and 2023).
Whether you think the trade deficit is good or bad depends on your perspective, with some worried about the net cash outflows that result from payments for imports exceeding receipts from exports. Others points to the net positive inflows of goods and services that are coming into the UK in exchange for the money that we spend.
Either way, what we sell abroad and what we buy from overseas are important not only to UK businesses that trade internationally but also to all of us living in the UK.
The Bank of England’s Christmas present to the nation of a cut in interest rates prompts my chart of the week for ICAEW to take a look at what is going under the hood of inflation.
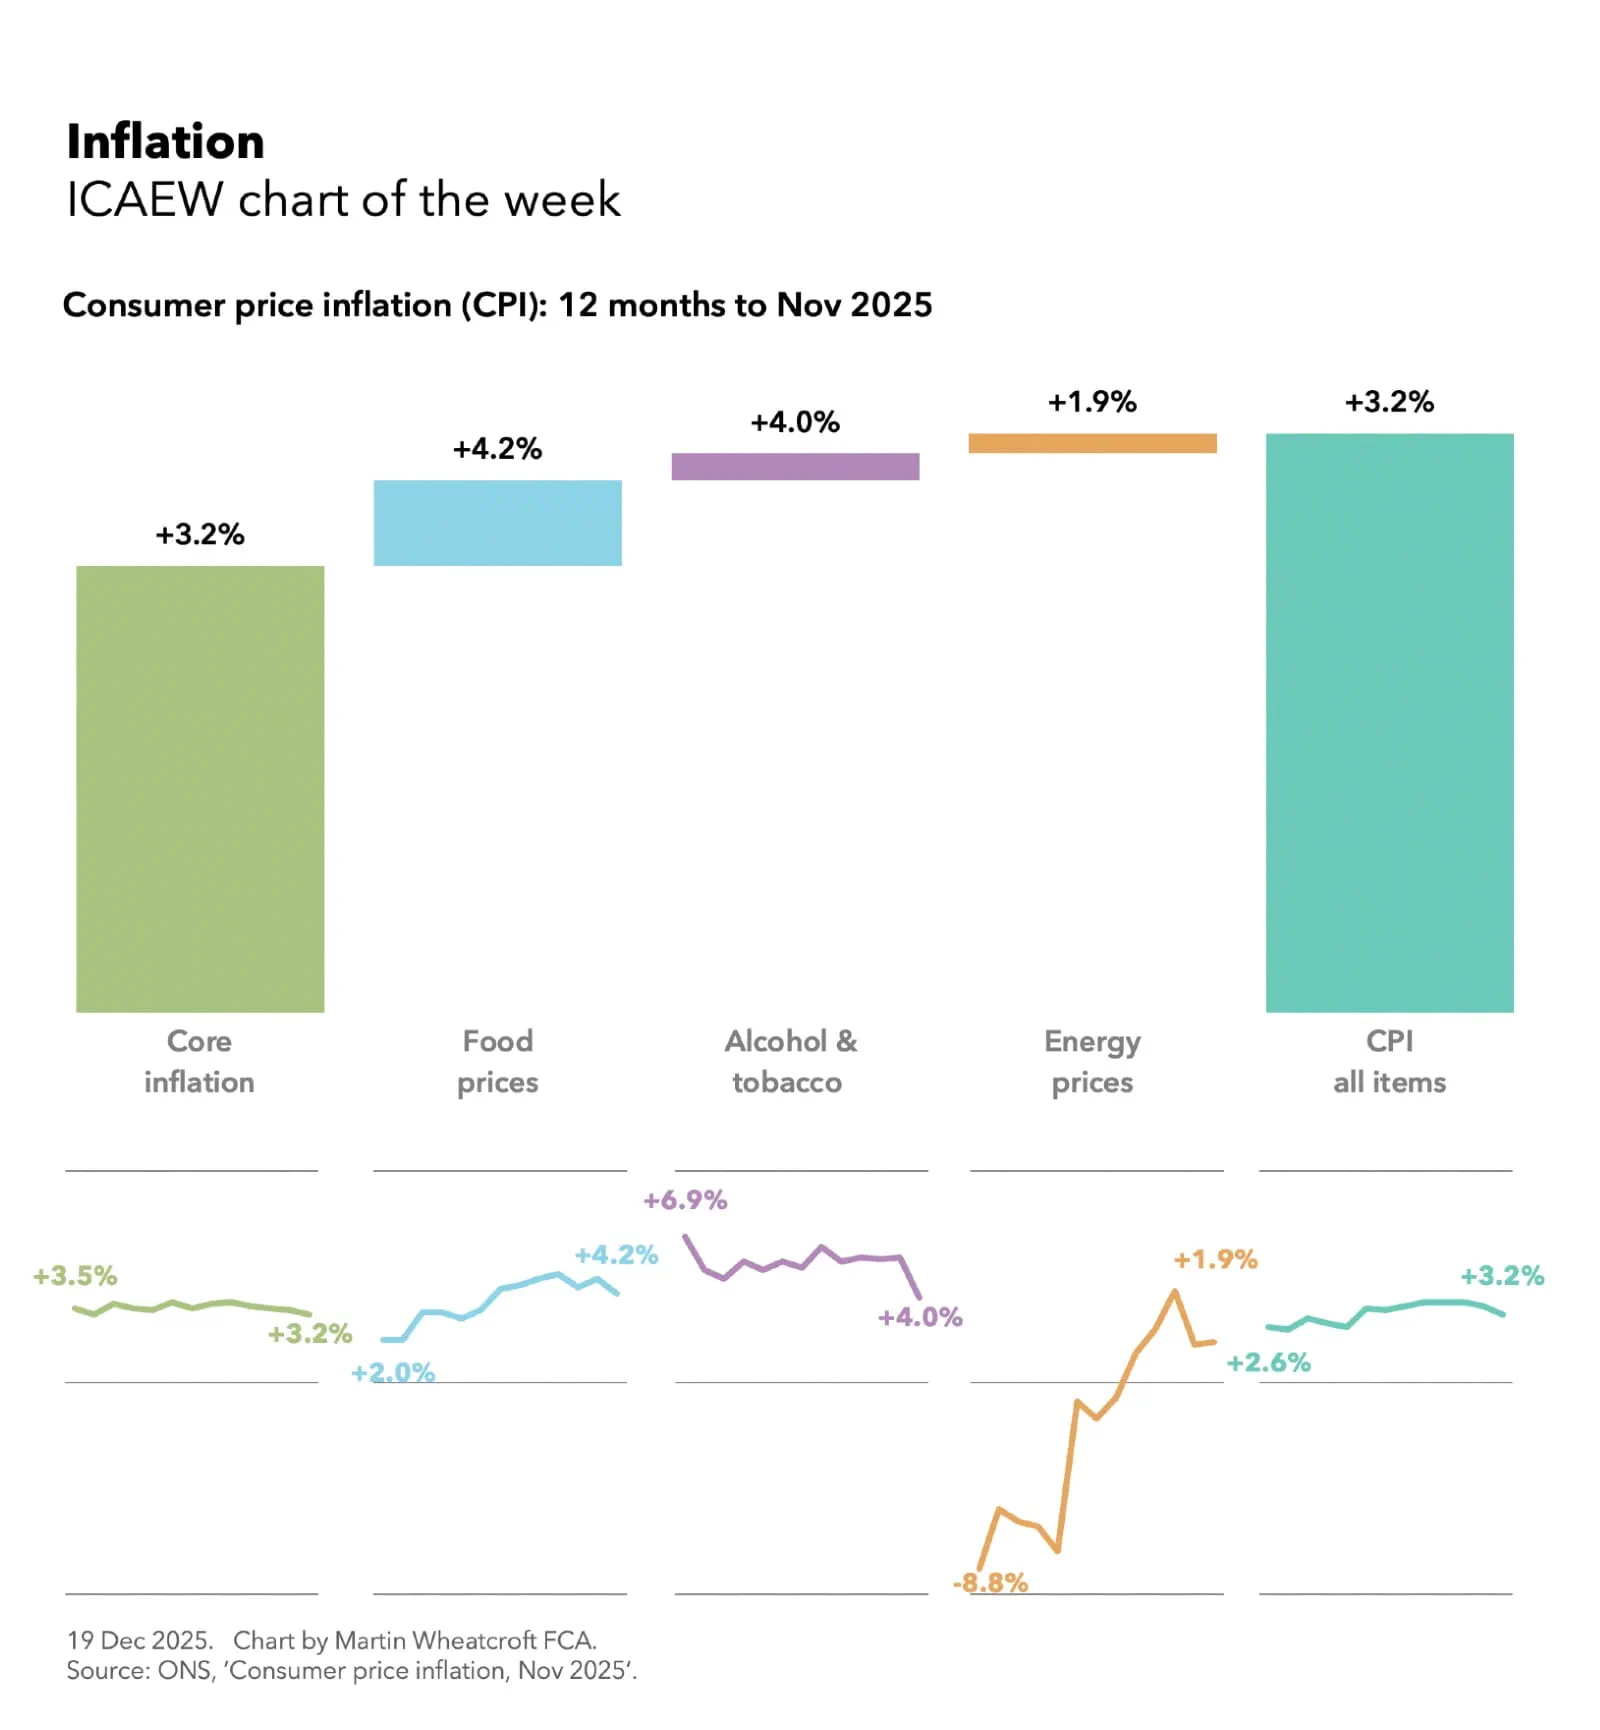
According to the latest release from the Office for National Statistics (ONS), prices in the UK rose by 3.2% over the course of the 12 months to November 2025.
My chart for ICAEW this week analyses this in more detail, breaking down the 3.2% annual rise in the consumer price inflation (CPI) index over the 12 months to November 2025. It shows that core inflation rose by 3.2%, while prices for food, alcohol and tobacco, and energy increased by 4.2%, 4.0% and 1.9% respectively.
Last year’s CPI was 2.6% in the year to November 2024, when core inflation, food, alcohol and tobacco, and energy inflation of 3.5%, 2.0%, 6.9% and -8.8% contributed 2.7%, 0.2%, 0.3% and -0.6% to the total increase respectively (taking into account their respective weightings). This compares to the 12 months to November 2025 – as shown in the chart – when core inflation, food, alcohol and tobacco, and energy inflation of 3.2%, 4.2%, 4.0% and 1.9% contributed 2.5%, 0.5%, 0.1% and 0.1% respectively to the total increase in the CPI.
Core inflation covers almost four-fifths of the goods and services that make up the CPI index and is therefore a better indicator of underlying trends, as it excludes food, alcohol and tobacco, and energy – some of more volatile components of consumer spending. The gradual trend downwards from 3.5% in the 12 months to November 2024 to 3.2% in the 12 months to November 2025 is therefore a positive sign that overall inflation is on its way back to being in the Bank of England’s target range of 2% plus or minus 1%.
However, there is still some concern about the rate of services inflation (a subcomponent of core inflation) which has remained relatively high at 4.4% in the 12 months to November 2025. While this is an improvement over the 5.0% comparative for a year ago, the Bank of England will want to see this come down further in the new year if they are going to go beyond the interest rate cut announced yesterday.
Many of our individual experiences of inflation are likely to feel worse than this given that food prices (including non-alcoholic beverages) have increased by 4.2% over the past 12 months, with some foodstuffs having increased by a lot more. According to the ONS, beef costs 27.7% more than a year ago, chocolate is up 17.3%, coffee is up 14.5% and butter is up 12.1% – all noticeable increases to most consumers. The positive news is that although annual food price inflation accelerated from 2.0% a year ago to a peak of 5.1% in the 12 months to August 2025, it has started to slow again since then.
Alcohol and tobacco prices constitute an even smaller component of the index (about 4% compared with the 11% represented by food) but are very visible to consumers who indulge. The positive news for those individuals is that the annual rate of increase in these prices has slowed from 6.9% a year ago to 4.0% in the 12 months to November 2025, with the latter comprising a 3.8% increase in the prices of alcoholic beverages and 4.2% in tobacco prices.
Energy comprises just over 6% of the overall index but its volatility can still have a significant influence on the overall index despite that weighting. This time last year energy prices had fallen by 8.8% over the previous 12 months, pulling down the overall rate of inflation by 0.6 percentage points. This year energy prices are up 1.9%, contributing 0.1% to the overall rise.
The good news was that the downward trend in inflation, particularly core inflation, was thought sufficiently positive to enable the Monetary Policy Committee (MPC) of the Bank of England to vote for a cut in interest rates in December. However, the close vote suggests that the MPC would like to see a further slowdown in the rate at which prices are rising before going further.
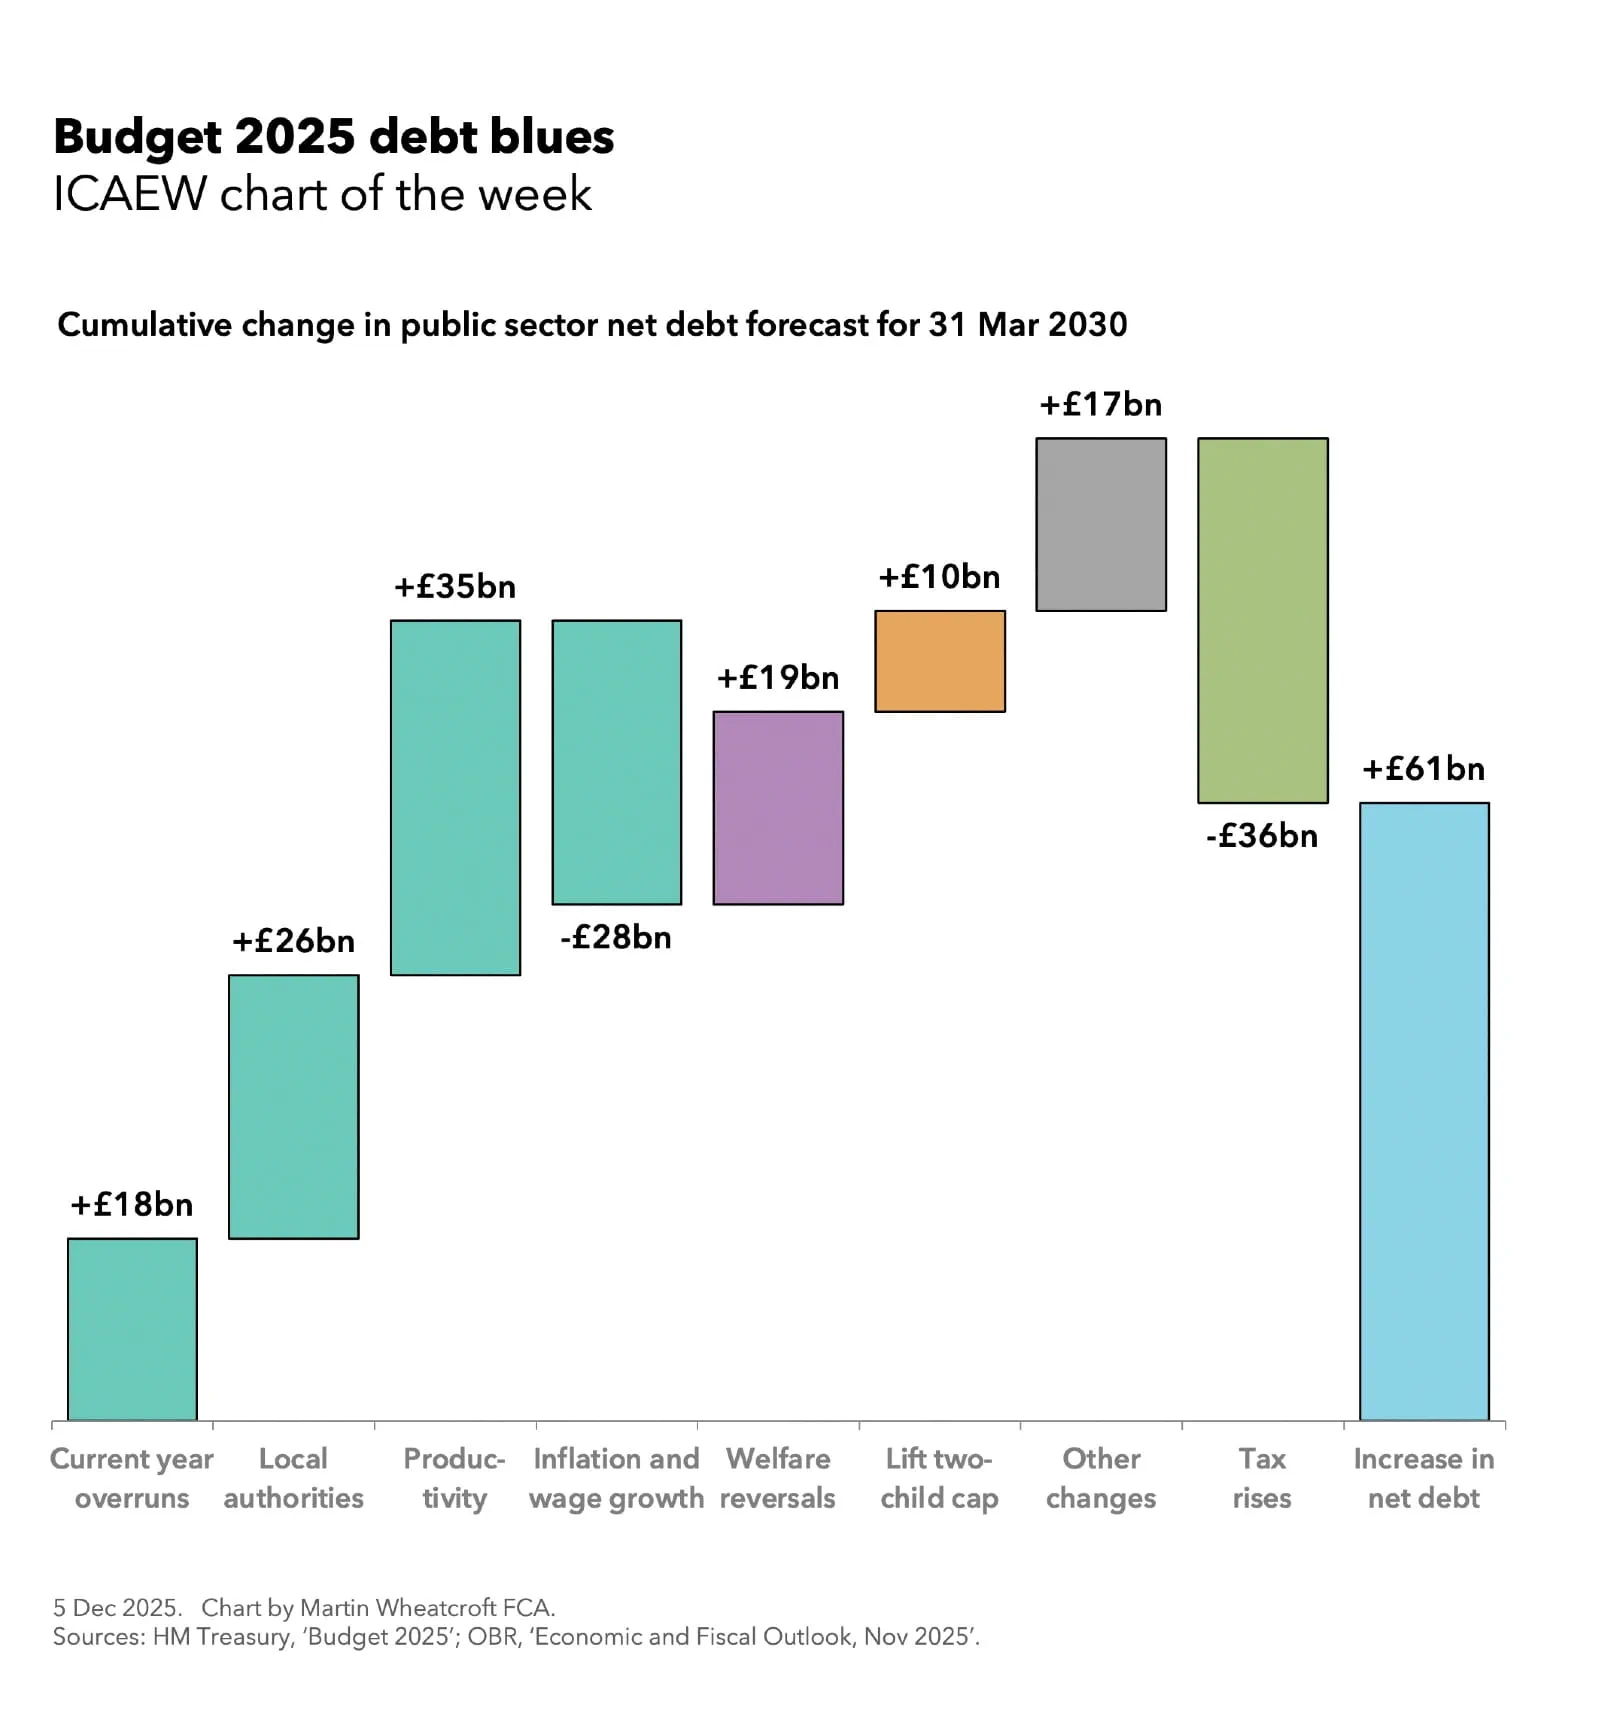
My chart for ICAEW this week illustrates how despite being a “tax-raising Budget”, the cumulative net effect of all the changes announced last week is to add £61bn to the public sector net debt forecast for 31 March 2030.
While my chart for ICAEW last week looked at the impact of Budget 2025 on 2029/30, the fourth year of the fiscal forecast used for the Chancellor’s fiscal rules, this week’s focus is on the cumulative effect of the changes made between now and 31 March 2030.
The first four bars of our step chart analyse the OBR’s forecast revisions, starting with extra borrowing to fund the expected budget overrun in the current financial year (2025/26) of £18bn (technically a £21bn higher deficit less a £3bn opening adjustment). This is followed by more borrowing to fund higher local authority spending of £26bn over four years (an average of £6.5bn a year) and to cover cumulative lower receipts of £35bn from downgrading the productivity growth assumption (£2bn a year rising to £16bn by 2029/30). This is then offset by £28bn over four years from the impact of inflation and wage growth on receipts exceeding the impact of inflation and other cost pressures on public spending.
Borrowing over the next four years is then increased by £19bn (just under £5bn a year on average) to cover the government’s welfare reversals over the summer – the restoration of the winter fuel allowance to many pensioners and the decision not to proceed with eligibility restrictions for disability benefits that were needed to make the Spring Statement add up.
The decision to lift the two-child benefit cap adds another £10bn (£2.5bn a year on average) to projected debt over the next four years, while other policy measures and working capital movements are expected to add £17bn (£11bn and £6bn respectively) on top of that.
A £36bn net reduction in debt from higher tax receipts net of indirect effects over the next four years (zero in 2026/27, £4bn in 2027/28, £10bn in 2028/29, and £22bn in 2029/30) reduces the cumulative impact to £61bn, with the £3,391bn forecast for 31 March 2030 at the time of the Spring Statement back in March 2025 being revised up to £3,452bn in the Autumn Budget 2025.
Perhaps the most surprising aspect of this analysis is the £26bn revision to the forecast for local government spending. While not as large as the well-publicised impact of productivity downgrades on the OBR’s fiscal forecast, it highlights some fundamental bookkeeping issues in how the government manages the public finances. A monthly financial consolidation process that excludes local government, schools and many other public bodies means the Office for National Statistics (ONS) and HM Treasury rely on forecasts and estimates instead of actual data when reporting the monthly public sector finances, exacerbated by the use of the four different accounting frameworks across the public sector and the local audit crisis in England that has created a large backlog in local authority audited financial statements.
The OBR states: “Recent substantial revisions to LA borrowing estimates and outturns, which reflect ongoing challenges in obtaining timely and high-quality estimates particularly for expenditure by local authorities. The ONS, the Ministry of Housing, Communities and Local Government, the Treasury and the OBR have formed a joint Local Government Financial Information Taskforce to investigate and address these concerns, with the overall objective of improving the flow of data to the ONS and the accuracy of our forecast.”
Meanwhile, the backloading of tax rises means that although the forecast is for a current budget surplus in 2029/30 and for a reduced overall deficit in that year, the summer welfare reversals, lifting of the two-child benefit cap, and other policy changes all require more borrowing before the tax rises kick in.
The 2025 Budget provides very mixed messages about the UK public finances’ prospects. There is more borrowing over the next three years before tax rises fully kick-in, while at the same time there are significant risks that mean the government could be back here again next year or the year after to ask for more money.
If ever a Chancellor could really do with some good economic news, it is probably in the coming year.
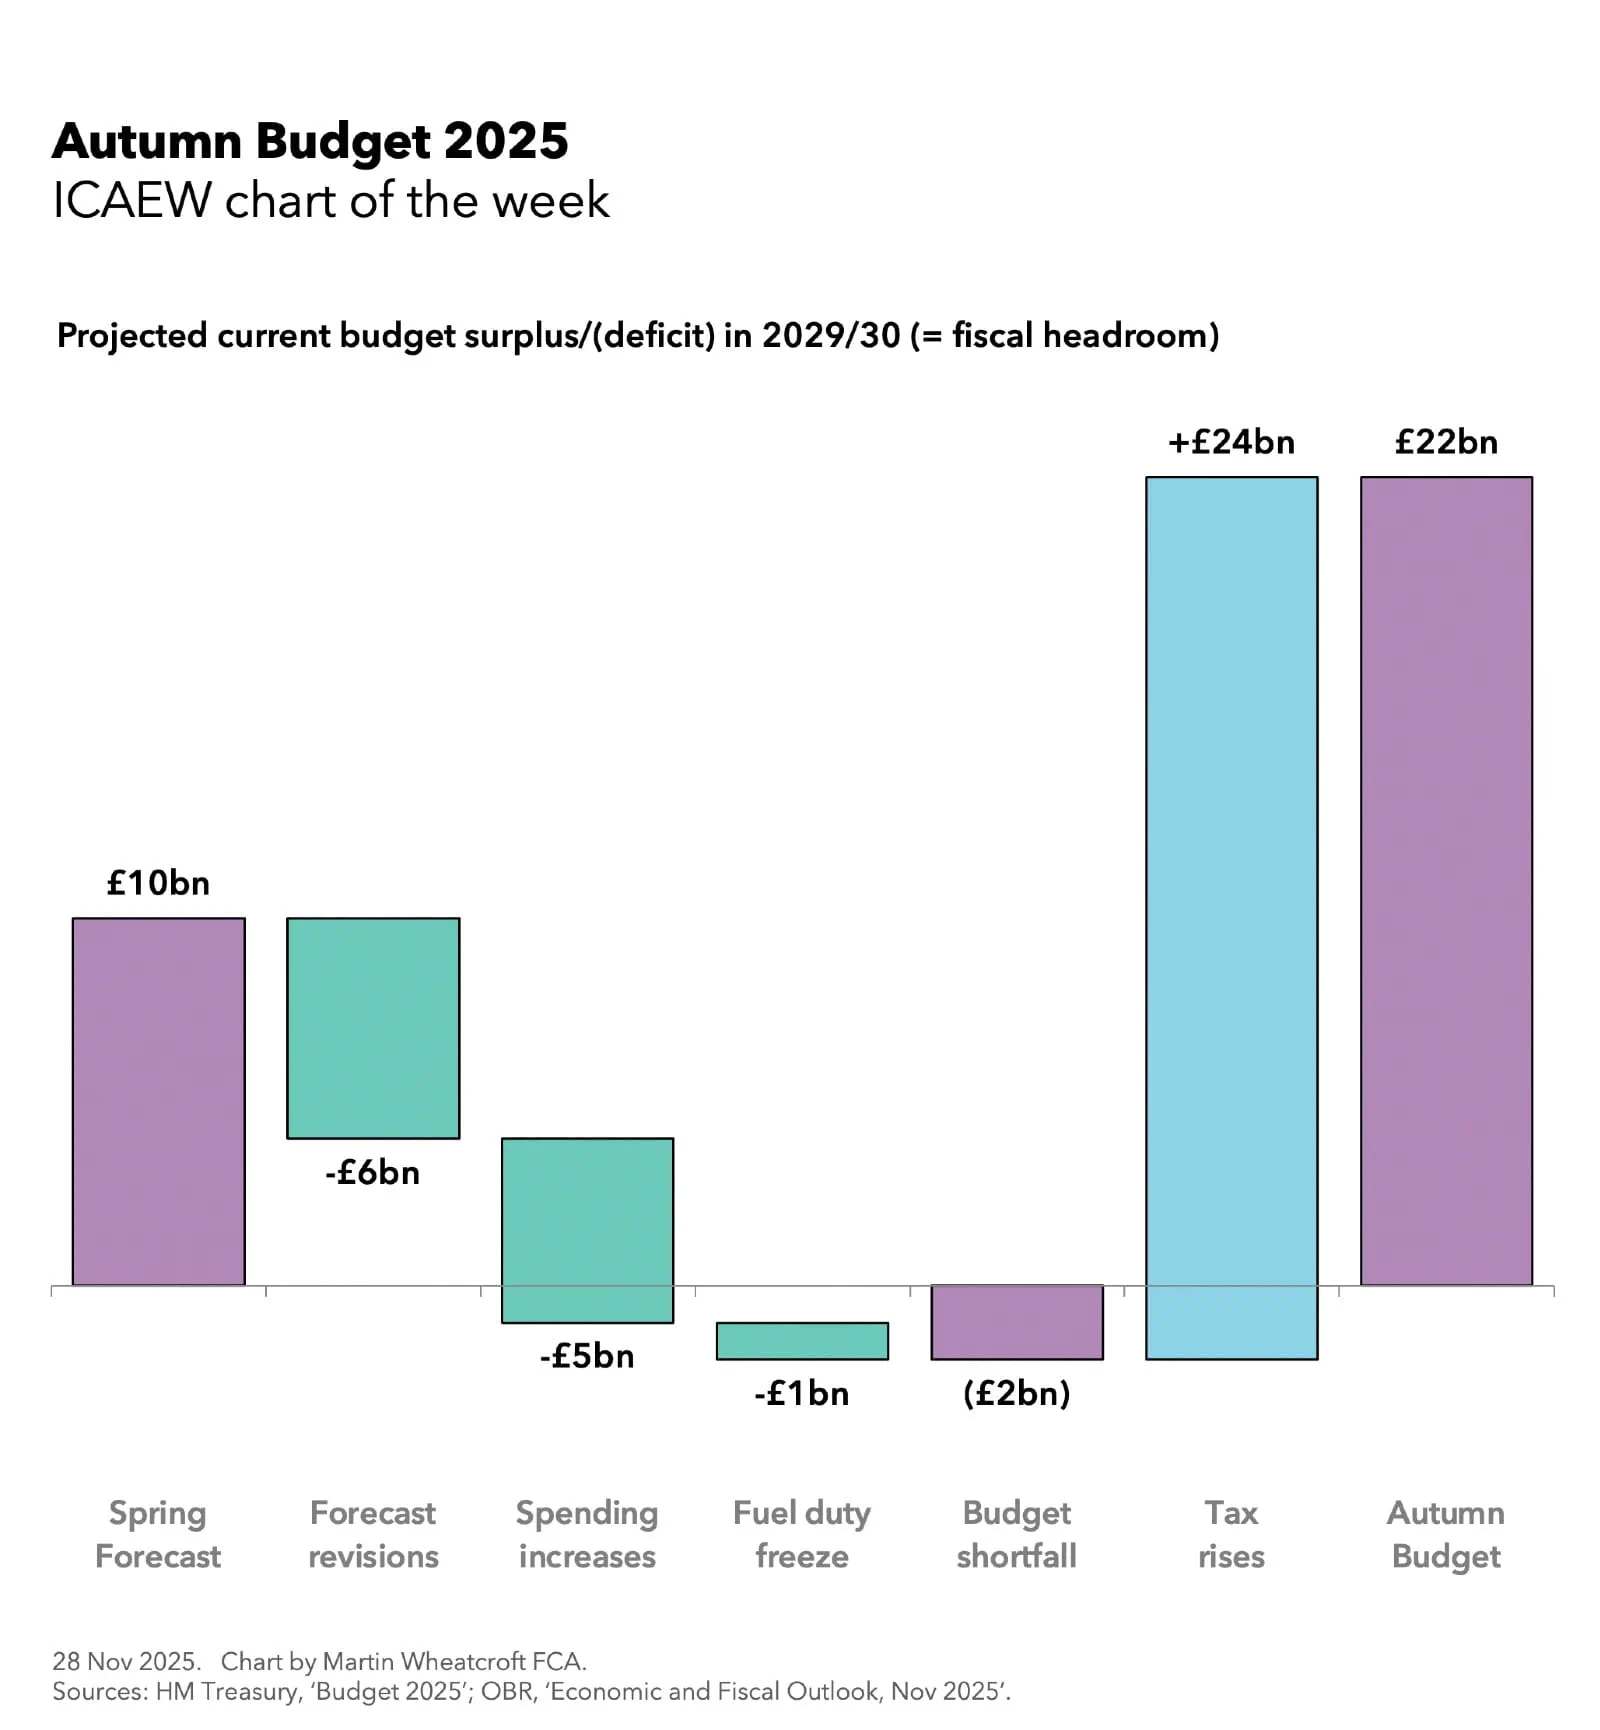
My chart this week for ICAEW looks at how the Chancellor used tax rises to refill and increase her budget headroom after forecast revisions and spending increases eliminated the projected current budget surplus for 2029/30.
The chart shows how the projected current budget surplus of £10bn in 2029/30 was reduced by £6bn of Office for Budget Responsibility (OBR) forecast revisions, by £5bn of spending increases announced in the Autumn Budget, and by £1bn from the freezing of fuel duties for yet another year.
Together these reduced the Chancellor’s headroom against her primary fiscal rule (to be in a current budget surplus by the fourth year of the fiscal forecast) from £10bn to minus £2bn – in effect breaching her fiscal rule before taking account of tax rises.
The Chancellor has then restored – and increased – her fiscal headroom to £22bn through a long list of tax rises that are anticipated to generate £24bn more in receipts in 2029/30.
Forecast revisions
The rumoured forecast downgrade from the OBR of £6bn in 2029/30 turned out to be much less significant than expected.
The OBR cut its receipts forecast for 2029/30 by £16bn a year because of weaker assumed productivity growth. But this was more than offset by a £30bn increase from higher nominal wages and prices, driven by both inflation and real wage growth, to add £14bn to receipts in that year – an increase not a decrease to the receipts side of the forecast.
This was offset by £20bn in higher current spending, of which £6bn was from higher uprating of welfare benefits and growth in claimants and caseloads, £6bn from government policy reversals on the winter fuel allowance and disability benefits, £4bn in higher debt interest, £2bn in higher local government spending, and £2bn in other changes.
The resulting deterioration of £6bn in the projected current budget surplus for 2029/30 was £14bn smaller than the £22bn deterioration anticipated by the Institute for Fiscal Studies (IFS) in its pre-Budget forecast (as used in our chart of the week on the Autumn Budget hole). The principal driver was £22bn in incremental receipts from higher inflation and higher real wage growth less £6bn in higher spending for similar reasons.
Because departmental budgets for 2026/27, 2027/28 and 2028/29 set out in the Spending Review earlier this year have not been increased for this higher level of inflation, the risk is that future Budgets will need to top up the amounts allocated to departments to deal with cost pressures that are likely to arise.
Spending increases
Current spending is projected to increase by £5bn in 2029/30, comprising £3bn to cover the annual cost of abolishing the two-child benefit cap, £1bn in higher debt interest, and £1bn in net other changes in non-interest current spending.
The OBR also announced that it had reduced its underspend assumption for departmental budgets during the latest spending review period (2026/27 to 2028/29 for current spending) by an average of £4bn a year to reflect the increased pressures on budgets from higher inflation. There was no similar adjustment to 2029/30 current spending as it is not covered by the spending review, but there is a risk that a similar adjustment may be needed by the time of the 2027 spending review.
Fuel duty freeze
Freezing fuel duties has become a consistent feature of Budgets since 2011, with the effect of reducing annual tax receipts in real terms by just under £1bn a year.
Given the current Chancellor has chosen to continue this practice in two successive Budgets, it is disappointing that fiscal forecasts have not reflected the anticipated £3bn additional reduction in tax receipts in 2029/30 if fuel duty is frozen again in the next three Budgets.
Tax rises
The Chancellor announced a total of £27bn in tax rises in the Budget (£26bn if the fuel duty freeze effective tax cut is netted off), but this is expected to generate £24bn in incremental tax receipts once behavioural responses and other indirect economic effects are adjusted for.
These tax rises are expected to generate the following amounts per year by 2029/30:
£8bn from extending the freezing of personal allowances (more ‘fiscal drag’).
£5bn from restricting the use of salary-sacrifice schemes to make pension contributions.
£2bn from increased income tax rates on property, savings and dividends.
£1.5bn from changes to writing-down allowances.
Just under £1.5bn from a mileage-based charge on electric cars.
Just over £1bn from gambling duty reform.
Just under £1bn from capital gains tax on employee ownership trusts.
Just under £0.5bn from a high value council tax surcharge.
Around £4.5bn from other tax measures.
£2bn from improved tax compliance and collection.
Higher headroom
The Chancellor chose to increase headroom against her principal (current budget) fiscal rule from £10bn last year to £22bn and to increase headroom in her secondary (debt) fiscal rule from £15bn to £24bn.
These are both positive in that they provide a much bigger cushion against potential forecast downgrades in the spring or autumn next year, reducing the risk of another round of significant tax rises in the Chancellor’s third Budget in 2026. It also helps that she is likely to gain around £15bn of extra headroom as the main fiscal rule moves to being tested in the third year of the forecast, which comes with a margin of permitted current budget deficit up to a maximum of GDP.
However, significant downside risks remain, so this outcome is far from assured. The Chancellor still faces the challenge of reviving a weak economy and delivering substantial efficiency savings if she is to keep public spending under control in the absence of more fundamental reform. That task is made harder by the risk of bailouts for local authorities and universities, and by continued pressure on the welfare budget.
The cumulative budget overrun has widened from £7bn to £10bn in seven months, reveals latest data from the Office for National Statistics.
The monthly public sector finances release, published by the Office for National Statistics (ONS) on 21 November 2025, reported a provisional shortfall between receipts and public spending of £17bn in October and a cumulative deficit of £117bn for the seven months then ended.
Martin Wheatcroft, external adviser on public finances to ICAEW, says: “The monthly public finances continue to disappoint, with the cumulative budget overrun widening from £7bn in the last release to £10bn for the seven months to October.
“While only slightly worse than expected, there were no rays of sunshine in these numbers for a beleaguered Chancellor trying to navigate her way through a series of political, economic and fiscal minefields surrounding the Autumn Budget.”
There was a £17bn shortfall between provisional receipts of £96bn and total public spending of £113bn in October 2025. This was £2bn better than the £19bn deficit incurred in October last year (£89bn receipts less £108bn total spending), but £3bn more than the budget of £14bn for the month.
Current spending of £108bn and net investment of £5bn in October were both in line with the £108bn and £5bn monthly averages incurred respectively during the first six months of the financial year.
October’s semi-annual advance tax payments meant that public sector net debt fell by £12bn during the month (from £2,917bn on 30 September to £2,905bn on 31 October 2025), with a net inflow of £29bn from working capital movements and lending activities more than offsetting the £17bn absorbed by the deficit.
The provisional £117bn deficit for the seven months to October 2025 was £9bn or 8% more than in the same seven months last year, and £10bn more than the £107bn that was budgeted. The £10bn overrun can be analysed as a £15bn adverse variance on the current budget deficit, offset by a £5bn underspend on net investment.
Table 1 highlights how year-to-date receipts of £672bn were 7% higher than the same period last year, with income tax up 8% from a combination of inflation and fiscal drag from frozen tax allowances. National insurance was up 19% as a result of the increase in employer national insurance from April 2025 onwards, and VAT receipts were up 4%, broadly in line with consumer price inflation.
Compared to last year, the 8% increase in spending to £756bn in the first seven months to October 2025 has principally been driven by public sector pay rises, higher supplier costs, the uprating of welfare benefits and higher debt interest.
Debt interest of £88bn was £9bn higher than for the first seven months of 2024/25, comprising a £7bn increase in indexation on inflation-linked debt as inflation rose again in 2025 and a £2bn increase in interest on variable and fixed-interest debt. The latter reflects a higher level of debt compared with a year ago, offset by a lower Bank of England base rate.
Net investment of £33bn in the first seven months of 2025/26 was £2bn or 6% higher than the same period last year. This comprised capital expenditure of £55bn (up by £2bn or 4%) and capital transfers (capital grants, research and development funding and student loan write-offs) of £20bn (up £2bn or 11%), less depreciation of £42bn (up by £2bn or 5%).
The deficit is budgeted to be £118bn for the full year ending 31 March 2026, comprising £107bn in the first seven months of the year to October 2025 and £11bn in the remaining five months.
The latter comprises budgeted deficits of £9bn and £11bn in November and December 2025, a forecast surplus of £23bn in January, and deficits of £1bn and £13bn in February and March 2026.
Table 2 summarises how the government borrowed £95bn in the first seven months of the financial year to take public sector net debt to a provisional £2,905bn on 31 October 2025. This comprised £117bn in public sector net borrowing (PSNB) to fund the deficit, less a £22bn net inflow from working capital movements and government lending.
The table also illustrates how the debt to GDP ratio increased by 1.0 percentage points from 93.5% of GDP at the start of the financial year to 94.5% on 31 October 2025. Incremental borrowing of £95bn, equivalent to 3.2% of GDP, was partly offset by 2.2 percentage points from the ‘inflating away’ effect of inflation and economic growth on GDP, the denominator in the net debt to GDP ratio.
Table 2: Public sector net debt and net debt/GDP
7 months to Oct
2025/26 £bn
2024/25 £bn
PSNB
117
108
Other borrowing
(22)
10
Net change
95
98
Opening net debt
2,810
2,686
Closing net debt
2,905
2,784
PSNB/GDP
4.0%
3.8%
Other/GDP
(0.8%)
(0.4%)
Inflating away
(2.2%)
(3.1%)
Net change
1.0%
0.3%
Opening net debt/GDP
93.5%
94.4%
Closing net debt/GDP
94.5%
94.7%
Public sector net debt on 31 October 2025 of £2,905bn comprised gross debt of £3,352bn, less cash and other liquid financial assets of £447bn.
Public sector net financial liabilities were £2,583bn, which included public sector net debt plus other financial liabilities of £715bn, less illiquid financial assets of £1,037bn. Public sector negative net worth was £926bn, comprising net financial liabilities less non-financial assets of £1,657bn.
Caution is needed with respect to the numbers published by the ONS, which are repeatedly revised as estimates are refined and gaps in the underlying data are filled. This includes local government, where the numbers are only updated in arrears and are based on budget or high-level estimates in the absence of monthly data collection.
This month was no different, with the ONS revising previously reported numbers for six months to September 2025 and for previous financial years. However, on this occasion, the changes made did not affect the aggregate totals when rounded to the nearest billion pounds.
Regular updates to economic statistics resulted in an upward revision to nominal GDP and a consequential 0.2 percentage point reduction in the ratio of public sector net debt to GDP from 95.3% to 95.1% as of 30 September 2025.
My chart for ICAEW this week shows how the high level of public debt is the main factor shaping next week’s Autumn Budget.
In the run up to next week’s Autumn Budget it has become clear that the Chancellor has very little room for manoeuvre.
In past fiscal events, a moderate downgrade in the economic and fiscal forecasts (see last week’s chart of the week) would typically be dealt with by allowing borrowing to rise, albeit in combination with a small cut in planned public spending (often to capital expenditure) and perhaps some minor tax rises.
This time is different. Borrowing – the normal safety valve for adverse forecast changes – is constrained by the existing high level of debt and by government’s existing plan to borrow substantial sums over the next five years, as illustrated by our chart of the week.
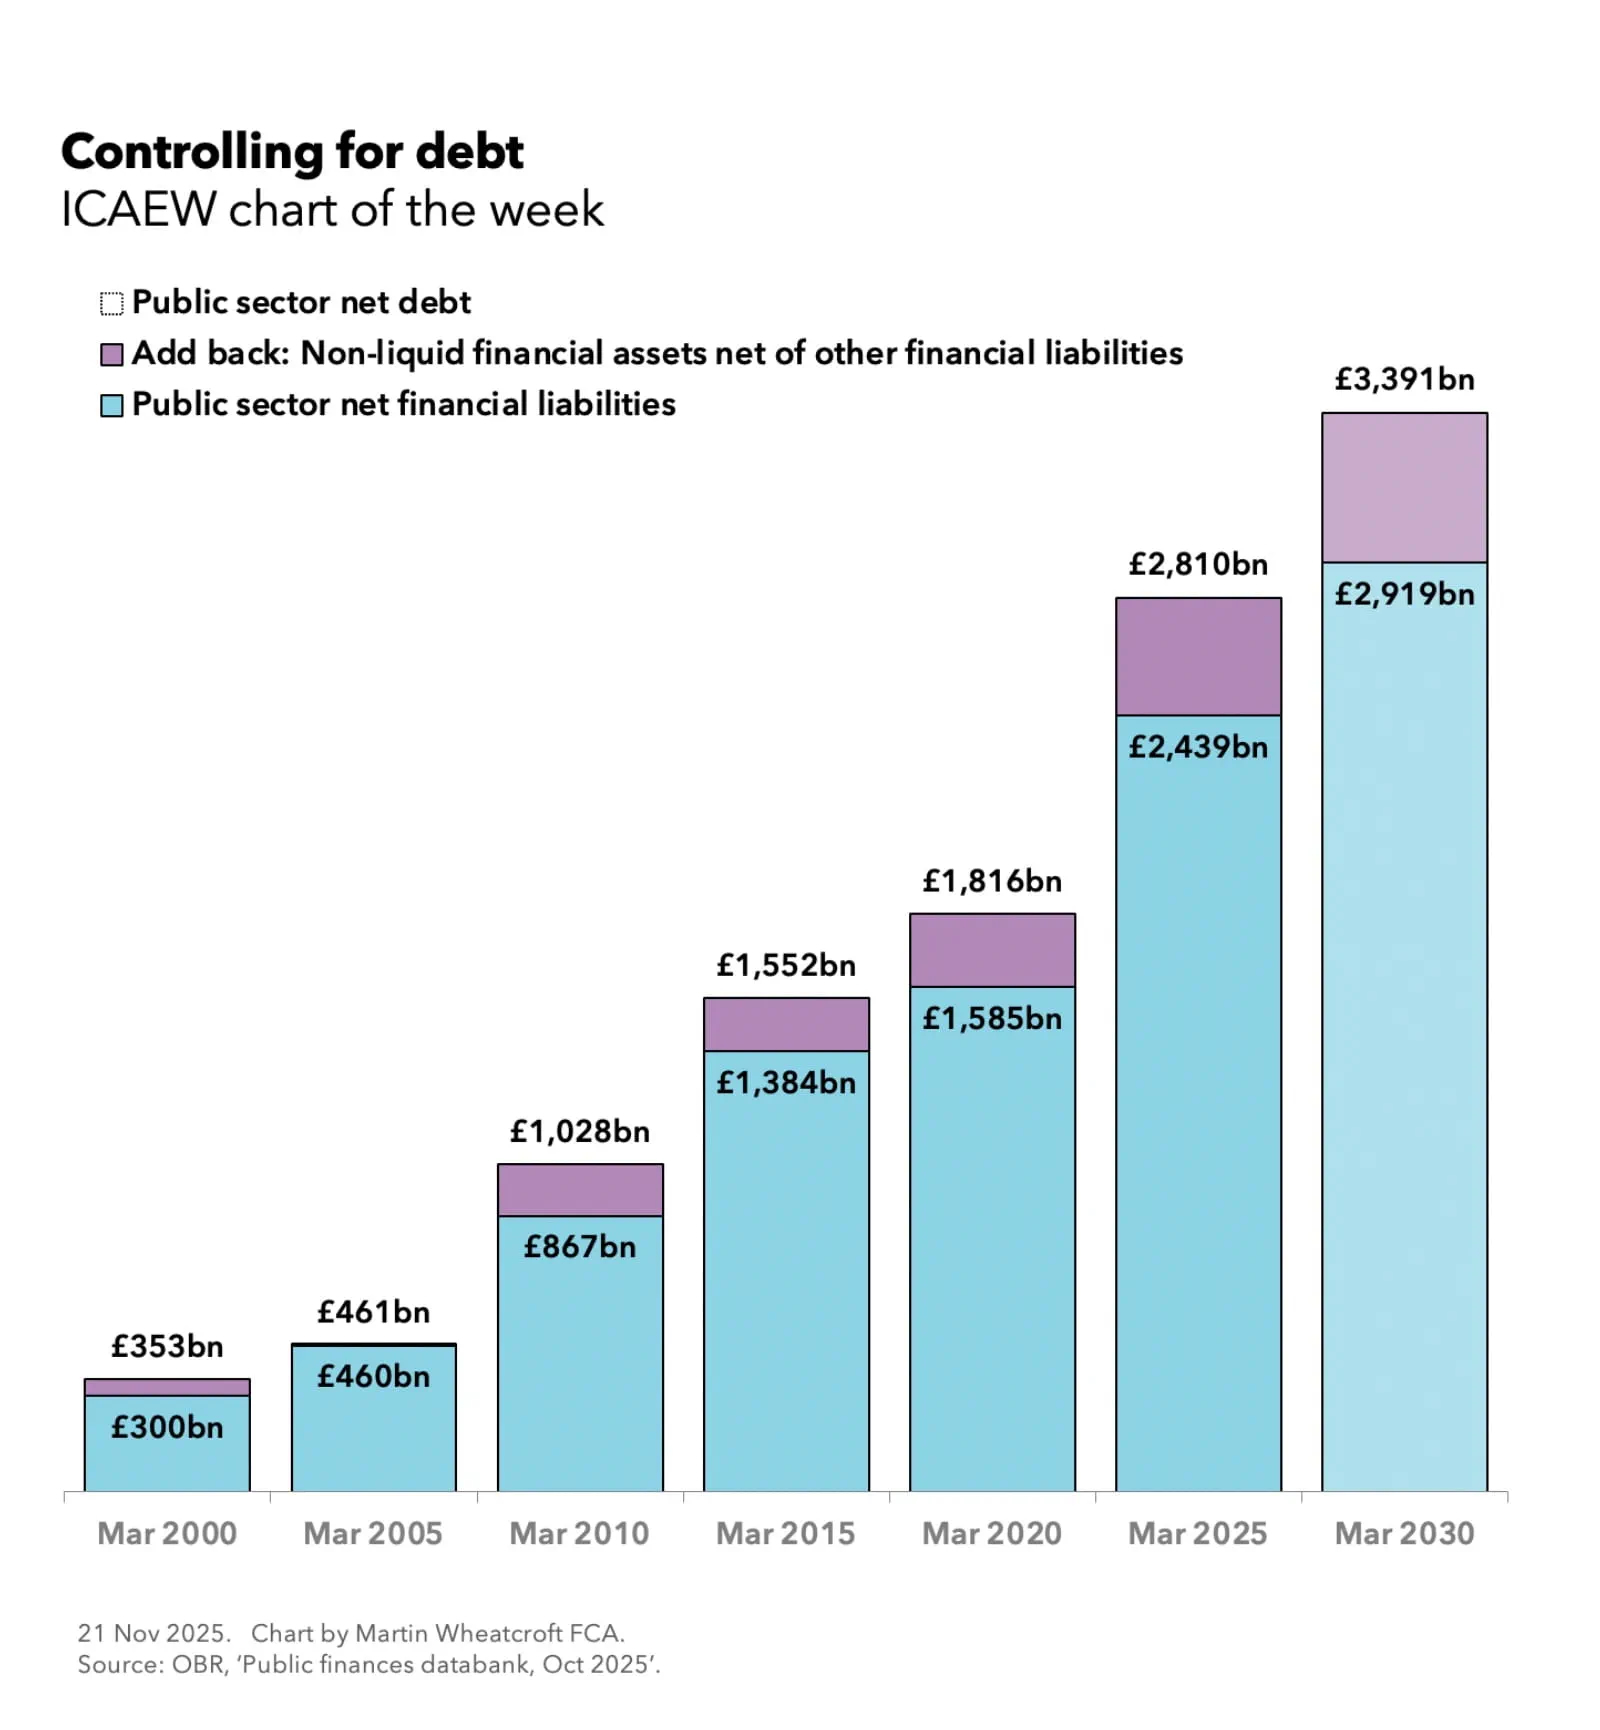
As my chart for ICAEW sets out, public sector net debt has risen over the past quarter of a century from £353bn on 31 March 2000 to £461bn in 2005, £1,028bn in 2010, £1,552bn in 2015, £1,816bn in 2020 and £2,810bn in 2025. It is forecast to rise further to £3,391bn on 31 March 2030.
Although the planned increase of £581bn over the coming five years is less than the £994bn increase over the previous five years, the latter included both the pandemic and an unexpected energy crisis.
The chart also shows how public sector net financial liabilities (PSNFL), the measure of debt that the Chancellor uses for her fiscal rules, increased from £300bn on 31 March 2000 to £2,439bn on 31 March 2025, with a planned rise of £480bn to £2,919bn due to take place on 31 March 2030.
The Chancellor’s debt fiscal rule is for the ratio of PSNFL to GDP starting to fall by 2029/30, or – in other words – for the rate at which debt is increasing to be slower than the rate of growth in the economy in four years’ time. The hope is that the borrowing the government is doing now to invest in infrastructure and economic development will speed up economic growth over that time, but unfortunately that is not yet showing up in the forecasts, which are going in the opposite direction.
With higher borrowing ruled out, the next option would be to look at spending. This also looks difficult as the Spending Review earlier this year locked in departmental budgets for the next few years (to 2028/29 for current spending and to 2029/30 for capital investment). Likewise, significant cuts in welfare spending also appear unlikely given the government’s failure to persuade its MPs to back a plan to cut back on disability and illness benefits and hints that the government wants to lift the two-child benefit cap. The Chancellor could potentially re-open the Spending Review, but that would risk spending going up not down given the continued pressures on health and the criminal justice systems, not to mention the international pressure from President Trump and others to accelerate increases in defence spending.
With other options such as raising the level of net inward migration also ruled out, that leaves taxation as the only real lever available to the Chancellor.
The flood of speculation ahead of next week’s Autumn Budget 2025 has ranged from manifesto-busting increases in one of the ‘big three’ taxes (income tax, VAT and national insurance) and fiscal drag (from the extension of freezes in tax allowances), to a long list of tax raising ideas to bring in just a little bit more money here and there that might together add up to a substantial amount.
At this point it seems that little can be ruled out.
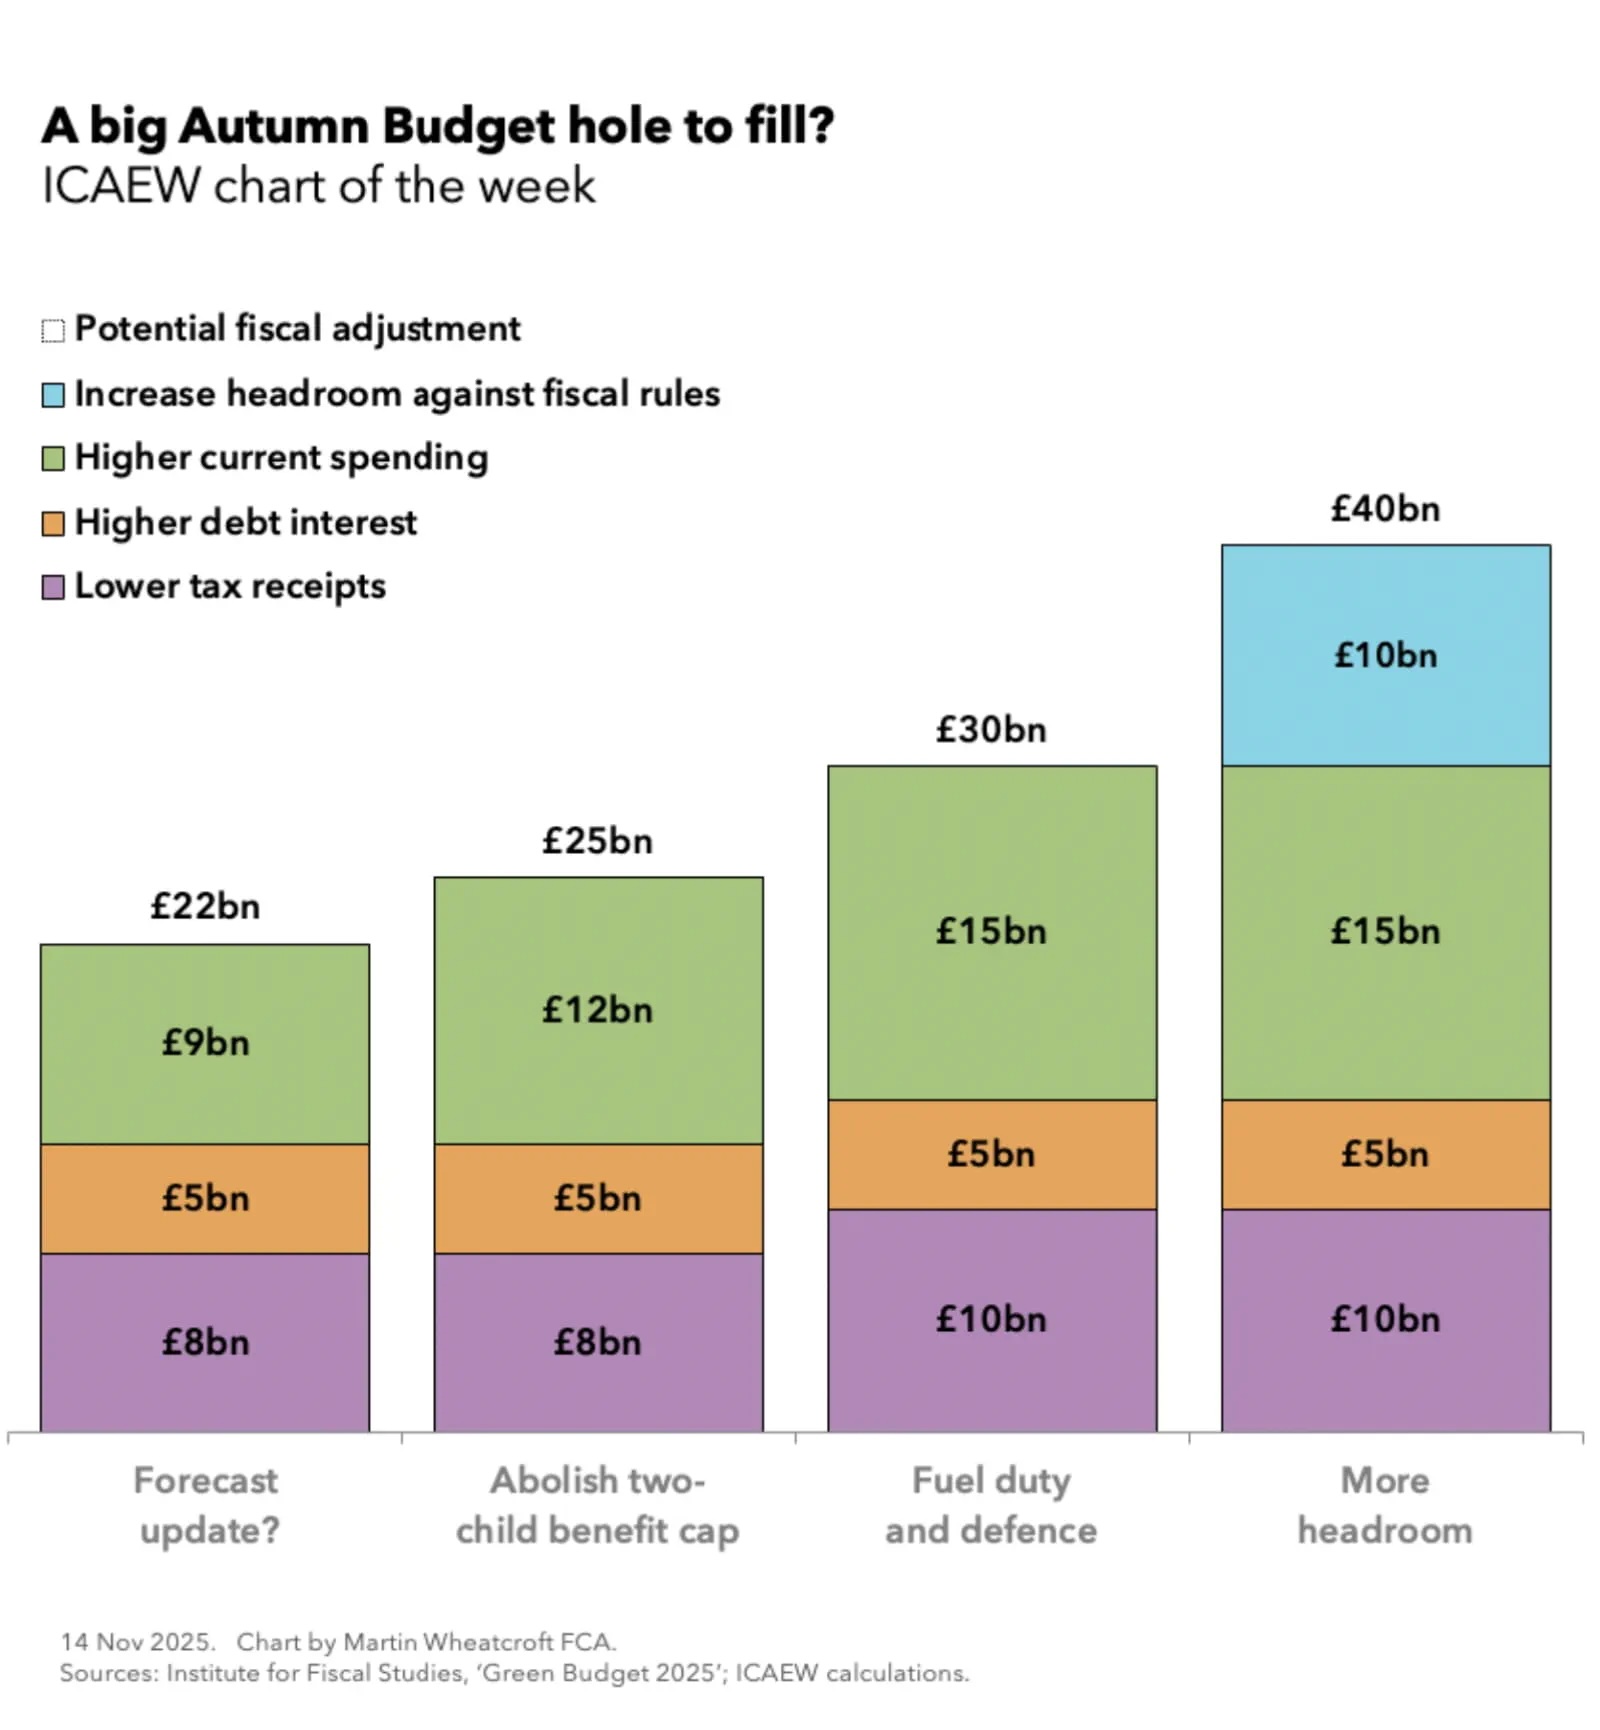
My chart for ICAEW this week takes a look at the £40bn ‘hole’ in the public finances that the Chancellor may have to fill when she presents the Autumn Budget 2025 to Parliament on Wednesday 26 November.
There are two really big questions that most of us have for the Chancellor about the Autumn Budget 2025. Firstly, just how much money does she need to find? Secondly, where is she is going to find it?
My chart for ICAEW this week focuses on the first question – how much will the Chancellor need to find (in tax rises or spending cuts) to stick within her fiscal rules?
Speculation ranges from just under £20bn a year up to as much as £50bn depending on who you talk to, with the consensus being somewhere in the region of £30bn or £40bn.
The starting point for the chart is the official OBR projection that the Chancellor has already received. As we don’t have access to that, we have cribbed from the Institute for Fiscal Studies (IFS) Green Budget 2025 report, an independent ‘green paper’ pre-legislative report that provides an in-depth analysis of the economic and fiscal situation facing the UK that also takes a look at potential options available to the Chancellor.
Based on an updated economic forecast prepared by Barclays, the IFS think that the OBR’s March 2025 projected current budget surplus of £10bn in 2029/30 could be revised down to a projected current budget deficit of £12bn – a £22bn deterioration.
The numbers calculated by the IFS indicate £8bn lower tax receipts, £5bn higher debt interest, and £9bn higher current spending. The lower tax receipts and higher debt interest reflect a less favourable economic outlook than anticipated by the OBR back in March, while the latter consists of £1bn from the partial roll-back of cuts to the winter fuel allowance, £5bn from the failure to enact previously planned cuts to disability benefits, and £3bn from the effect of higher than previously forecast inflation on the uprating of the state pension and other welfare benefits.
If the OBR’s updated projections were to align with this scenario, then the Chancellor would need to find £22bn to get back to a projected current budget surplus of £10bn in 2029/30, assuming she decides again to give herself £10bn of headroom against her primary fiscal rule of a current budget balance.
We don’t know how these numbers compare with the numbers that the OBR are working on, but we do know that the OBR has been reviewing its assumptions for productivity growth, where it has proved consistently over-optimistic in previous forecasts. The IFS estimate that just a 0.1 percentage point downgrade in annual productivity growth would reduce the current budget balance by around £7bn in 2029/30, highlighting how sensitive the numbers are to relatively small changes. The IFS assume a downgrade of between 0.1 and 0.2 percentage points in their projection, although some rumours suggest the OBR has been considering a downgrade of as much as 0.3 percentage points.
The Chancellor has dropped a clear hint that she is going to abolish the two-child limit in the Autumn Budget as part of the government’s efforts to tackle child poverty, with the IFS and the Resolution Foundation both estimating that this could cost the exchequer between £3bn and £4bn a year by 2029/30. This would take the potential ‘hole’ up to £25bn.
For the purposes of the chart, I have also added in £5bn for further policy changes. Firstly, there is a good chance that the Chancellor will choose to make the existing 5p ‘temporary’ cut in fuel duties permanent at a cost of £2bn a year. This is currently scheduled to be reversed on 1 April 2026, alongside the expected end of the annual freeze in fuel duties – a measure that, if continued, could cost a further £3 billion a year by 2029/30.
The government is also under significant pressure – from President Trump and other NATO allies in particular – to accelerate increases in the defence budget to meet the new NATO target for spending on defence and security of 3.5% of GDP. Although the NATO target includes capital expenditure (which is not part of the current budget surplus or deficit), we have included a proxy amount of £3bn a year by 2029/30 for additional operating expenditure on defence.
This brings the potential funding requirement to roughly £30 billion, if the Chancellor aims to maintain £10bn of headroom against her fiscal rule of achieving a current budget balance in the fourth year of the forecast.
Unfortunately, as the government has discovered over the past year, such a small margin – less than 0.3% of GDP – is hugely problematic. Relatively small changes in the OBR’s assumptions or in actual economic performance can easily use up all the headroom, leading (as we have seen) to endless speculation about what the Chancellor is going to have to do to bring the public finances back under control.
The Chancellor is therefore expected to provide herself with a bigger cushion to reduce the risk of having to come back to raise taxes for a third time. The chart thinks she is likely to choose to double the level of headroom as a minimum – from £10bn to £20bn – with some economic commentators suggesting that an even larger cushion might be necessary.
The IFS point out in their report that extra headroom may be needed in any case because of the Chancellor’s second ‘debt’ fiscal rule, which is for public sector net financial liabilities to be falling as a share of GDP by the fourth year of the fiscal forecasts. Although she could cut the capital expenditure already budgeted for 2029/30 to remain within the fiscal rule, the Chancellor has said she wishes to avoid doing so.
Whatever happens, it looks like the Autumn Budget 2025 is going to be a pretty big deal.