Each month I write an article for ICAEW on the monthly public sector finance release. Here are my most recent articles:
Public sector net debt hits £3tn ahead of budget
Rising inflation and budget overruns provide a difficult backdrop for John Healey as he prepares for his first fiscal event. The Chancellor is under pressure to provide more support for rising energy bills, but the challenges to balance spending are mounting.
Budget overrun widens as public finances disappoint
The triple whammy of geopolitical uncertainty, persistent inflation and rising gilt yields are squeezing the public purse as the Chancellor prepares for his first budget.
Read More
www.icaew.com
UK net debt in touching distance of £3.0tn
Latest data confirms that the UK’s public finances remain weak, despite taxpayers facing the highest tax burden since the 1960s. The Chancellor faces significant challenges if he is to increase public spending, says ICAEW.
Our chart this week looks at how the five-year fiscal forecasts have consistently proved too optimistic in recent years, something to bear in mind as the budget approaches.
Read More
www.icaew.com
Chart of the week: disposable income
Our chart this week looks at how income is distributed across UK households with a median equivalised household disposable income of £3,265 per month and an equivalised average of £3,800 per month.
Read More
www.icaew.com
Chart of the week: UK productivity remeasured
Our chart this week looks at how the ONS is changing how it calculates labour productivity – one of the most important factors driving economic growth.
Read More
www.icaew.com
Chart of the week: public sector workforce
Our chart this week looks at how one third of the 6.2m public sector workforce work for the NHS while 9% work for the Civil Service.
Read More
www.icaew.com
Chart of the week: OBR long-term fiscal forecast
Our chart this week shows how alternative scenarios go off the chart in the OBR’s latest long-term fiscal projections.
Read More
www.icaew.com
Chart of the week: long-term interest rates
Our chart this week highlights how long-term borrowing costs have changed over the past year in Japan, Germany, France, the US and the UK.
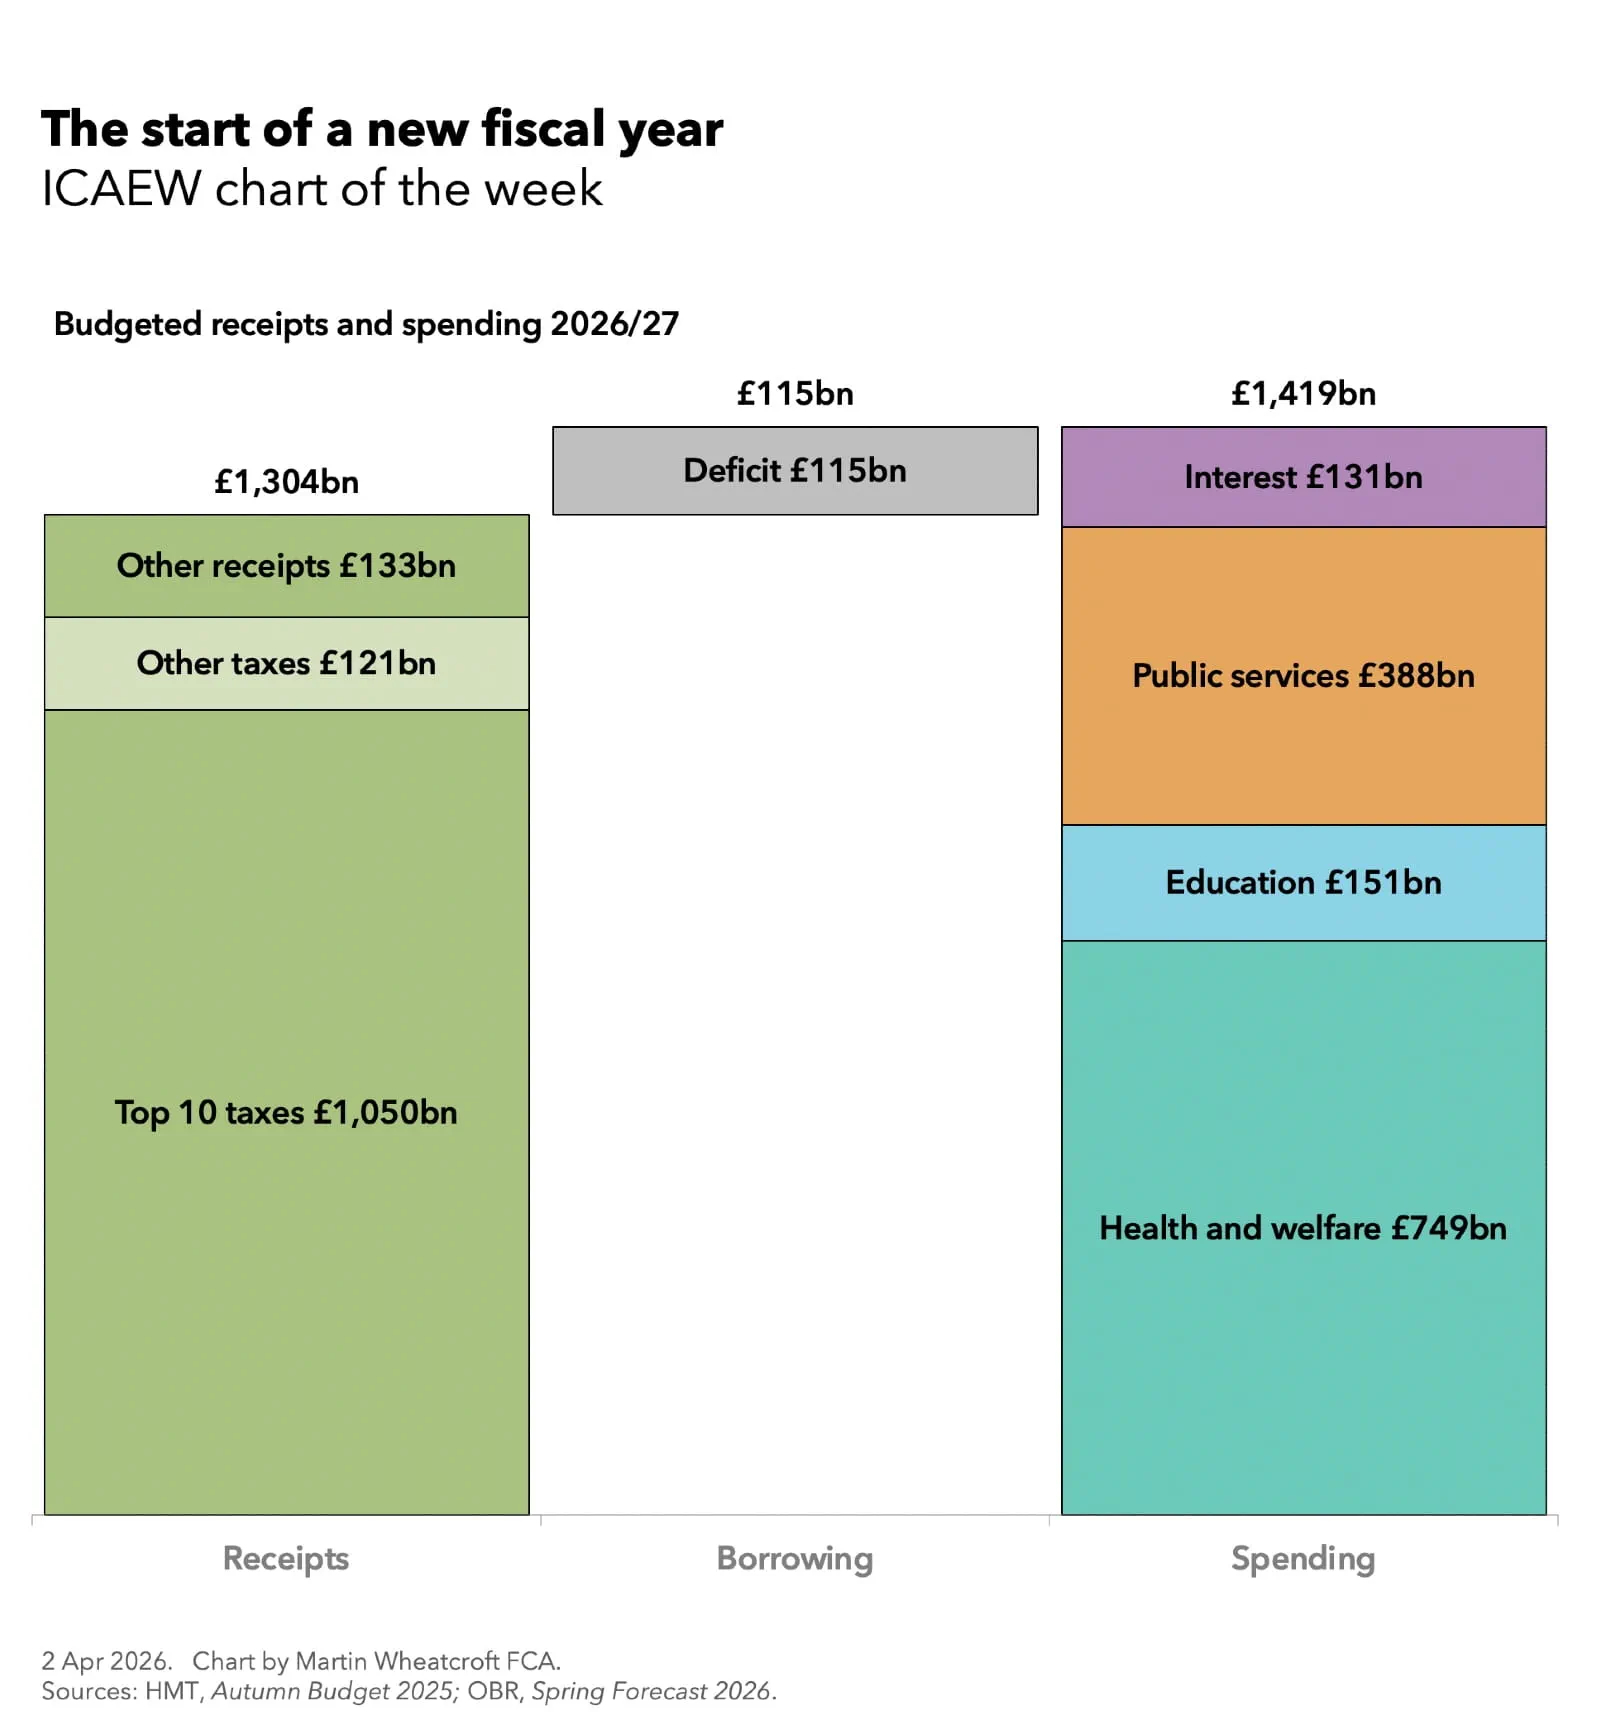
My first chart of the financial year starting 1 April 2026 for ICAEW looks at the government’s £1.4tn budget for 2026/27.
My chart fir ICAEW this week is on the public sector budget for the 2026/27 financial year which began on 1 April 2026, showing how there is expected to be a shortfall of £116bn between anticipated receipts of £1,304bn and planned spending of £1,419bn.
This is equivalent to a deficit of 3.6% of GDP, calculated as receipts of 41.2% of GDP less total managed expenditure of 44.8% of GDP.
The chart highlights how the top 10 taxes are expected to generate £1,050bn (81% of total receipts), with all other taxes contributing £121bn (9%) and other receipts generating £133bn (10%).
The top 10 taxes comprise: income tax which generates £360bn, VAT (£220bn), employer national insurance (£155bn), corporation tax (£102bn), employee and self-employed national insurance (£57bn), council tax (£54bn), business rates (£37bn), fuel duties (£24bn), capital gains tax (£21bn) and property transaction taxes (stamp duty in England) generating £20bn.
The remaining £121bn of tax receipts comprises £84bn from the next 10 largest taxes: environmental duties (£16bn), alcohol duties (£13bn), vehicle excise duty (£10bn), inheritance tax (£9bn), insurance premium tax (£9bn), tobacco duties (£7bn), air passenger duty (£5bn), stamp duty on shares (£5bn), customs duties (£5bn) and the apprenticeship levy (£5bn), and £37bn from all other taxes and duties.
Other receipts comprise £87bn from operating surpluses (including social housing rents and the profits of public corporations), £43bn in interest and dividends (on investments and cash balances), and £3bn other receipts.
On the spending side, the chart illustrates how the £749bn budgeted for health and welfare is more than half of the total (approximately 53%), while education spending is budgeted to be £151bn (11%), public services outside of health, social care and education amount to £388bn (27%) and interest is forecast to be £131bn (9%).
Health and welfare spending comprises £401bn on welfare (including the state pension), £294bn on health (principally the NHS), and social care provision of £54bn. Budgeted spending on public services outside of health, social care and education include defence and security of around £70bn, transport £69bn, public order and safety £62bn, industry, agriculture and employment £56bn, and housing and environment £51bn, together with £80bn across the hundreds of other public services provided by central and local government.
The planned borrowing to fund the deficit of £116bn, the difference between receipts and total managed expenditure, excludes £15bn in other borrowing to fund government lending activities and working capital movements, with public sector net debt scheduled to rise above £3tn during the coming financial year.
The problem for the Chancellor – and for all of us – is that the actual numbers for 2026/27 could be significantly worse from the budgeted amounts presented in our chart. Not only is she already under significant pressure to increase defence spending and alleviate student loans (amongst many other spending challenges), but the conflict with Iran will make the situation even more challenging for both the government and the nation.
On that cheery note, we would like to wish you all the best for the new (financial) year.
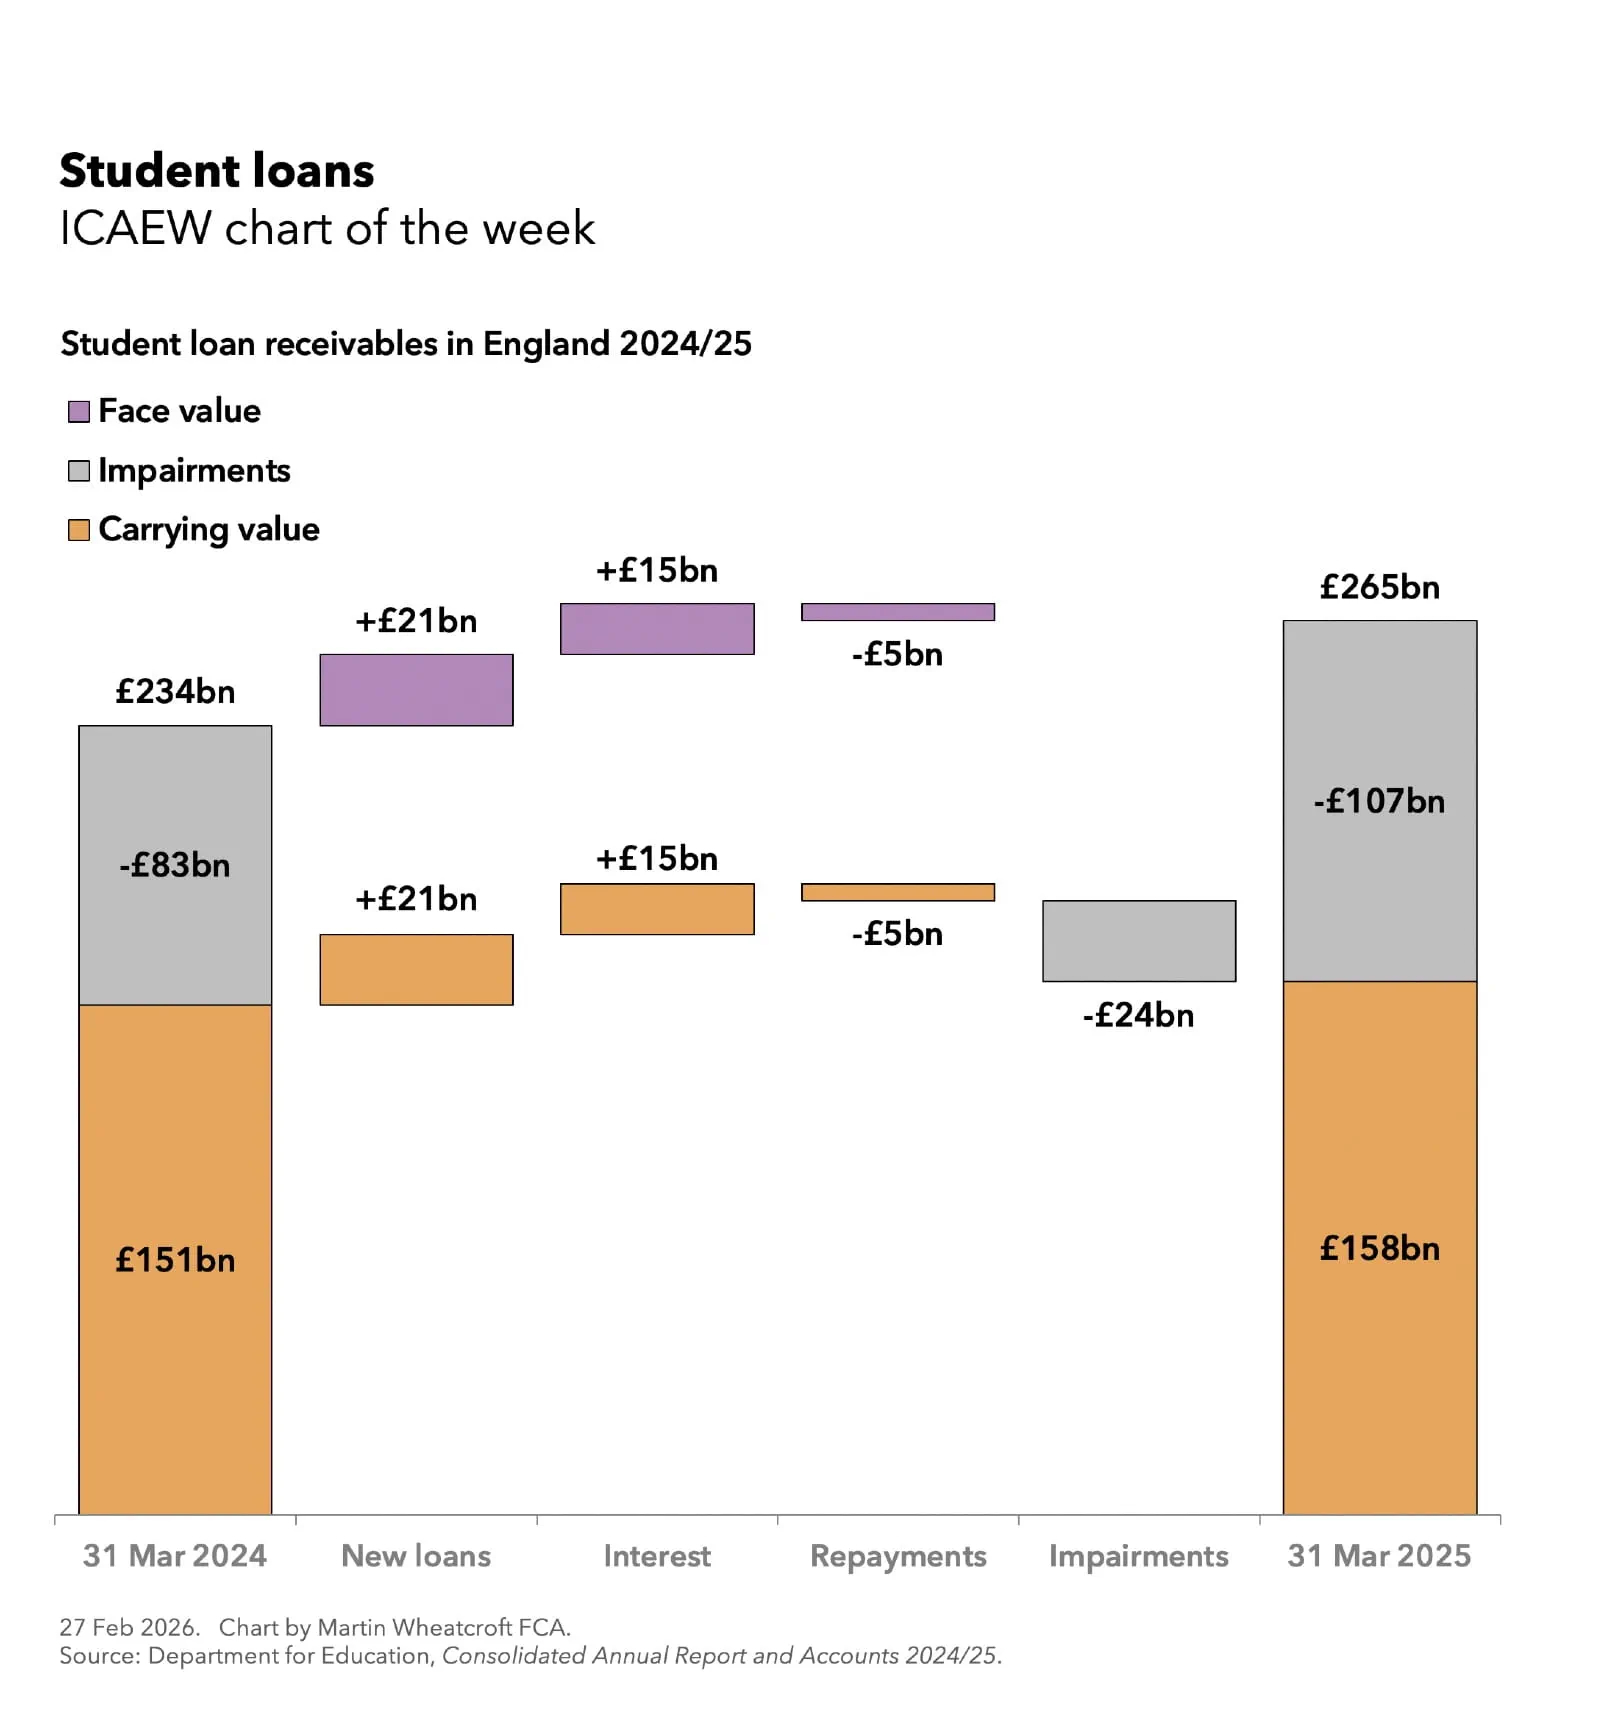
My chart for ICAEW this week looks at how the Department for Education has impaired 40% of the value of its student loans outstanding as at 31 March 2025.
This is before taking account of the government’s decision to freeze repayment thresholds over the next three years, which should reduce the impairment to 38%.
According to the Department for Education’s consolidated annual report and accounts 2024/25, the face value of student loans in England increased from £234bn to £265bn during the year ended 31 March 2025. The movements comprised £21bn in new loans advanced to students during the year and £15bn of added interest less £5bn in repayments.
As our chart also illustrates, the carrying value in the department’s balance sheet increased from £151bn to £158bn, once an impairment of £24bn during the year is taken into account – increasing the cumulative impairment from £83bn to £107bn.
This is an increase in the impairment percentage from approximately 35% on 31 March 2024 to 40% on 31 March 2025 based on the fair value of the student loan portfolio calculated by the department.
The £21bn impairment can be analysed between an immediate £6bn impairment on the inception of new loans issued during the year (approximately 30% of their face value) and £15bn from the recalculation of the fair value of loans at the end of the financial year, co-incidentally pretty much offsetting the interest added to the loans.
The loan portfolio can be broken down between Plan 1 loans for undergraduate courses that started before 1 September 2012 (face value £28bn less £14bn cumulative impairment = fair value £12bn on 31 March 2025), Plan 2 loans for undergraduate courses between 2012 and 31 August 2023 (£216bn – £87bn = £129bn), Plan 3 loans for postgraduates (£7bn – £1bn = £6bn) and Plan 5 loans for undergraduate courses starting from 1 September 2023 onwards (£14bn – £3bn = £11bn).
The recent controversy around student loans has been around the interest rates charged on student loans, and in particular those of Plan 2 loans owed by the majority of former students, which are based on RPI + 3%. In the year from 1 September 2025 the interest rate is 6.2% for those earning £51,245 (£4,270 a month) or more reducing to 3.2% for those earning £28,470 (£2,372 a month) or less.
This often means that the balance outstanding grows by more than the amount repaid. For example, someone earning £42,000 (£3,500 a month) with Plan 2 student loans totalling £50,000 on 1 September 2025 would see £2,490 (at an interest rate fractionally under 5%) added to their loan over the year to 31 August 2026. As their repayments would be equal to approximately £1,220 (being 9% on their earnings above the Plan 2 threshold of £28,470) their debt would rise to £51,270.
Most current undergraduates are under Plan 5, which has a flat interest rate of RPI irrespective on income but a lower £25,000 repayment threshold which could see them pay a lot more over their 40-year terms than those on the 30-year Plan 2 loans. In our example, a graduate on £42,000 a year with £50,000 in Plan 5 loans brought forward would see £1,600 added in interest and repay £1,530 to result in a much smaller increase in their outstanding loan balance.
With the government suggesting that they are going to have another look at the way student loans are designed, many graduates will be hoping that reform is the air.
This week’s chart looks at how the government is relying on a strong inflow from self-assessment and employee bonuses to meet its revised fiscal targets for the financial year to March 2026.
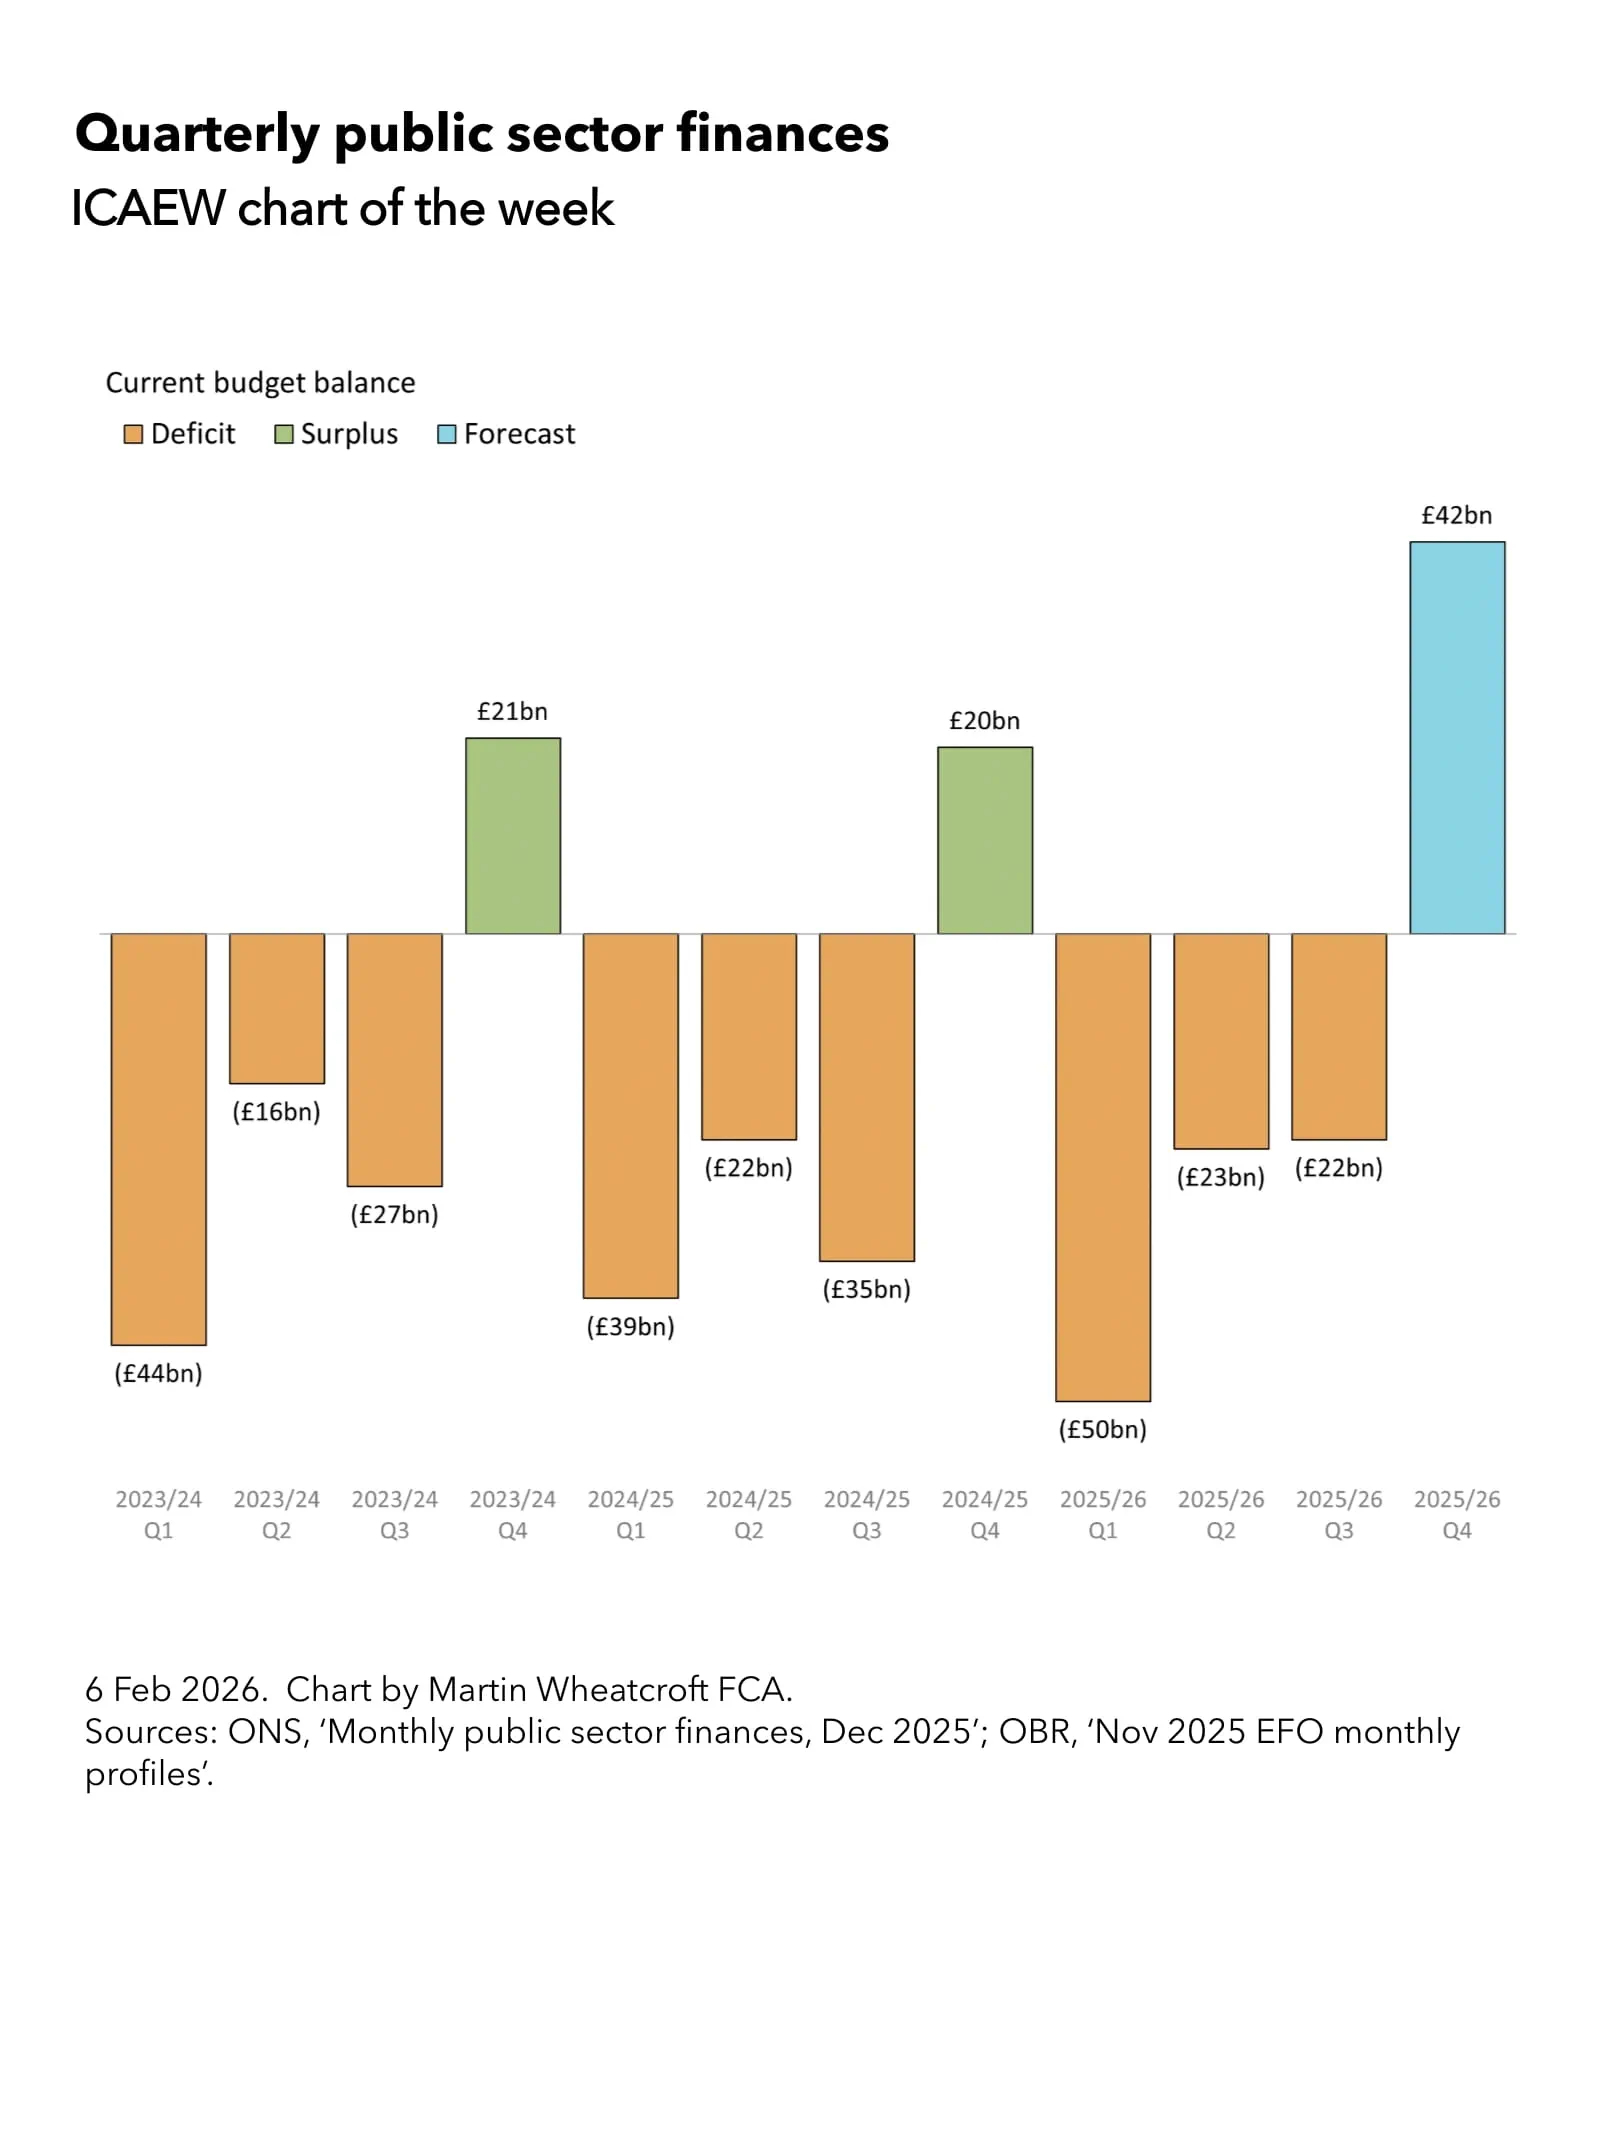
Our chart this week illustrates the financial results for the UK public sector before net investment expenditure over the twelve quarters to March 2026, including the latest Office for Budget Responsibility (OBR) forecast for the final quarter.
According to the Office for National Statistics (ONS), the full-year current budget deficit – current receipts less current spending including depreciation – was £66bn in 2023/24 and £76bn in 2024/25, while the latest OBR forecast is for a current budget deficit of £52bn for 2025/26.
The current budget balance is different to the headline deficits of £135bn, £152bn and the OBR forecast of £138bn for 2023/24, 2024/25 and 2025/26 as deficits also include net investment spending of £69bn, £76bn and £86bn respectively.
Our chart breaks the current budget balance down by quarter, showing how there were current budget deficits of £44bn, £16bn and £27bn in the first three quarters of 2023/24 and a surplus of £21bn in the fourth quarter of 2023/24. This was followed by current budget deficits of £39bn, £22bn and £35bn and a current budget surplus of £20bn in 2024/25.
Current budget deficits of £50bn, £23bn and £22bn were reported for the first three quarters of the current financial year, with the OBR forecasting a current budget surplus of £42bn in the final quarter. This would bring the total current budget deficit to £53bn, £1bn more than the OBR’s November 2025 full-year forecast of £52bn because of variances in the third quarter.
As the chart illustrates, there is a £64bn swing between a current budget deficit of £22bn in the third quarter of 2025/26 to a current budget surplus of £42bn in the fourth quarter.
This quarter-on-quarter swing can be analysed between:
a £46bn contribution from 2024/25 self-assessment tax returns, most of which were submitted in January 2026 (£28bn income tax and £18bn capital gains tax);
£20bn from higher PAYE income tax and national insurance receipts (principally driven by employee bonuses and first calendar quarter pay rises);
£5bn from lower interest charges (as interest rates and inflation have fallen); less
a net £7bn swing in all other receipts and expenditures across central and local government and public corporations.
The £64bn swing this year is higher than the £55bn swing between the third and fourth quarters of 2024/25. The difference is mainly due to an anticipated £7bn extra from capital gains taxes, principally driven by the rate increases that took effect in October 2024, half-way through the self-assessment tax return period.
The lower current budget deficit in the third quarter compared with a year previously is primarily because of the employer national insurance tax rise from 1 April 2025. This rise also benefited the first quarter of 2025/26 but that was offset by much higher interest charges (principally on inflation-linked debt) amongst other drivers.
Some of the benefit of the swing in the current budget balance in the fourth quarter of the current financial year will be offset by higher net investment spending in the typical end-of-year ‘capital rush’. However, the achievement of the £138bn revised deficit forecast for the current year is primarily in the hands of the taxpayers who submitted their tax returns in January and how well employers operating on a calendar performance year basis did in 2025 and hence the bonuses that they will pay out by the end of March.
We will hope to get a sense of the position in self-assessment tax returns when the January public sector finances are published by the ONS later this month, but we will likely need to wait until April (when the March public sector finances are published) to fully understand what is happening with bonuses.
My chart for ICAEW this week looks at civil service numbers given that restructuring is in the air in Whitehall. Will the government really be able to deliver on its plans to cut administration costs and civil service headcount over the coming three years?
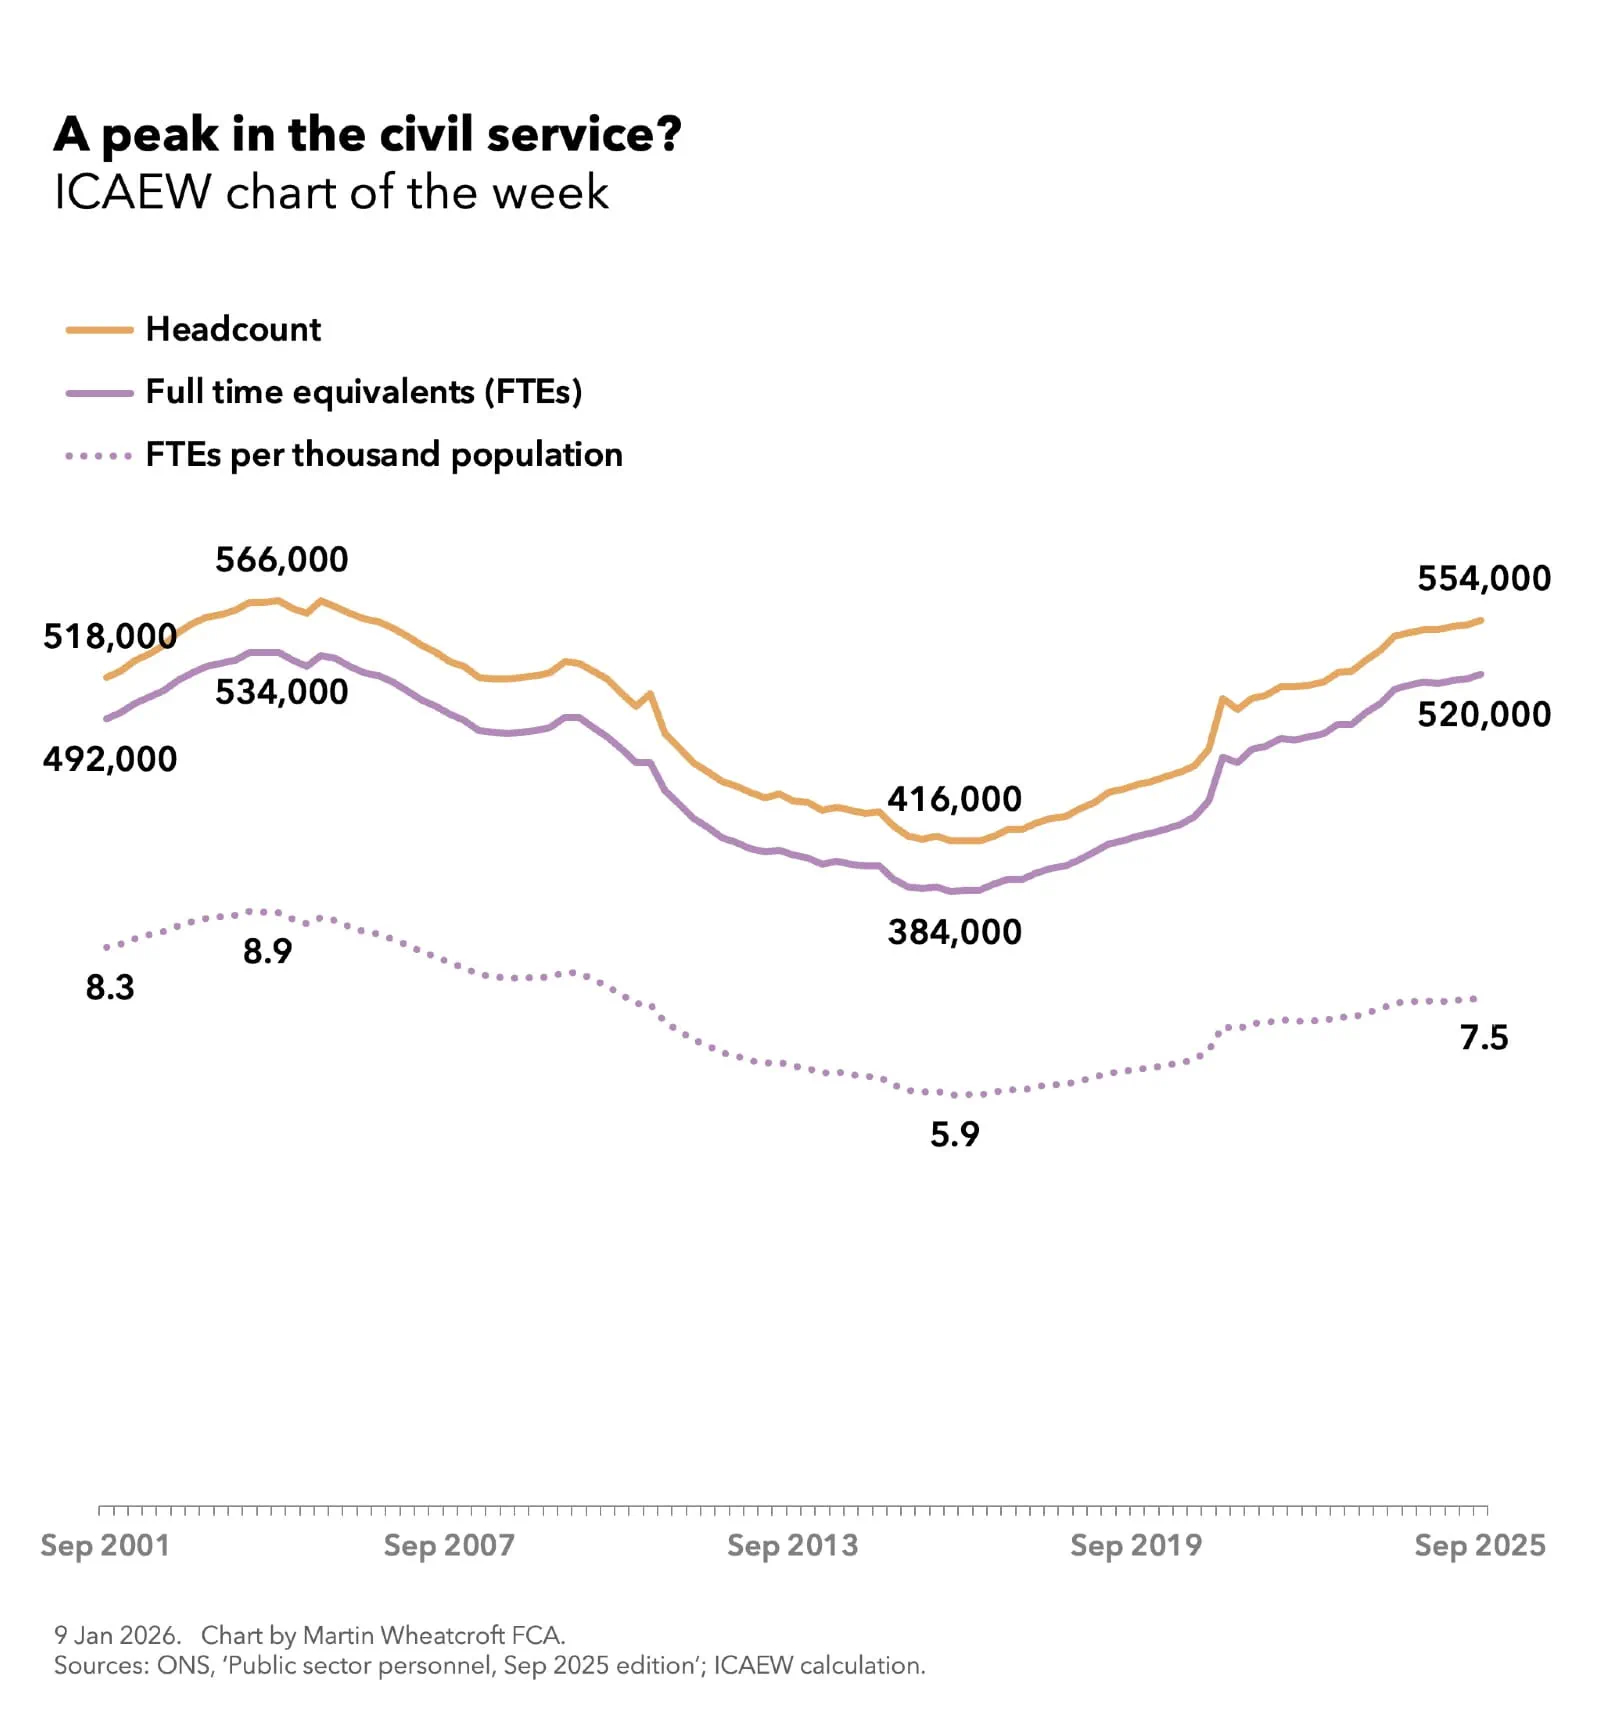
My chart for ICAEW this week takes a look at how the size of the civil service has risen, fallen, and risen again over the last 24 years.
According to the Office for National Statistics (ONS), there were 518,000 civil servants or 492,000 full time equivalents (FTEs) in September 2001. This rose to 566,000 or 534,000 FTEs in September 2004, before gradually falling over the following decade or so to 416,000 or 384,000 FTEs in June 2016. Numbers started to increase from that point, rising to 554,000 or 520,000 FTEs in September 2025.
The decline in the number of civil servants during the Cameron-led coalition government between 2010 and 2015 reflected a concerted attempt to reduce costs, but the cuts were brought to a shuddering halt following the UK’s decision to leave the European Union.
This saw civil numbers grow firstly to prepare for Brexit from the summer of 2016 onwards and then following the reverse economies of scale from the UK’s departure from the EU in January 2020 and from the EU single market and customs union in December 2020. Functions including trade relationships, customs, farm subsidies, regional economic development and multiple strands of regulation (economic, financial, food, medical, chemical etc) have all returned from Brussels, requiring more civil servants to deal with each. Although Covid boosted numbers further in 2020 and 2021, the rise has continued steadily since then as government departments have become even busier due to a range of factors, including rising numbers of immigrants and asylum seekers.
Our chart also shows how the ratio of civil servant FTEs to the population increased from 8.3 per thousand people in September 2001 to 8.9 in September 2004 and then fell to 5.9 in June 2016 before rising back to 7.5 per thousand in September 2025. This makes the increase since 2016 look a little less dramatic, as high levels of net inward migration has driven up the size of the population in recent years.
The civil service is the core policy and administrative staff working for central government departments and agencies (including those of the Scottish and Welsh governments) and is a subset of the 6.2m people (5.2m FTEs) who worked in the public sector in September 2025. This excludes the 2.3m employees (2.0m FTEs) of the NHS and other public health and social work services, the 1.7m people (1.2m FTEs) working in education, the 0.4m (0.4m FTEs) in the armed forces and police, and 1.3m (1.0m FTEs) total for council workers, employees of public corporations (such as the Post Office), and other public or crown servants.
The UK government set out a plan in the Spending Review 2025 covering the three financial years from 1 April 2026 to 31 March 2029 to cut administration budgets by 16% in real terms, with cuts in the numbers of civil servants expected to contribute a significant proportion of these savings.
The National Audit Office estimates that around 8,500 civil servants are expected to leave the civil service by March 2027 under existing exit schemes, but this is likely to be only a small proportion of the total that will need to leave if the government is to be successful in its objective.
The peak in the size of the civil service has been called many times before, but this analysis (cautiously) suggests that the most likely peak will fall in either September 2025, December 2025 or March 2026, after which the civil service is expected to begin shrinking.
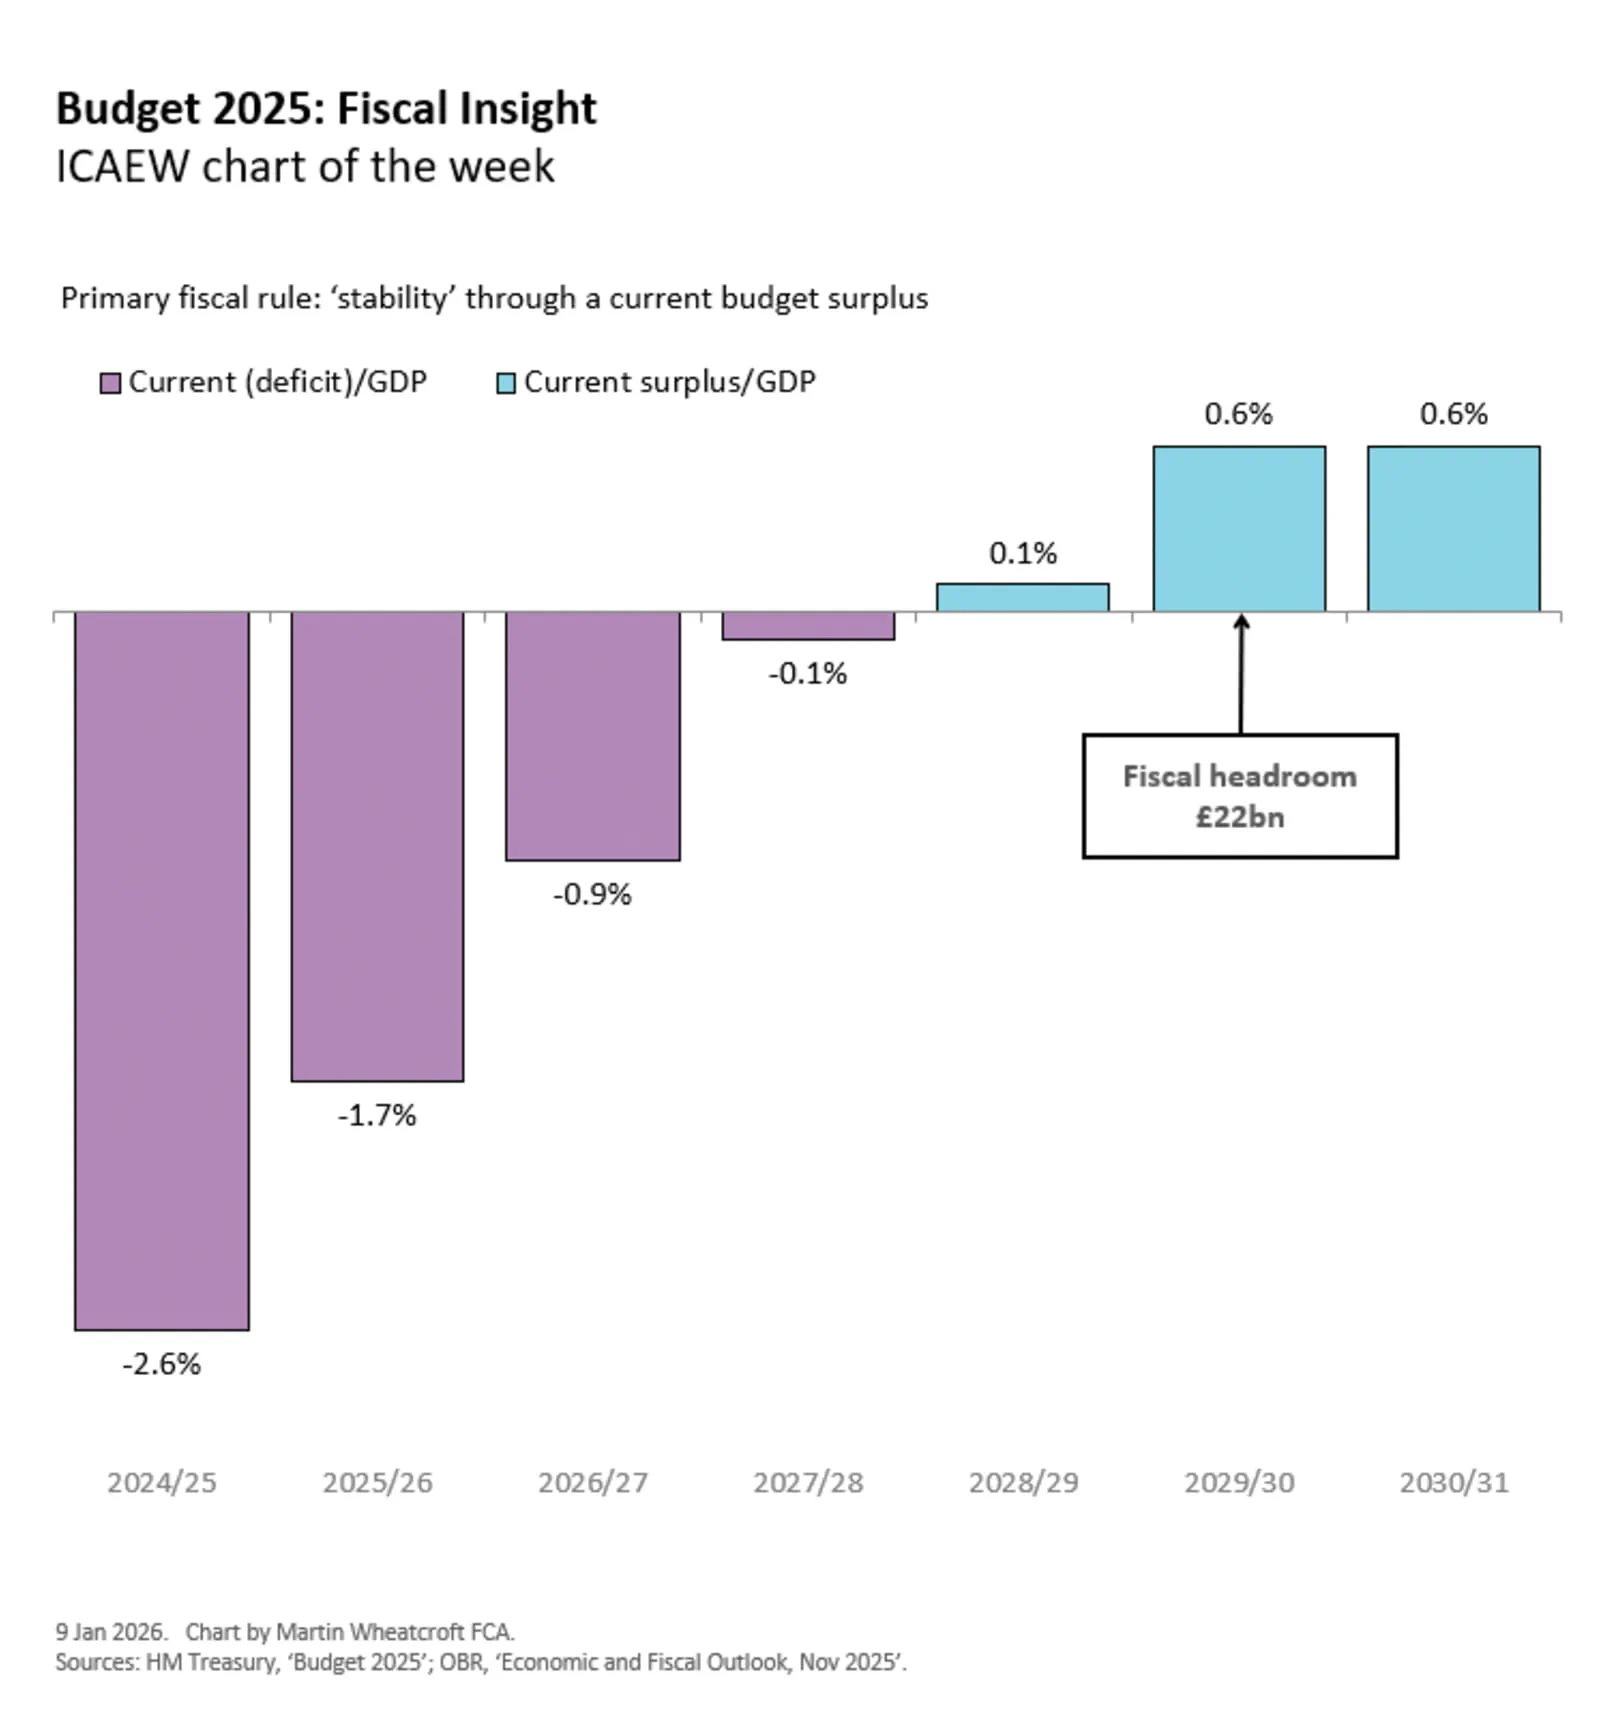
My chart for ICAEW this week returns to the scene of the Budget as it publishes an in-depth analysis written by me on its effect on the public finances and how it was ‘all about the headroom’.
Now that the dust has settled on November’s Budget, ICAEW has published a 20-page in-depth Fiscal Insight report written by me on the government’s most recent fiscal event and what it means for public finances.
One of the key conclusions of the report is that this Budget was ‘all about the headroom’, with the Chancellor’s tax rises almost entirely devoted to improving the buffer against potential adverse economic developments.
Although the government does not have an explicit long-term fiscal strategy, it does have medium-term strategic objectives to end the use of borrowing to fund current spending and to stop public debt from rising faster than the size of the economy.
These aims are embodied in fiscal targets that are intended to provide confidence to debt markets about the government’s commitment to keeping public finances under control. The Chancellor’s primary ‘stability’ fiscal rule targets a current budget surplus by 2029/30 – the fourth year of the fiscal forecast period – as illustrated by Figure 3.
In theory, this rule prevents the government borrowing to fund current spending and reduces the incentive inherent in previous fiscal rules to attempt to ‘balance the books’ by cutting investment.
Budget 2026 later this year will reduce the fiscal target to three years. This is a major improvement as it aligns with the three-year spending review period and hence should significantly reduce the scope for ‘playing with spreadsheets’ to meet fiscal targets.
The tightening in this fiscal rule is accompanied by a slight relaxation in the target: instead of aiming for a current budget surplus, the rule now allows a maximum current budget deficit of up to 0.5% of GDP. This should provide the Chancellor with around £17bn in additional headroom on top of the existing £22bn she has this year, before taking account of changes in the fiscal forecasts or policy decisions in 2026.
This is likely to mean that her secondary fiscal rule – requiring projected debt to start falling by 2029/30 – will become more important in determining whether she will meet her fiscal commitments next year.
It is generally accepted that the Chancellor left herself with too small a level of headroom against her fiscal rules in the Autumn Budget 2024. This left the government vulnerable to relatively small swings in economic circumstances and also constrained the government’s ability to spend more on defence or other emerging priorities.
The need to respond to a deterioration in the fiscal forecasts saw the Chancellor cut planned welfare spending in the Spring Statement, followed by hugely damaging speculation about potential tax rises in the run up to Budget 2025 following the overturning of those cuts by Labour MPs.
Although the level of headroom is still not that high by historical standards, the additional £17bn of headroom she is scheduled to benefit from in next year’s Budget should provide her with more resilience to weather further deteriorations in the economy if needed
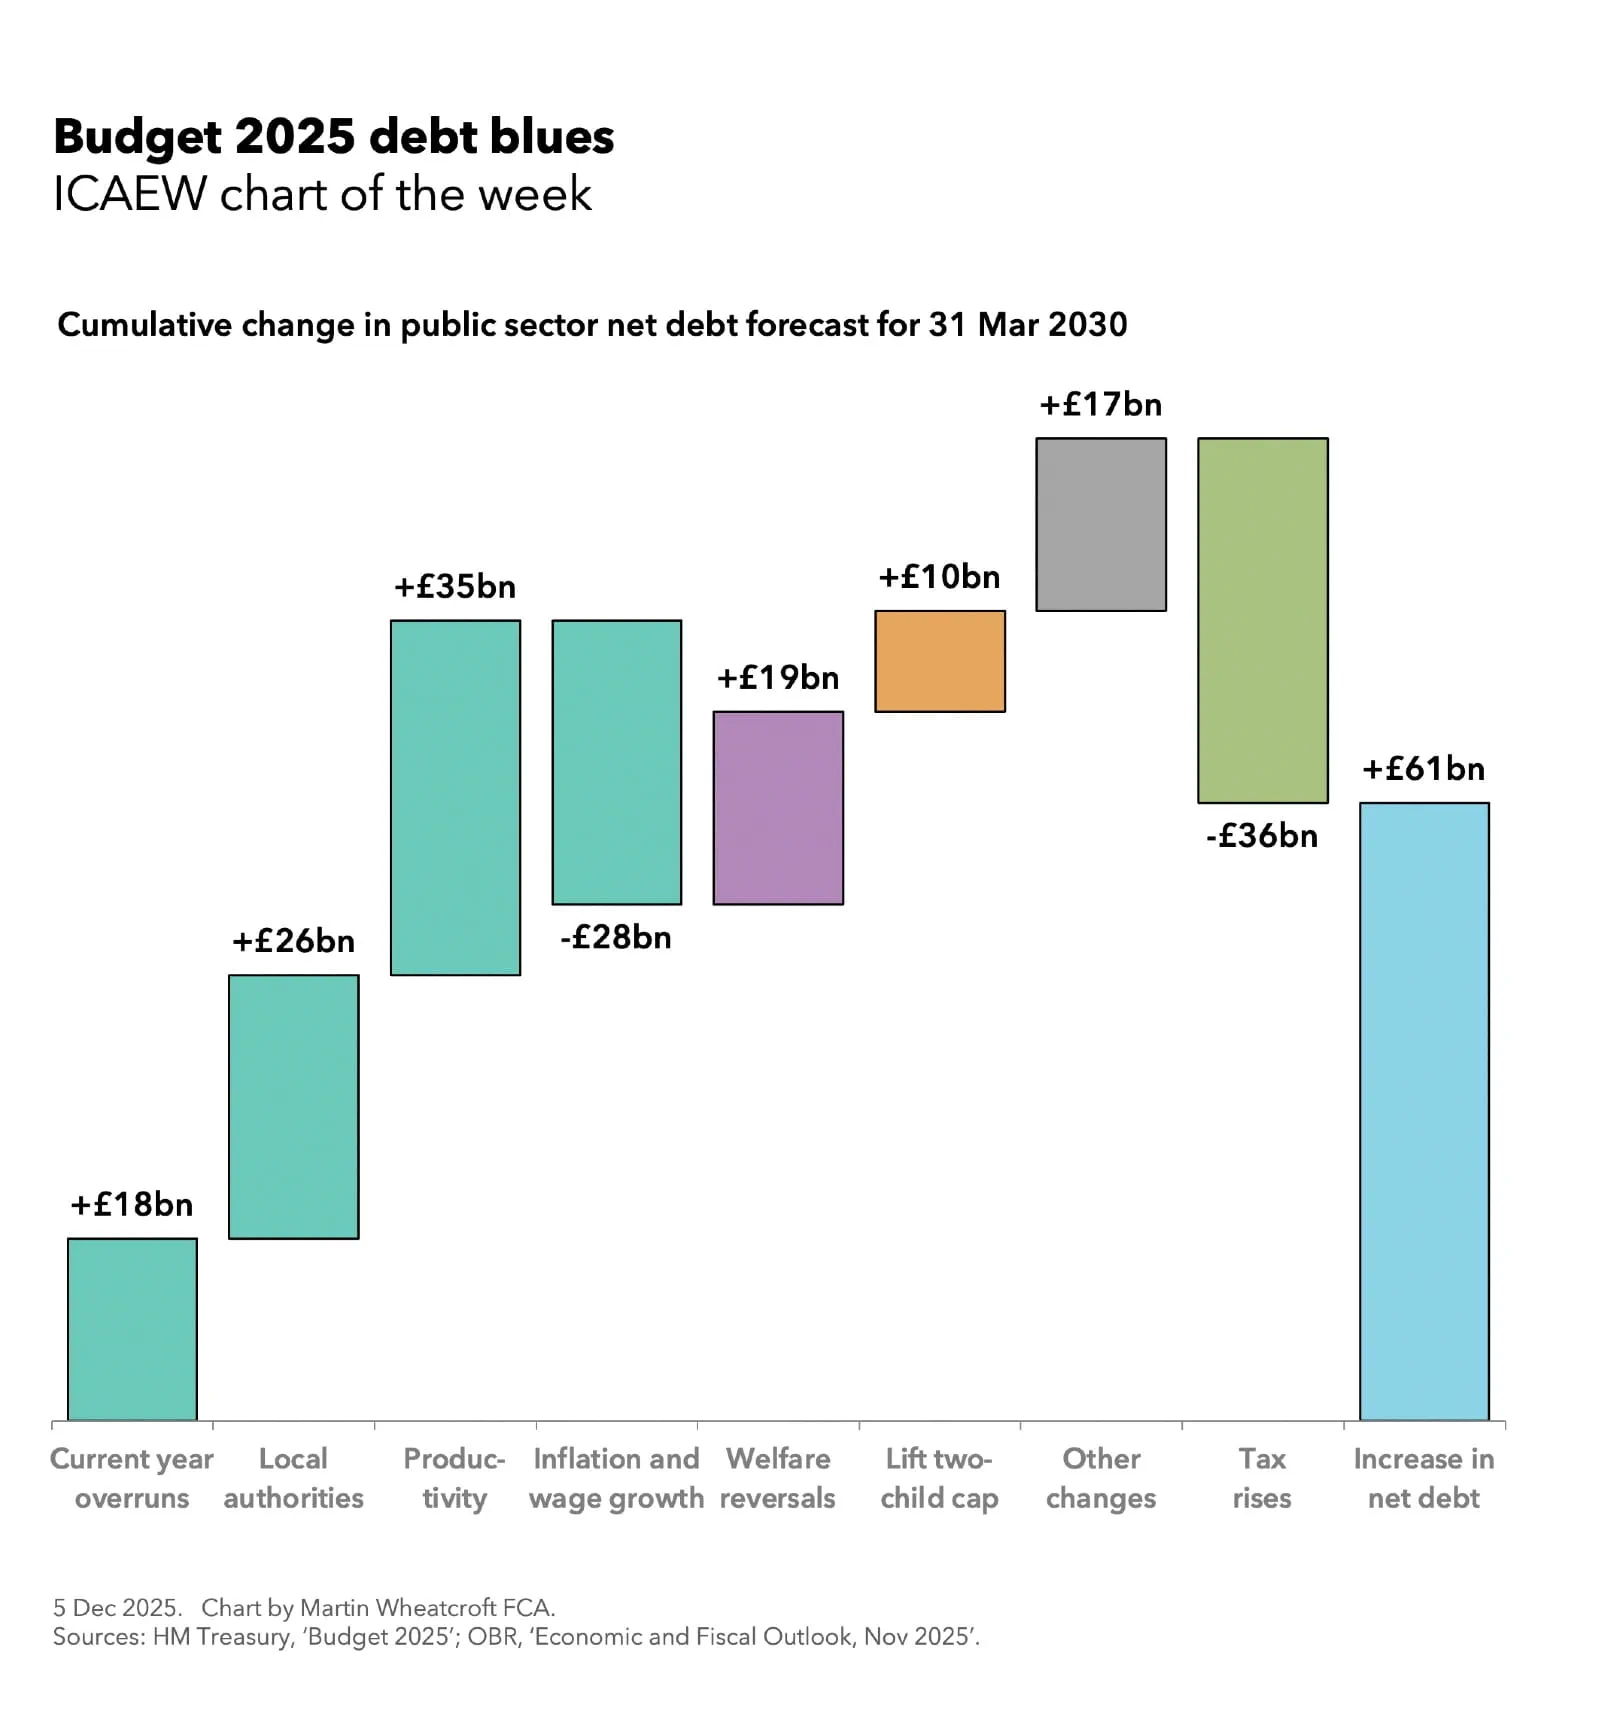
My chart for ICAEW this week illustrates how despite being a “tax-raising Budget”, the cumulative net effect of all the changes announced last week is to add £61bn to the public sector net debt forecast for 31 March 2030.
While my chart for ICAEW last week looked at the impact of Budget 2025 on 2029/30, the fourth year of the fiscal forecast used for the Chancellor’s fiscal rules, this week’s focus is on the cumulative effect of the changes made between now and 31 March 2030.
The first four bars of our step chart analyse the OBR’s forecast revisions, starting with extra borrowing to fund the expected budget overrun in the current financial year (2025/26) of £18bn (technically a £21bn higher deficit less a £3bn opening adjustment). This is followed by more borrowing to fund higher local authority spending of £26bn over four years (an average of £6.5bn a year) and to cover cumulative lower receipts of £35bn from downgrading the productivity growth assumption (£2bn a year rising to £16bn by 2029/30). This is then offset by £28bn over four years from the impact of inflation and wage growth on receipts exceeding the impact of inflation and other cost pressures on public spending.
Borrowing over the next four years is then increased by £19bn (just under £5bn a year on average) to cover the government’s welfare reversals over the summer – the restoration of the winter fuel allowance to many pensioners and the decision not to proceed with eligibility restrictions for disability benefits that were needed to make the Spring Statement add up.
The decision to lift the two-child benefit cap adds another £10bn (£2.5bn a year on average) to projected debt over the next four years, while other policy measures and working capital movements are expected to add £17bn (£11bn and £6bn respectively) on top of that.
A £36bn net reduction in debt from higher tax receipts net of indirect effects over the next four years (zero in 2026/27, £4bn in 2027/28, £10bn in 2028/29, and £22bn in 2029/30) reduces the cumulative impact to £61bn, with the £3,391bn forecast for 31 March 2030 at the time of the Spring Statement back in March 2025 being revised up to £3,452bn in the Autumn Budget 2025.
Perhaps the most surprising aspect of this analysis is the £26bn revision to the forecast for local government spending. While not as large as the well-publicised impact of productivity downgrades on the OBR’s fiscal forecast, it highlights some fundamental bookkeeping issues in how the government manages the public finances. A monthly financial consolidation process that excludes local government, schools and many other public bodies means the Office for National Statistics (ONS) and HM Treasury rely on forecasts and estimates instead of actual data when reporting the monthly public sector finances, exacerbated by the use of the four different accounting frameworks across the public sector and the local audit crisis in England that has created a large backlog in local authority audited financial statements.
The OBR states: “Recent substantial revisions to LA borrowing estimates and outturns, which reflect ongoing challenges in obtaining timely and high-quality estimates particularly for expenditure by local authorities. The ONS, the Ministry of Housing, Communities and Local Government, the Treasury and the OBR have formed a joint Local Government Financial Information Taskforce to investigate and address these concerns, with the overall objective of improving the flow of data to the ONS and the accuracy of our forecast.”
Meanwhile, the backloading of tax rises means that although the forecast is for a current budget surplus in 2029/30 and for a reduced overall deficit in that year, the summer welfare reversals, lifting of the two-child benefit cap, and other policy changes all require more borrowing before the tax rises kick in.
The 2025 Budget provides very mixed messages about the UK public finances’ prospects. There is more borrowing over the next three years before tax rises fully kick-in, while at the same time there are significant risks that mean the government could be back here again next year or the year after to ask for more money.
If ever a Chancellor could really do with some good economic news, it is probably in the coming year.
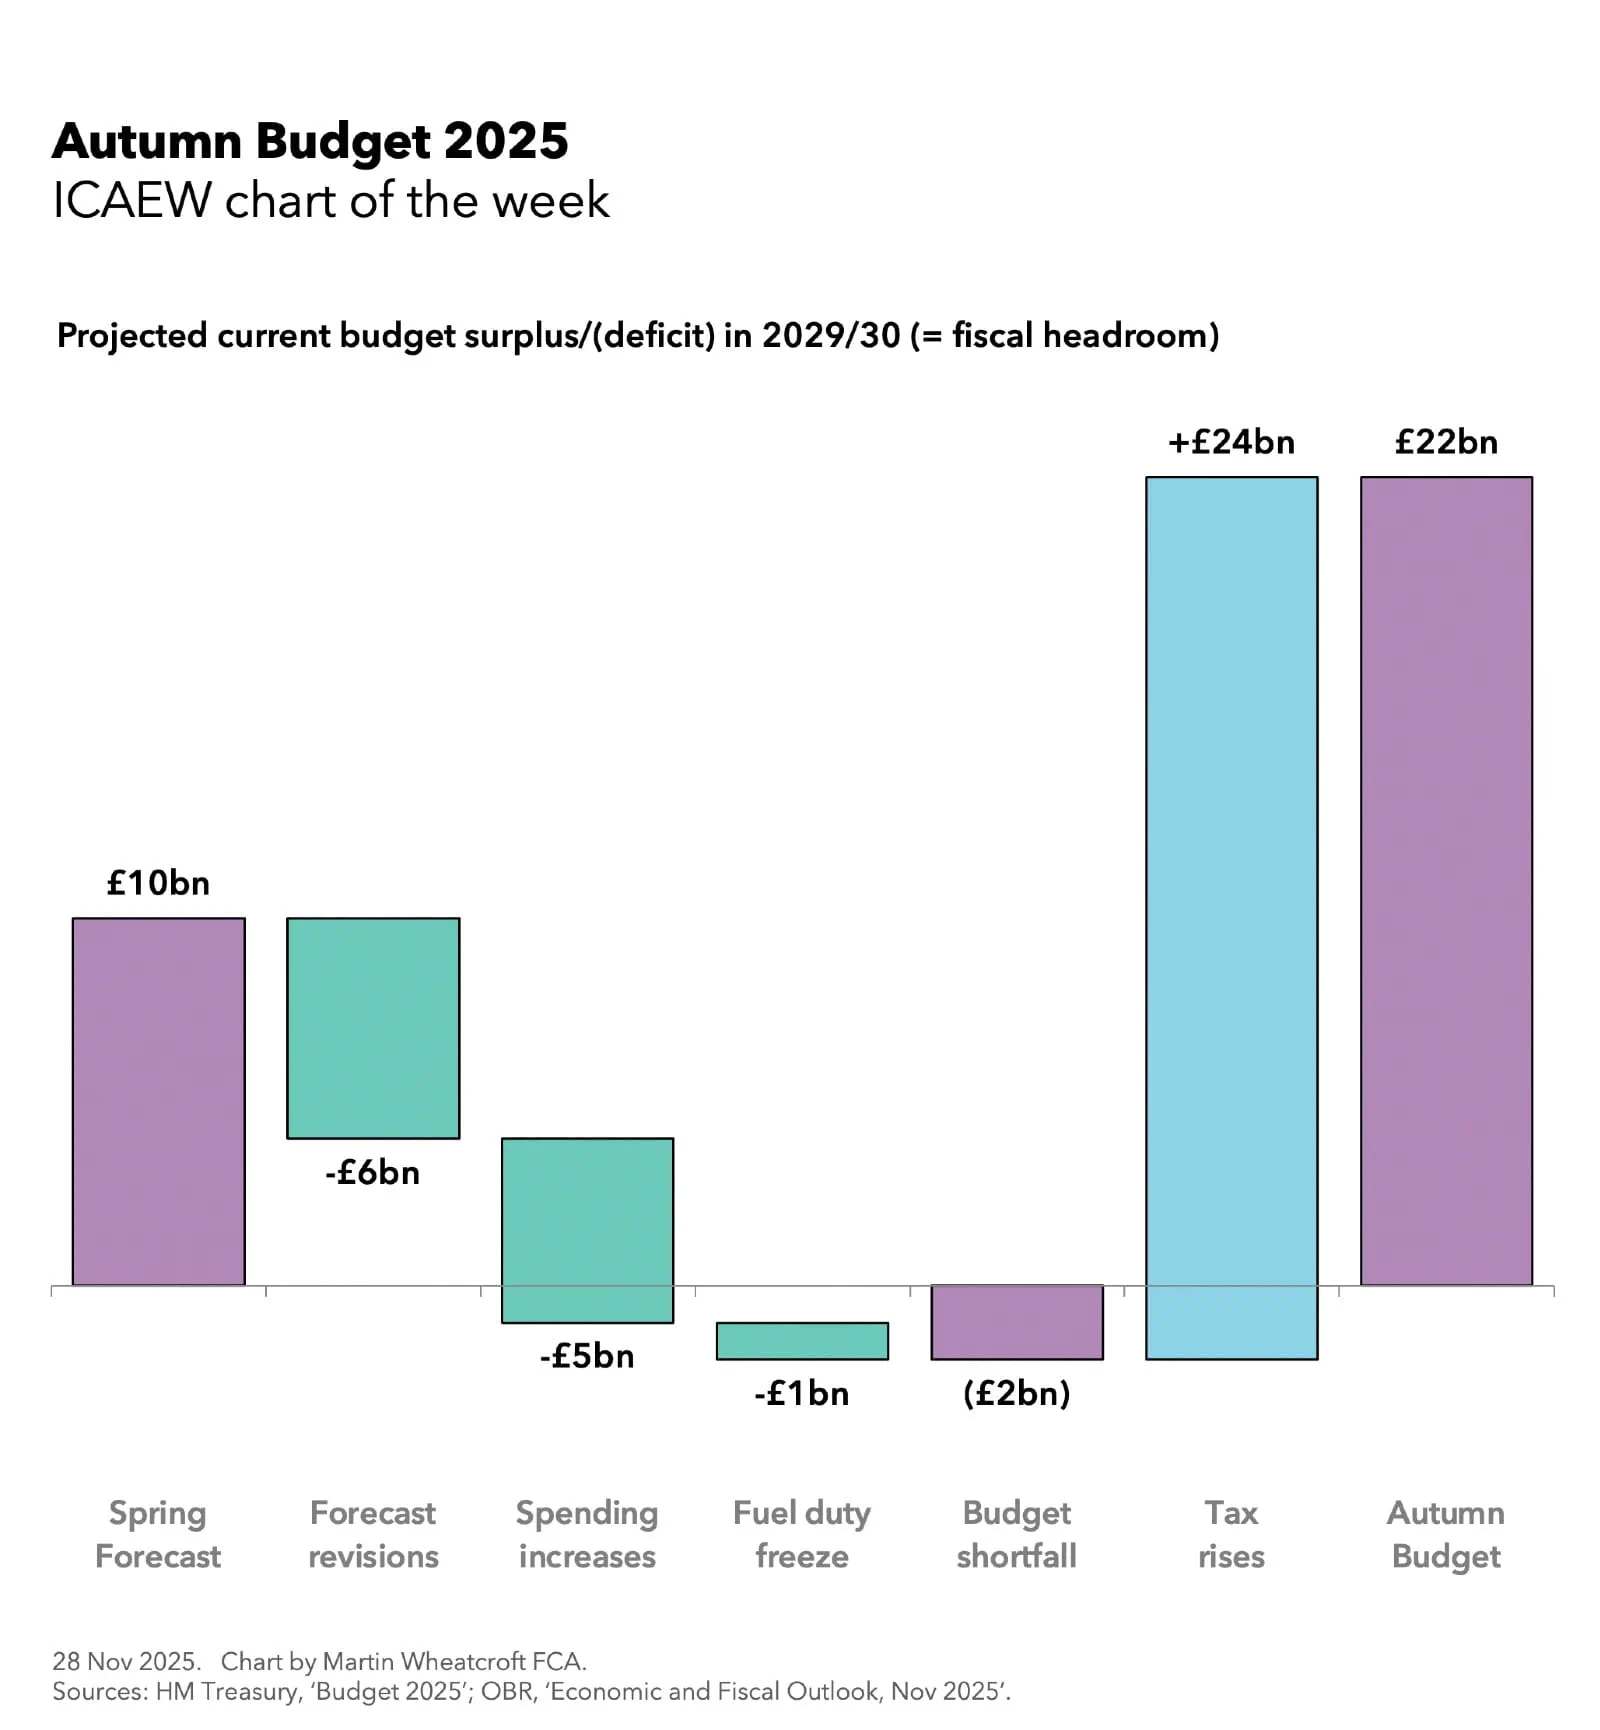
My chart this week for ICAEW looks at how the Chancellor used tax rises to refill and increase her budget headroom after forecast revisions and spending increases eliminated the projected current budget surplus for 2029/30.
The chart shows how the projected current budget surplus of £10bn in 2029/30 was reduced by £6bn of Office for Budget Responsibility (OBR) forecast revisions, by £5bn of spending increases announced in the Autumn Budget, and by £1bn from the freezing of fuel duties for yet another year.
Together these reduced the Chancellor’s headroom against her primary fiscal rule (to be in a current budget surplus by the fourth year of the fiscal forecast) from £10bn to minus £2bn – in effect breaching her fiscal rule before taking account of tax rises.
The Chancellor has then restored – and increased – her fiscal headroom to £22bn through a long list of tax rises that are anticipated to generate £24bn more in receipts in 2029/30.
Forecast revisions
The rumoured forecast downgrade from the OBR of £6bn in 2029/30 turned out to be much less significant than expected.
The OBR cut its receipts forecast for 2029/30 by £16bn a year because of weaker assumed productivity growth. But this was more than offset by a £30bn increase from higher nominal wages and prices, driven by both inflation and real wage growth, to add £14bn to receipts in that year – an increase not a decrease to the receipts side of the forecast.
This was offset by £20bn in higher current spending, of which £6bn was from higher uprating of welfare benefits and growth in claimants and caseloads, £6bn from government policy reversals on the winter fuel allowance and disability benefits, £4bn in higher debt interest, £2bn in higher local government spending, and £2bn in other changes.
The resulting deterioration of £6bn in the projected current budget surplus for 2029/30 was £14bn smaller than the £22bn deterioration anticipated by the Institute for Fiscal Studies (IFS) in its pre-Budget forecast (as used in our chart of the week on the Autumn Budget hole). The principal driver was £22bn in incremental receipts from higher inflation and higher real wage growth less £6bn in higher spending for similar reasons.
Because departmental budgets for 2026/27, 2027/28 and 2028/29 set out in the Spending Review earlier this year have not been increased for this higher level of inflation, the risk is that future Budgets will need to top up the amounts allocated to departments to deal with cost pressures that are likely to arise.
Spending increases
Current spending is projected to increase by £5bn in 2029/30, comprising £3bn to cover the annual cost of abolishing the two-child benefit cap, £1bn in higher debt interest, and £1bn in net other changes in non-interest current spending.
The OBR also announced that it had reduced its underspend assumption for departmental budgets during the latest spending review period (2026/27 to 2028/29 for current spending) by an average of £4bn a year to reflect the increased pressures on budgets from higher inflation. There was no similar adjustment to 2029/30 current spending as it is not covered by the spending review, but there is a risk that a similar adjustment may be needed by the time of the 2027 spending review.
Fuel duty freeze
Freezing fuel duties has become a consistent feature of Budgets since 2011, with the effect of reducing annual tax receipts in real terms by just under £1bn a year.
Given the current Chancellor has chosen to continue this practice in two successive Budgets, it is disappointing that fiscal forecasts have not reflected the anticipated £3bn additional reduction in tax receipts in 2029/30 if fuel duty is frozen again in the next three Budgets.
Tax rises
The Chancellor announced a total of £27bn in tax rises in the Budget (£26bn if the fuel duty freeze effective tax cut is netted off), but this is expected to generate £24bn in incremental tax receipts once behavioural responses and other indirect economic effects are adjusted for.
These tax rises are expected to generate the following amounts per year by 2029/30:
£8bn from extending the freezing of personal allowances (more ‘fiscal drag’).
£5bn from restricting the use of salary-sacrifice schemes to make pension contributions.
£2bn from increased income tax rates on property, savings and dividends.
£1.5bn from changes to writing-down allowances.
Just under £1.5bn from a mileage-based charge on electric cars.
Just over £1bn from gambling duty reform.
Just under £1bn from capital gains tax on employee ownership trusts.
Just under £0.5bn from a high value council tax surcharge.
Around £4.5bn from other tax measures.
£2bn from improved tax compliance and collection.
Higher headroom
The Chancellor chose to increase headroom against her principal (current budget) fiscal rule from £10bn last year to £22bn and to increase headroom in her secondary (debt) fiscal rule from £15bn to £24bn.
These are both positive in that they provide a much bigger cushion against potential forecast downgrades in the spring or autumn next year, reducing the risk of another round of significant tax rises in the Chancellor’s third Budget in 2026. It also helps that she is likely to gain around £15bn of extra headroom as the main fiscal rule moves to being tested in the third year of the forecast, which comes with a margin of permitted current budget deficit up to a maximum of GDP.
However, significant downside risks remain, so this outcome is far from assured. The Chancellor still faces the challenge of reviving a weak economy and delivering substantial efficiency savings if she is to keep public spending under control in the absence of more fundamental reform. That task is made harder by the risk of bailouts for local authorities and universities, and by continued pressure on the welfare budget.
The cumulative budget overrun has widened from £7bn to £10bn in seven months, reveals latest data from the Office for National Statistics.
The monthly public sector finances release, published by the Office for National Statistics (ONS) on 21 November 2025, reported a provisional shortfall between receipts and public spending of £17bn in October and a cumulative deficit of £117bn for the seven months then ended.
Martin Wheatcroft, external adviser on public finances to ICAEW, says: “The monthly public finances continue to disappoint, with the cumulative budget overrun widening from £7bn in the last release to £10bn for the seven months to October.
“While only slightly worse than expected, there were no rays of sunshine in these numbers for a beleaguered Chancellor trying to navigate her way through a series of political, economic and fiscal minefields surrounding the Autumn Budget.”
There was a £17bn shortfall between provisional receipts of £96bn and total public spending of £113bn in October 2025. This was £2bn better than the £19bn deficit incurred in October last year (£89bn receipts less £108bn total spending), but £3bn more than the budget of £14bn for the month.
Current spending of £108bn and net investment of £5bn in October were both in line with the £108bn and £5bn monthly averages incurred respectively during the first six months of the financial year.
October’s semi-annual advance tax payments meant that public sector net debt fell by £12bn during the month (from £2,917bn on 30 September to £2,905bn on 31 October 2025), with a net inflow of £29bn from working capital movements and lending activities more than offsetting the £17bn absorbed by the deficit.
The provisional £117bn deficit for the seven months to October 2025 was £9bn or 8% more than in the same seven months last year, and £10bn more than the £107bn that was budgeted. The £10bn overrun can be analysed as a £15bn adverse variance on the current budget deficit, offset by a £5bn underspend on net investment.
Table 1 highlights how year-to-date receipts of £672bn were 7% higher than the same period last year, with income tax up 8% from a combination of inflation and fiscal drag from frozen tax allowances. National insurance was up 19% as a result of the increase in employer national insurance from April 2025 onwards, and VAT receipts were up 4%, broadly in line with consumer price inflation.
Compared to last year, the 8% increase in spending to £756bn in the first seven months to October 2025 has principally been driven by public sector pay rises, higher supplier costs, the uprating of welfare benefits and higher debt interest.
Debt interest of £88bn was £9bn higher than for the first seven months of 2024/25, comprising a £7bn increase in indexation on inflation-linked debt as inflation rose again in 2025 and a £2bn increase in interest on variable and fixed-interest debt. The latter reflects a higher level of debt compared with a year ago, offset by a lower Bank of England base rate.
Net investment of £33bn in the first seven months of 2025/26 was £2bn or 6% higher than the same period last year. This comprised capital expenditure of £55bn (up by £2bn or 4%) and capital transfers (capital grants, research and development funding and student loan write-offs) of £20bn (up £2bn or 11%), less depreciation of £42bn (up by £2bn or 5%).
The deficit is budgeted to be £118bn for the full year ending 31 March 2026, comprising £107bn in the first seven months of the year to October 2025 and £11bn in the remaining five months.
The latter comprises budgeted deficits of £9bn and £11bn in November and December 2025, a forecast surplus of £23bn in January, and deficits of £1bn and £13bn in February and March 2026.
Table 2 summarises how the government borrowed £95bn in the first seven months of the financial year to take public sector net debt to a provisional £2,905bn on 31 October 2025. This comprised £117bn in public sector net borrowing (PSNB) to fund the deficit, less a £22bn net inflow from working capital movements and government lending.
The table also illustrates how the debt to GDP ratio increased by 1.0 percentage points from 93.5% of GDP at the start of the financial year to 94.5% on 31 October 2025. Incremental borrowing of £95bn, equivalent to 3.2% of GDP, was partly offset by 2.2 percentage points from the ‘inflating away’ effect of inflation and economic growth on GDP, the denominator in the net debt to GDP ratio.
Table 2: Public sector net debt and net debt/GDP
7 months to Oct
2025/26 £bn
2024/25 £bn
PSNB
117
108
Other borrowing
(22)
10
Net change
95
98
Opening net debt
2,810
2,686
Closing net debt
2,905
2,784
PSNB/GDP
4.0%
3.8%
Other/GDP
(0.8%)
(0.4%)
Inflating away
(2.2%)
(3.1%)
Net change
1.0%
0.3%
Opening net debt/GDP
93.5%
94.4%
Closing net debt/GDP
94.5%
94.7%
Public sector net debt on 31 October 2025 of £2,905bn comprised gross debt of £3,352bn, less cash and other liquid financial assets of £447bn.
Public sector net financial liabilities were £2,583bn, which included public sector net debt plus other financial liabilities of £715bn, less illiquid financial assets of £1,037bn. Public sector negative net worth was £926bn, comprising net financial liabilities less non-financial assets of £1,657bn.
Caution is needed with respect to the numbers published by the ONS, which are repeatedly revised as estimates are refined and gaps in the underlying data are filled. This includes local government, where the numbers are only updated in arrears and are based on budget or high-level estimates in the absence of monthly data collection.
This month was no different, with the ONS revising previously reported numbers for six months to September 2025 and for previous financial years. However, on this occasion, the changes made did not affect the aggregate totals when rounded to the nearest billion pounds.
Regular updates to economic statistics resulted in an upward revision to nominal GDP and a consequential 0.2 percentage point reduction in the ratio of public sector net debt to GDP from 95.3% to 95.1% as of 30 September 2025.