ICAEW chart of the week: International trade

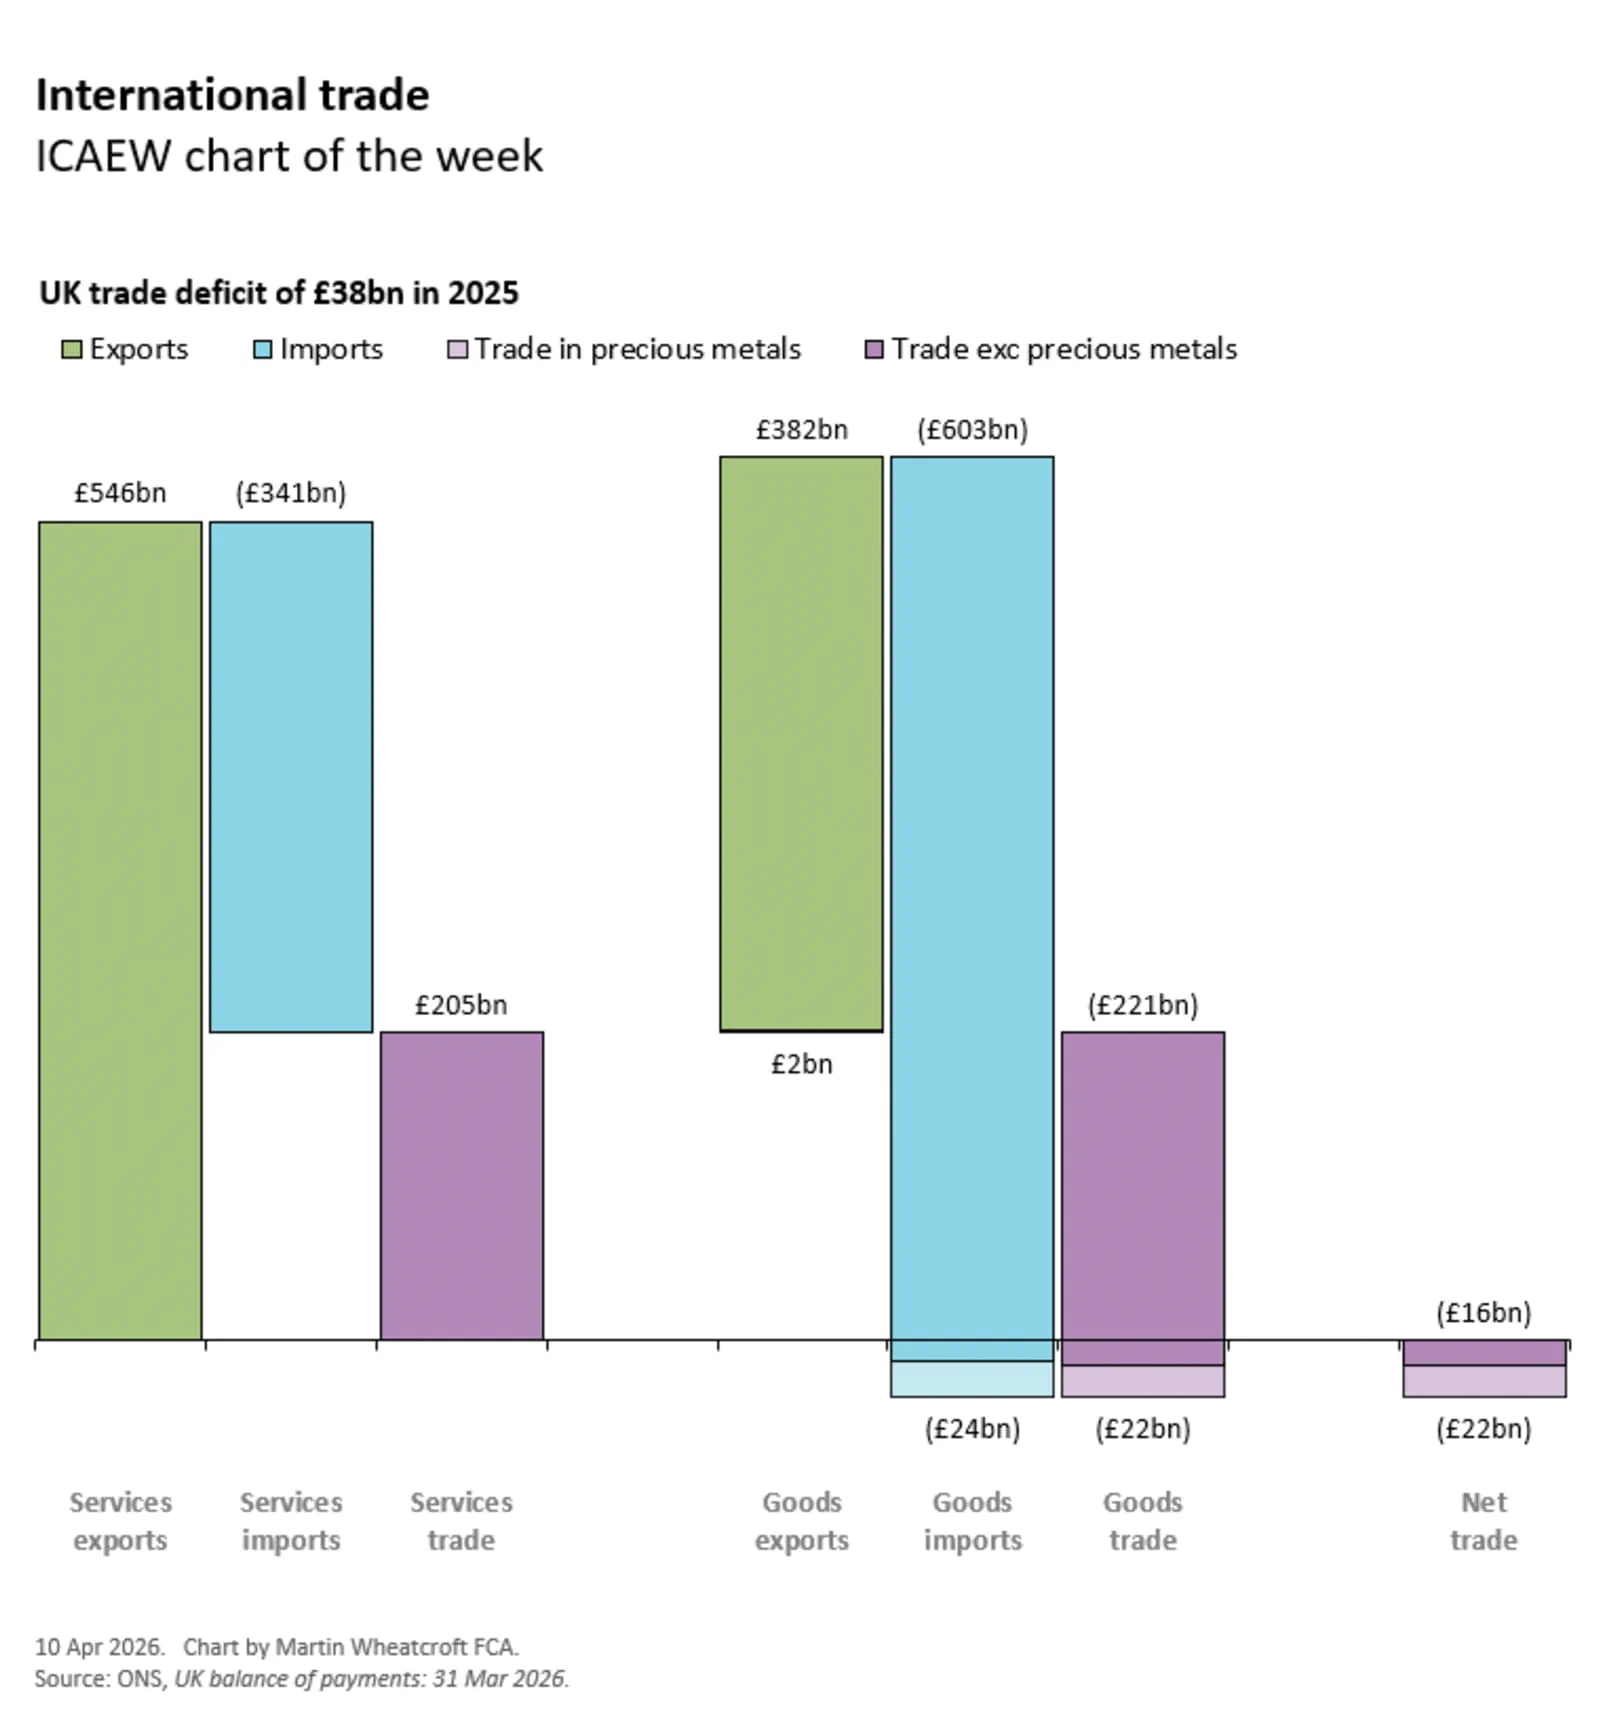
This week’s chart for ICAEW illustrates how a £205bn surplus on trade in services was offset by a £243bn deficit on trade in goods to result in a net trade deficit of £38bn in 2025 – or £16bn if trade in precious metals is excluded.
ICAEW chart of the week: International trade. 

A three-section step chart showing the components of the UK trade deficit of £38bn in 2025. 

First section (on the left): Services exports in green £546bn - services imports in blue (£341bn) = a surplus in services trade in purple of £205bn. 

Second section: Goods exports in green £382bn - goods imports in blue (£603bn) = a deficit on trade excluding precious metals in purple of £221bn; combined with precious metals exports in light green of £2bn - imports in light blue of £24bn = a deficit on trade in precious metals in light purple of £22bn. 

Third section (on the right): Net trade deficits going below the line of £16bn on trade excluding precious metals in purple and £22bn on trade in precious metals in light purple - a total of £38bn. 

10 Apr 2026. Chart by Martin Wheatcroft FCA. 
Source: ONS, UK balance of payments: 31 Mar 2026.

My chart this week for ICAEW is on the principal components of the UK’s £38bn trade deficit in the 2025 calendar year.

The chart starts with a £205bn surplus on trade in services (comprising a £546bn cash inflow from services exports less a £346bn cash outflow to pay for services imports) followed by a £221bn deficit on trade in goods excluding precious metals (comprising £382bn generated from goods exports less £603bn to pay for goods imports), and a £22bn deficit on trade in precious metals (comprising £2bn from exports less £24bn on imports).

Together these result in an overall trade deficit of £38bn, of which £16bn is a deficit on trade in goods and services excluding precious metals and £22bn relates to precious metals.

This is equivalent to a net trade deficit of 1.3% of GDP, comprising a surplus on trade in services of 6.7% of GDP (17.9% from exports – 11.2% on imports) less a deficit on trade in goods excluding precious metals of 7.3% of GDP (12.6% from exports – 19.9% on imports) and a deficit on trade in precious metals of 0.7% of GDP (0.1% from exports – 0.8% on imports).

The ONS publishes trade statistics that exclude precious metals because a large proportion of the value of this trade are sales and purchases of gold between UK and international holders that are really financial flows, often without any physical movement of the gold concerned. Not only can the volume and value of such transactions be quite volatile, but the trade deficit excluding precious metals of £16bn in 2025 is probably more representative of trade flows in that year than the overall trade deficit of £38bn.

The balance of payments 

Not shown in the chart are the other components of the current account deficit of £74bn in 2025 and a capital account deficit of £5bn.

The former comprised a primary income or ‘earnings’ deficit of £19bn (being £417bn investment income coming to the UK and £2bn foreign compensation of UK-based employees less £435bn investment income going abroad and £3bn compensation of foreign employees) and a secondary income deficit or ‘net transfers’ of £17bn (£1bn UK government receipts £1bn and £30bn remittances and other inward transfers less £12bn UK government payments abroad and £36bn remittances and other outward transfers) in addition to the trade deficit of £38bn. The latter consisted of £2bn from international sales of non-produced non-financial assets less £7bn in purchases.

The chart also doesn’t show the £79bn surplus in 2025 on the other side of the balance of payments, being an £86bn surplus on financial transactions (£678bn in financial investments in the UK less £592bn in outbound financial investments) less £7bn in statistical errors and omissions.

The trade deficit over time

The trade deficits excluding precious metals of £17bn in 2024 and £16bn in 2025 were a little lower than the £24bn average over the last quarter of a century and were less than the net £19bn average over the previous four years that were distorted by the pandemic and the energy crisis (trade surpluses excluding precious metals of £14bn and £7bn in 2020 and 2021 followed by deficits of £50bn and £47bn in 2022 and 2023).

Whether you think the trade deficit is good or bad depends on your perspective, with some worried about the net cash outflows that result from payments for imports exceeding receipts from exports. Others points to the net positive inflows of goods and services that are coming into the UK in exchange for the money that we spend. 

Either way, what we sell abroad and what we buy from overseas are important not only to UK businesses that trade internationally but also to all of us living in the UK.
This chart was originally published by ICAEW.

ICAEW chart of the week: Balance of payments

Our chart this week takes a look at the UK’s balance of payments in the year to 31 March 2025 and wonders what the future has in store.

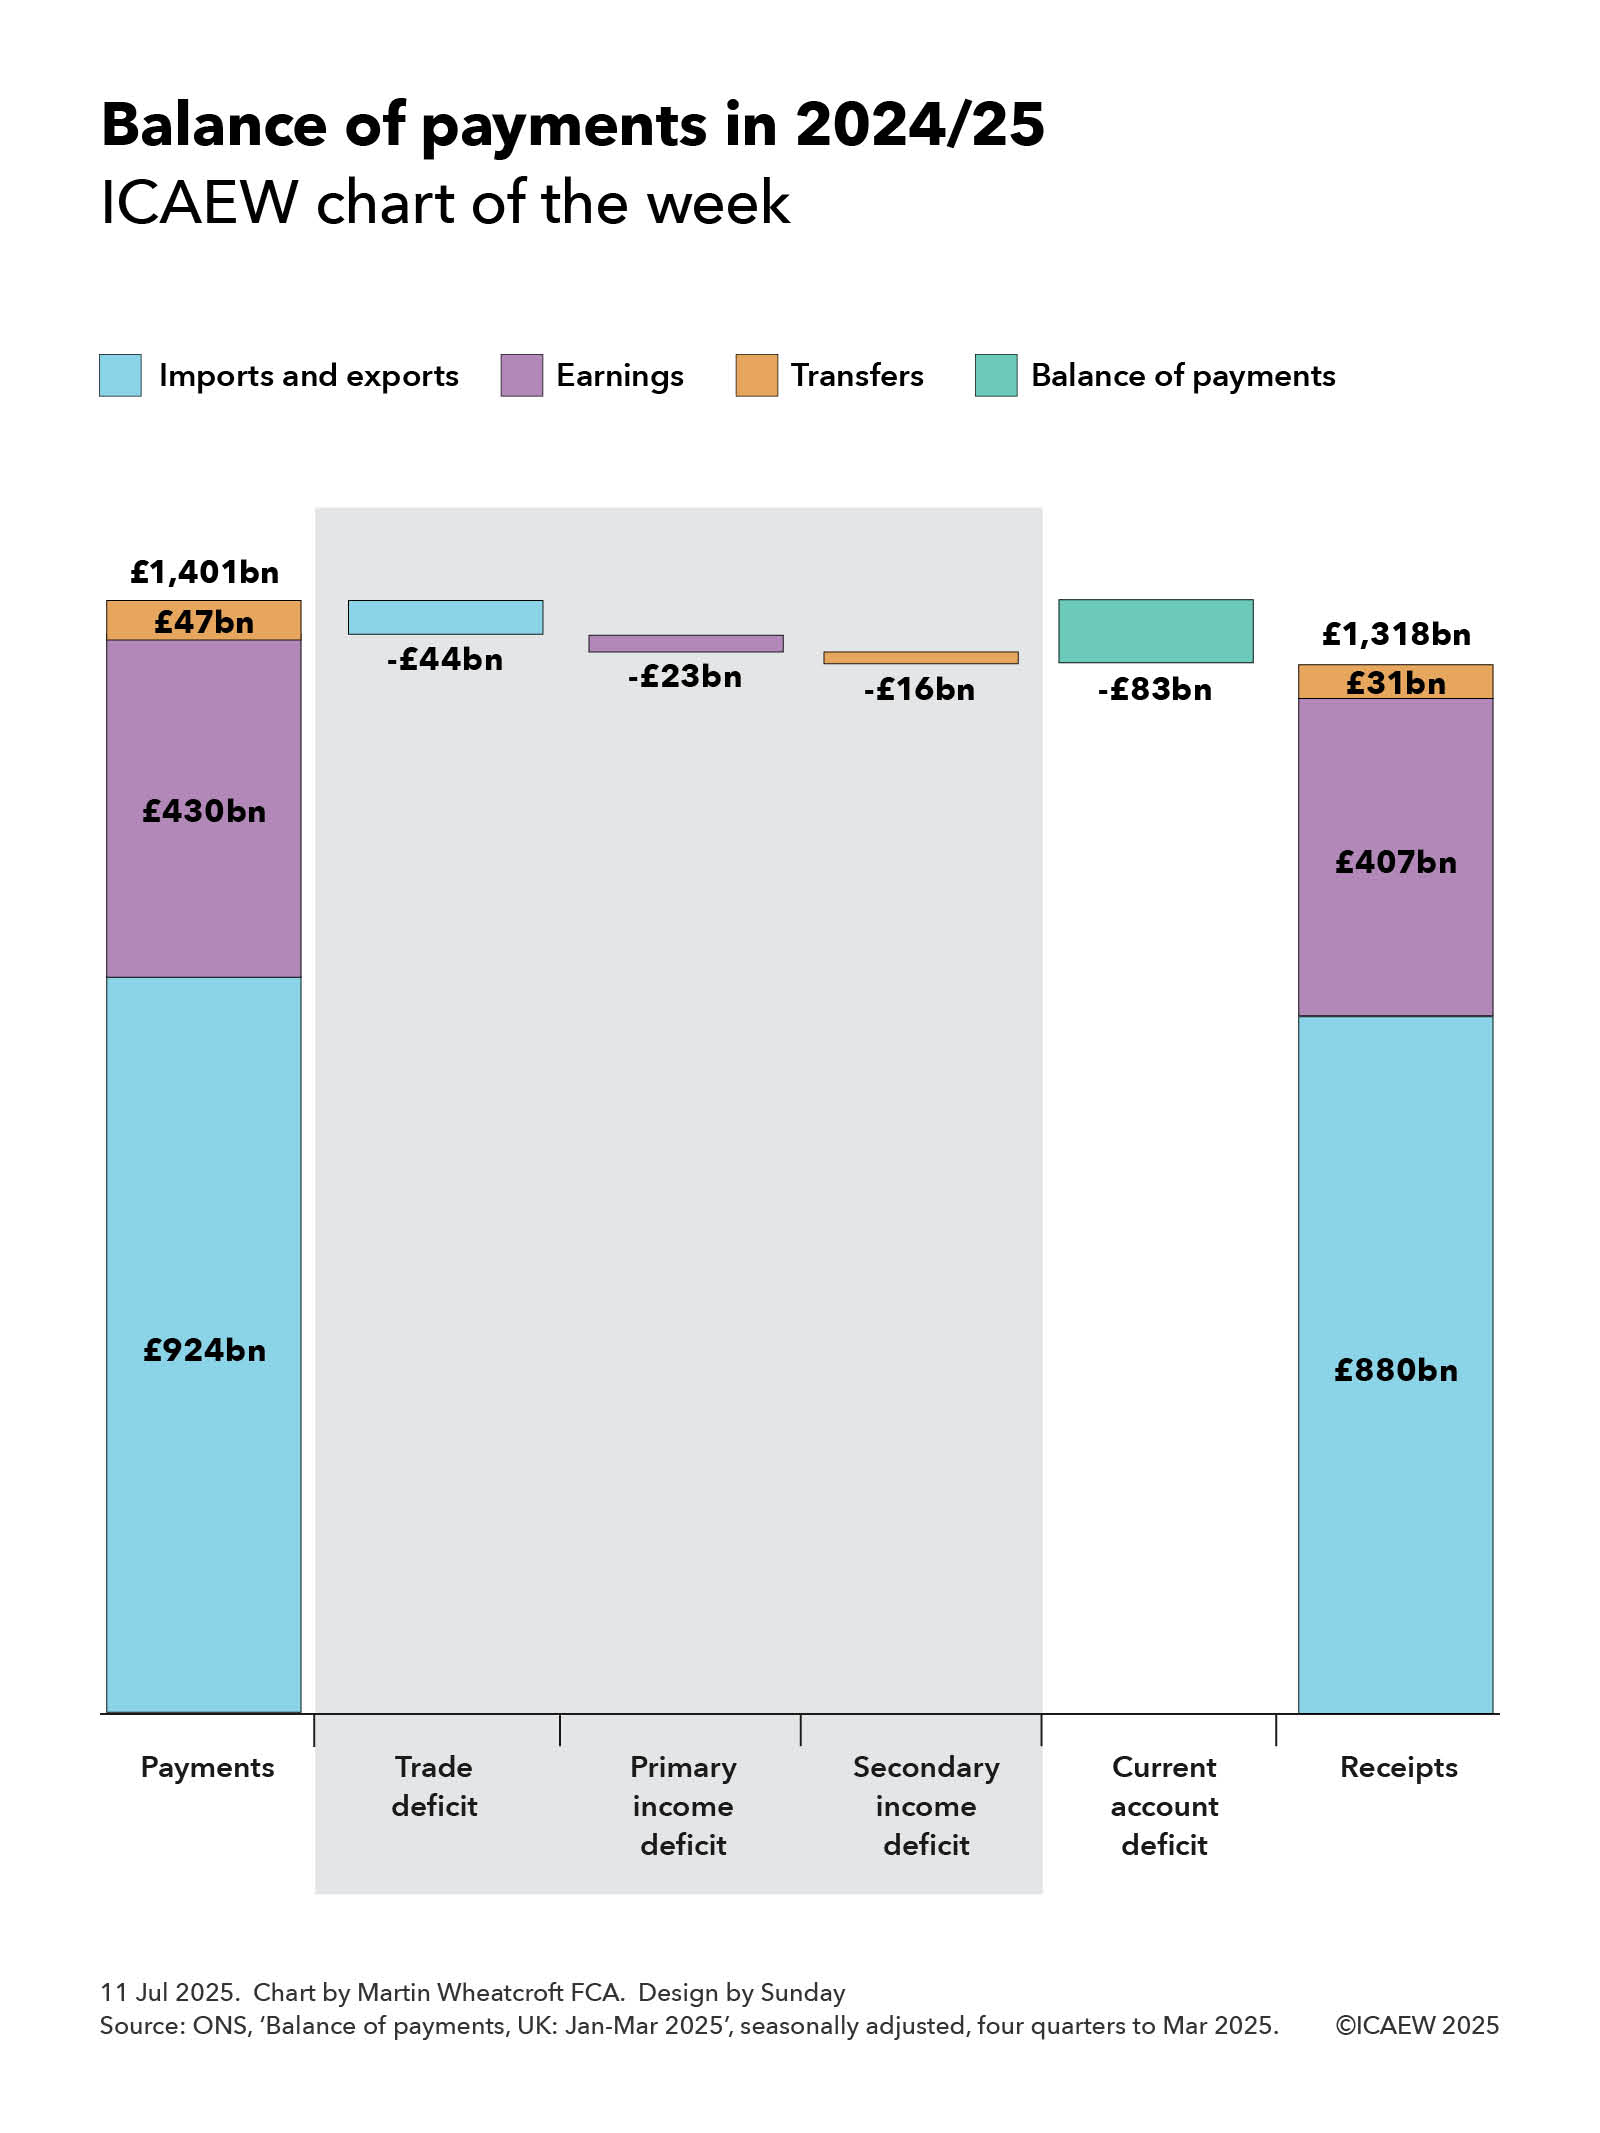
A step chart on the balance of payments in 2024/25 showing payments and receipts on either side, with three shaded sub-steps in-between adding up to the current account deficit, being the difference between total payments and receipts. 

Payments £1,401bn = £924bn for imports + £430bn earnings + £47bn transfers.  

Receipts £1,318bn = £880bn from exports + £407bn earnings + £31bn transfers.  

Step 1: Trade deficit (imports and exports) -£44bn. 
Step 2: Primary income deficit (earnings) -£23bn. 
Step 3: Secondary income deficit (transfers) -£16bn. 

Step 4: Current account deficit (sum of steps 1 to 3) -£83bn.   

11 Jul 2025. Chart by Martin Wheatcroft FCA. Design by Sunday. Source: ONS, 'Balance of payments, UK: Jan-Mar 2025', seasonally adjusted, four quarters to Mar 2025.

The UK is a trading nation as demonstrated by its balance of payments, the topic of our chart this week.

According to the Office for National Statistics (ONS), the UK made external payments of £1,401bn in 2024/25, comprising £924bn in exchange for imported goods and services, £430bn in investment and other earnings paid to foreign investors and workers, and £47bn in remittances, international development aid and other transfers.

On the other side of the ledger, the UK received £1,318bn from external sources in 2024/25 comprising £880bn in exchange for exported goods and services, £407bn from foreign investment and other earnings, and £31bn in remittances and other transfers.

As our chart illustrates, this resulted in a current account deficit of £83bn in 2024/25, comprising a trade deficit of £44bn, a primary income deficit on earnings of £23bn, and a secondary income deficit on transfers of £16bn.

The trade deficit of £44bn can be analysed between a deficit on goods of £239bn (being payments for goods imports of £602bn net of receipts from goods exports of £363bn) and a surplus on services of £195bn (with payments for services imports of £322bn being exceeded by receipts from services exports of £517bn).

The primary income deficit of £23bn principally relates to the £22bn difference between £427bn in investment income and profits generated in the UK paid to foreign owners in 2024/25 and the £407bn received by UK investors from their investments overseas, plus £1bn from the net of £3bn paid in compensation to foreign workers less £2bn earnt by UK workers from foreign sources.

The secondary income deficit of £16bn comprises a net £10bn in government-related transfers, being £11bn in payments made by the UK government (primarily for international development and humanitarian aid) less £1bn received from the EU and others, and a net £6bn from the differences between remittances and other transfers sent abroad of £36bn less remittances and other transfers received into the UK of £30bn.

The chart does not show the other side of the balance of payments, which is a £77bn non-seasonally adjusted surplus on the investment account less a £4bn deficit on the seasonally adjusted capital account, a net cash inflow of approximately £73bn. 

The £77bn surplus on the investment account reflected net investment into the UK of £370bn over the course of the four quarters to March 2025, less £293bn net investment abroad. The £4bn deficit on the capital account primarily relates to international development capital grants, with £1bn from the disposal of non-financial assets to foreign owners offset by £1bn in UK purchases of foreign non-financial assets.

While some of the difference of £10bn between the current account deficit of £83bn and the net surplus on the investment and capital accounts of £73bn is because of timing differences from seasonal adjustments, most of it arises because the ONS is not able to gather data on all international payments and receipts. In theory the balance of payments should balance exactly.

The current account deficit of £83bn in 2024/25 was equivalent to 2.9% of the UK’s GDP of £2,891bn for the same period, being the net of total payments and total receipts of 48.5% and 46.6% of GDP respectively.

Being the difference between two very big numbers, the current account deficit is the net effect of billions of transactions every year as goods and services are bought and sold internationally, earnings are paid and received, and money is transferred at exchange rates that change on a minute-by-minute basis. Despite this the current account deficit in 2024/25 was only 0.1 percentage points higher than the average 2.8% of GDP since 1997, even if it has gone as high as 6.9% in an individual quarter.

While the global trade war was initiated by the US is likely to have a major impact on how money flows around the world, it is much harder to guess how significant that effect will be, either on the overall global economy or on any individual country, in particular the UK. 

Either way, the balance of payments is likely to become a more prominent statistic in the coming months and years. 

This chart was originally published by ICAEW.

ICAEW chart of the week: US and China trade

Our chart this week looks at trade between the US and China following the 145% tariffs imposed on China by President Trump in the latest twist in his global trade war.

A three-column step chart showing the trade balance between the US and China. 

China exports to the US: $439bn goods + $462bn = $462bn total. 

China trade surplus with the US: $263bn. 

US exports to China: $144bn goods + $55bn = $199bn total. 

11 Apr 2025. Chart by Martin Wheatcroft FCA. Source: US Bureau of Economic Analysis, 'International Trade in Goods and Services'.

According to the US Bureau of Economic Analysis, mainland China generated a trade surplus of $263bn in its trade with the US in 2024, being total exports of $462bn from China to the US less imports into China from the US of $199bn.

As our chart of the week highlights, the vast majority of China’s exports to the US in 2024 were goods, with $439bn sold to US businesses and consumers, while services exports amounted to a much smaller $23bn. Meanwhile the US exported $144bn in goods and $55bn in services in the same period.

China’s overall trade surplus of $263bn can be analysed between a surplus on goods trade of $295bn less a deficit on services of $32bn.

These numbers exclude trade between Hong Kong and the US, where Hong Kong has a trade deficit with the US of $22bn, comprising exports from Hong Kong to the US of $22bn ($7bn goods and $15bn services) less imports from the US into Hong Kong of $44bn ($29bn goods and $15bn services).

Goods exports from China to the US of $439bn in 2024 included $206bn in machinery, electrical and electronic products (including $51bn phones, $36bn computers and $18bn batteries), $42bn chemicals and pharmaceuticals, $37bn clothes and accessories, $30bn toys, games and sports equipment, $25bn metals and metal products, $19bn furniture, $19bn plastics and $17bn vehicles, together with $44bn in other goods. 

Goods imported by China from the US of $144bn included $28bn in machinery, electrical and electronic products (including $9bn integrated circuits), $23bn food and drink (much of which was animal foodstuffs), $21bn chemicals and pharmaceuticals, $15bn fuel, $12bn aircraft, and $7bn metal and metal products, together with $35bn in other goods. 

While the imposition of such high tariffs on China is likely to cause US consumers and businesses to switch to other sources where they can, in many cases this will not be possible – especially in the near term. This is likely to be the case for the significant proportion of China’s exports that are intermediate goods used by US manufacturers to make their own products – many US businesses reliant on Chinese inputs could find they are no longer competitive with suppliers from elsewhere in the world that are now subject to ‘just’ 10% tariffs (or 25% in the case of cars, steel and aluminium).

So, while we can’t predict what is going to happen in the global trade war launched by President Trump, the current state of affairs of 10% base import tariffs on almost all countries and 145% tariffs on imports from China seems unlikely to last indefinitely.

This chart was originally published by ICAEW.

ICAEW chart of the week: Trade with the US

Our chart this week looks at trade with the US in light of the 10% tariffs imposed on the UK by President Trump on ‘liberation day’.

A three-column step chart showing the difference between UK exports to and imports from the US. 

UK exports to the US: £58bn goods + £124bn services = £182bn. 

UK trade surplus with the US: £71bn.   

UK imports from the US: £56bn goods + £55bn services = £111bn.  


4 Apr 2025. Chart by Martin Wheatcroft FCA. Design by Sunday. Source: DBT, 'United States Trade and Investment Factsheet, 21 Feb 2025'.

According to the UK Department for Business and Trade, the UK generated a trade surplus of £71bn during the four quarters ended 30 September 2024, being the difference between seasonally adjusted numbers for exports of £182bn from the UK to the US less imports from the US into the UK of £111bn. 

As our chart of the week highlights, goods exports to and imports from the US comprised £58bn and £56bn respectively, while services exports to and imports from the US were £124bn and £55bn.

The trade surplus with the US of £71bn for the year to September 2024 can be analysed between a surplus on goods of just under £2bn and a surplus on services of slightly more than £69bn, according to the statistics collected by the UK Office for National Statistics (ONS).

The £2bn surplus on goods in favour of the UK contrasts with the corresponding US statistics, which report a trade surplus in goods in favour of the US of $12bn (£9bn) in 2024, based on exports from the US to the UK of $80bn (£62bn) less imports from the UK into the US of $68bn (£53bn).

According to non-seasonally adjusted data from the ONS, goods exports to the US in the four quarters to September 2024 totalled £60bn (£2bn more than the £58bn shown in the chart), comprising £37bn in manufactured goods (including £8bn cars, £5bn engines and £2bn aircraft), £7bn pharmaceuticals, £5bn other chemicals, £3bn metals, £3bn food, drink and tobacco, £3bn oil, and £2bn other goods and materials.

Meanwhile non-seasonally adjusted data on goods imports from the US in the same period of £57bn (£1bn more than in the chart) comprised £25bn manufactured goods (including £6bn engines, £3bn aircraft and £1bn cars), £15bn oil and gas, £4bn pharmaceuticals, £4bn other chemicals, £2bn metals, £1bn food, drinks and tobacco, and £6bn of other goods and materials.

The US is the UK’s biggest individual trading partner, with exports to the US representing 22% of total UK exports (goods: 16% of total goods exports; services: 27% of total services exports) and imports representing 13% of total imports (goods: 10% of total goods imports; services: 19% of total services imports).

These numbers compare with the UK’s trade with the EU in the year to September 2024, where exports to the EU were £346bn or 41% of total exports (goods: £178bn or 48% of total goods exports; services: £168bn or 36% of total services exports) and imports from the EU were £445bn or 52% of total imports (goods: £312bn or 55% of total goods imports; services: £133bn or 45% of total services imports).

The UK government was no doubt relieved to have ‘only’ been targeted with 10% tariffs by President Trump. It will also be hopeful that the position of both the UK and US believing they have a small surplus in their goods trade with each other will help in the negotiations for a UK-US trade deal that could potentially see those tariffs lifted.

The government will also be hoping that the global trade war on goods doesn’t affect the UK’s services trade too much, given its importance as an export earner.

This chart was originally published by ICAEW.

ICAEW chart of the month: UK international trade

Imports £718bn: EU £369bn, EFTA £34bn, USA £87bn, Other Americas £26bn, Asia-Pacific £138bn, Other £64bn. Exports £673bn: EU £297bn, EFTA £29bn, USA £133bn, Other Americas £29bn, Asia-Pacific £108bn, Other £77bn.

With recent changes in ICAEW communications, the ICAEW Public Sector team has started an #icaewchartofthemonth to complement the #icaewchartoftheweek.

The first #icaewchartofthemonth was published on the ICAEW’s Insights Hub (icaew.com/insights) on Friday 31 January 2020 and is on the UK’s international trade. It highlights how important the £718bn in imports and £673bn in exports in the year to 30 September 2019 are to the economy of the UK.

As the UK Government starts to negotiate new trade arrangements with countries around the world, the EU will be the highest priority. Imports into the UK of £369bn represent 51% of total imports and exports to the 27 EU countries of £297bn are 44% of total exports. This is followed by the USA, where imports of £87bn and exports of £133bn represent 12% and 20% respectively.

Trade relationships with countries in the Asia-Pacific region will also be very important, in particular China (imports £60bn and exports £39bn), Japan (£17bn and £15bn) and the 10-country Association of South East Asian Nations (£22bn and £19bn).

https://www.icaew.com/insights/features/2020/jan-2020/uk-international-trade