ICAEW chart of the week: Australian Government balance sheet

My chart for ICAEW marks Australia Day by looking at the federal government balance sheet over the last decade.

My chart for ICAEW marks Australia Day by looking at the federal government balance sheet over the last decade.

Australia Day is on Monday 26 January, prompting us take a look at the Australian Government’s consolidated financial position over the last 10 years.

The chart is derived from federal government consolidated financial statements prepared in accordance with Australian Accounting Standards (as adjusted for prior period adjustments), divided by annual estimates of GDP in current prices published by the Australian Bureau of Statistics in October 2025.

The chart shows how net worth was negative throughout the period, going from 18% of GDP on 30 June 2015 to 23% on 30 June 2025.

Other key stats from the balance sheet

  • Non-financial assets going from 10% on 30 June 2015 to 11% on 30 June 2025
  • Financial assets going from 24% on 30 June 2015 to 27% on 30 June 2025
  • Interest bearing liabilities going from 28% on 30 June 2015 to 36% on 30 June 2025
  • Provisions and payables going from 24% on 30 June 2015 to 25% on 30 June 2025

Financial assets of AU$753bn on 30 June 2025 comprised of AU$570bn in financial investments, AU$174bn in receivables and accrued revenue, and AU$9bn in cash. While non-financial assets of AU$320bn comprised of AU$94bn in military equipment, AU$96bn in other plant, equipment and infrastructure, AU$79bn in land and buildings, AU$17bn in intangibles, AU$13bn in inventories, AU$13bn in heritage and cultural assets, and AU$8bn in other non-financial assets.

Interest bearing liabilities of AU$1,009bn on 30 June 2025 comprised of AU$679bn in government securities, AU$216bn in central bank and other deposit liabilities, AU$58bn in loans, AU$33bn in leases and AU$23bn in other interest-bearing liabilities. While provisions and payables of AU$696bn comprised of AU$411bn in pension liabilities, AU$103bn Australian currency in issue, AU$50bn in payables and AU$132bn in provisions.

Net worth was -AU$632bn on 30 June 2025 and GDP in the year to 30 June 2025 was AU$2,779bn. (Australian balance sheet to GDP ratios are based on GDP for the preceding 12 months, rather the UK practice of using ‘mid-year’ GDP from 6 months before to 6 months after the balance sheet date). 

Nominal GDP has increased by 70% or an average of 5.5% a year over the past decade, comprising inflation of 3.2% a year on average and average economic growth of 2.2% a year. The latter reflects average population growth of 1.5% per year and average per capita economic growth of 0.75% per year.

Not shown in the chart are revenues as a share of GDP respectively in the 10 financial years from 24% in 2015/16 to 27% in 2024/25, expenditure of 27% in 2015/16 to 29% in 2024/25, and net accounting (deficits)/surpluses as a share of GDP of (2.4%) in 2015/16 to (1.5%) to 2024/25. Net investment averaged 0.5% of GDP over the ten years.

This is of course not the full picture of the Australian public finances, as these numbers exclude approximately AU$1.7tn of positive net worth in the balance sheets of states and territory governments and local authorities across Australia.

Overall, Australia’s overall general government net debt – including states, territories and local government, but excluding illiquid financial assets, non-financial assets and non-debt liabilities – is reported to be around 32% of GDP in 2025. This compares with around 95% of GDP for the UK according to the IMF.

Apart from the pandemic years – when deficits rose and GDP fell in real terms – what is remarkable is how stable the Australian Government balance sheet has been over the last decade when compared with the size of the Australian economy. 

This has been partly down to the continued growth of Australia’s sovereign wealth funds (the Australia Future Funds) and the decision to close federal defined benefit pension schemes to new members in 2005 (non-military) and 2016 (military), slowing the growth in these liabilities. It also reflects a relatively prudent fiscal stance over the last few decades by successive governments.

For the Australian Government, this is a positive financial position to be in.
This chart was originally published by ICAEW.

ICAEW chart of the week: Whole of Government liabilities

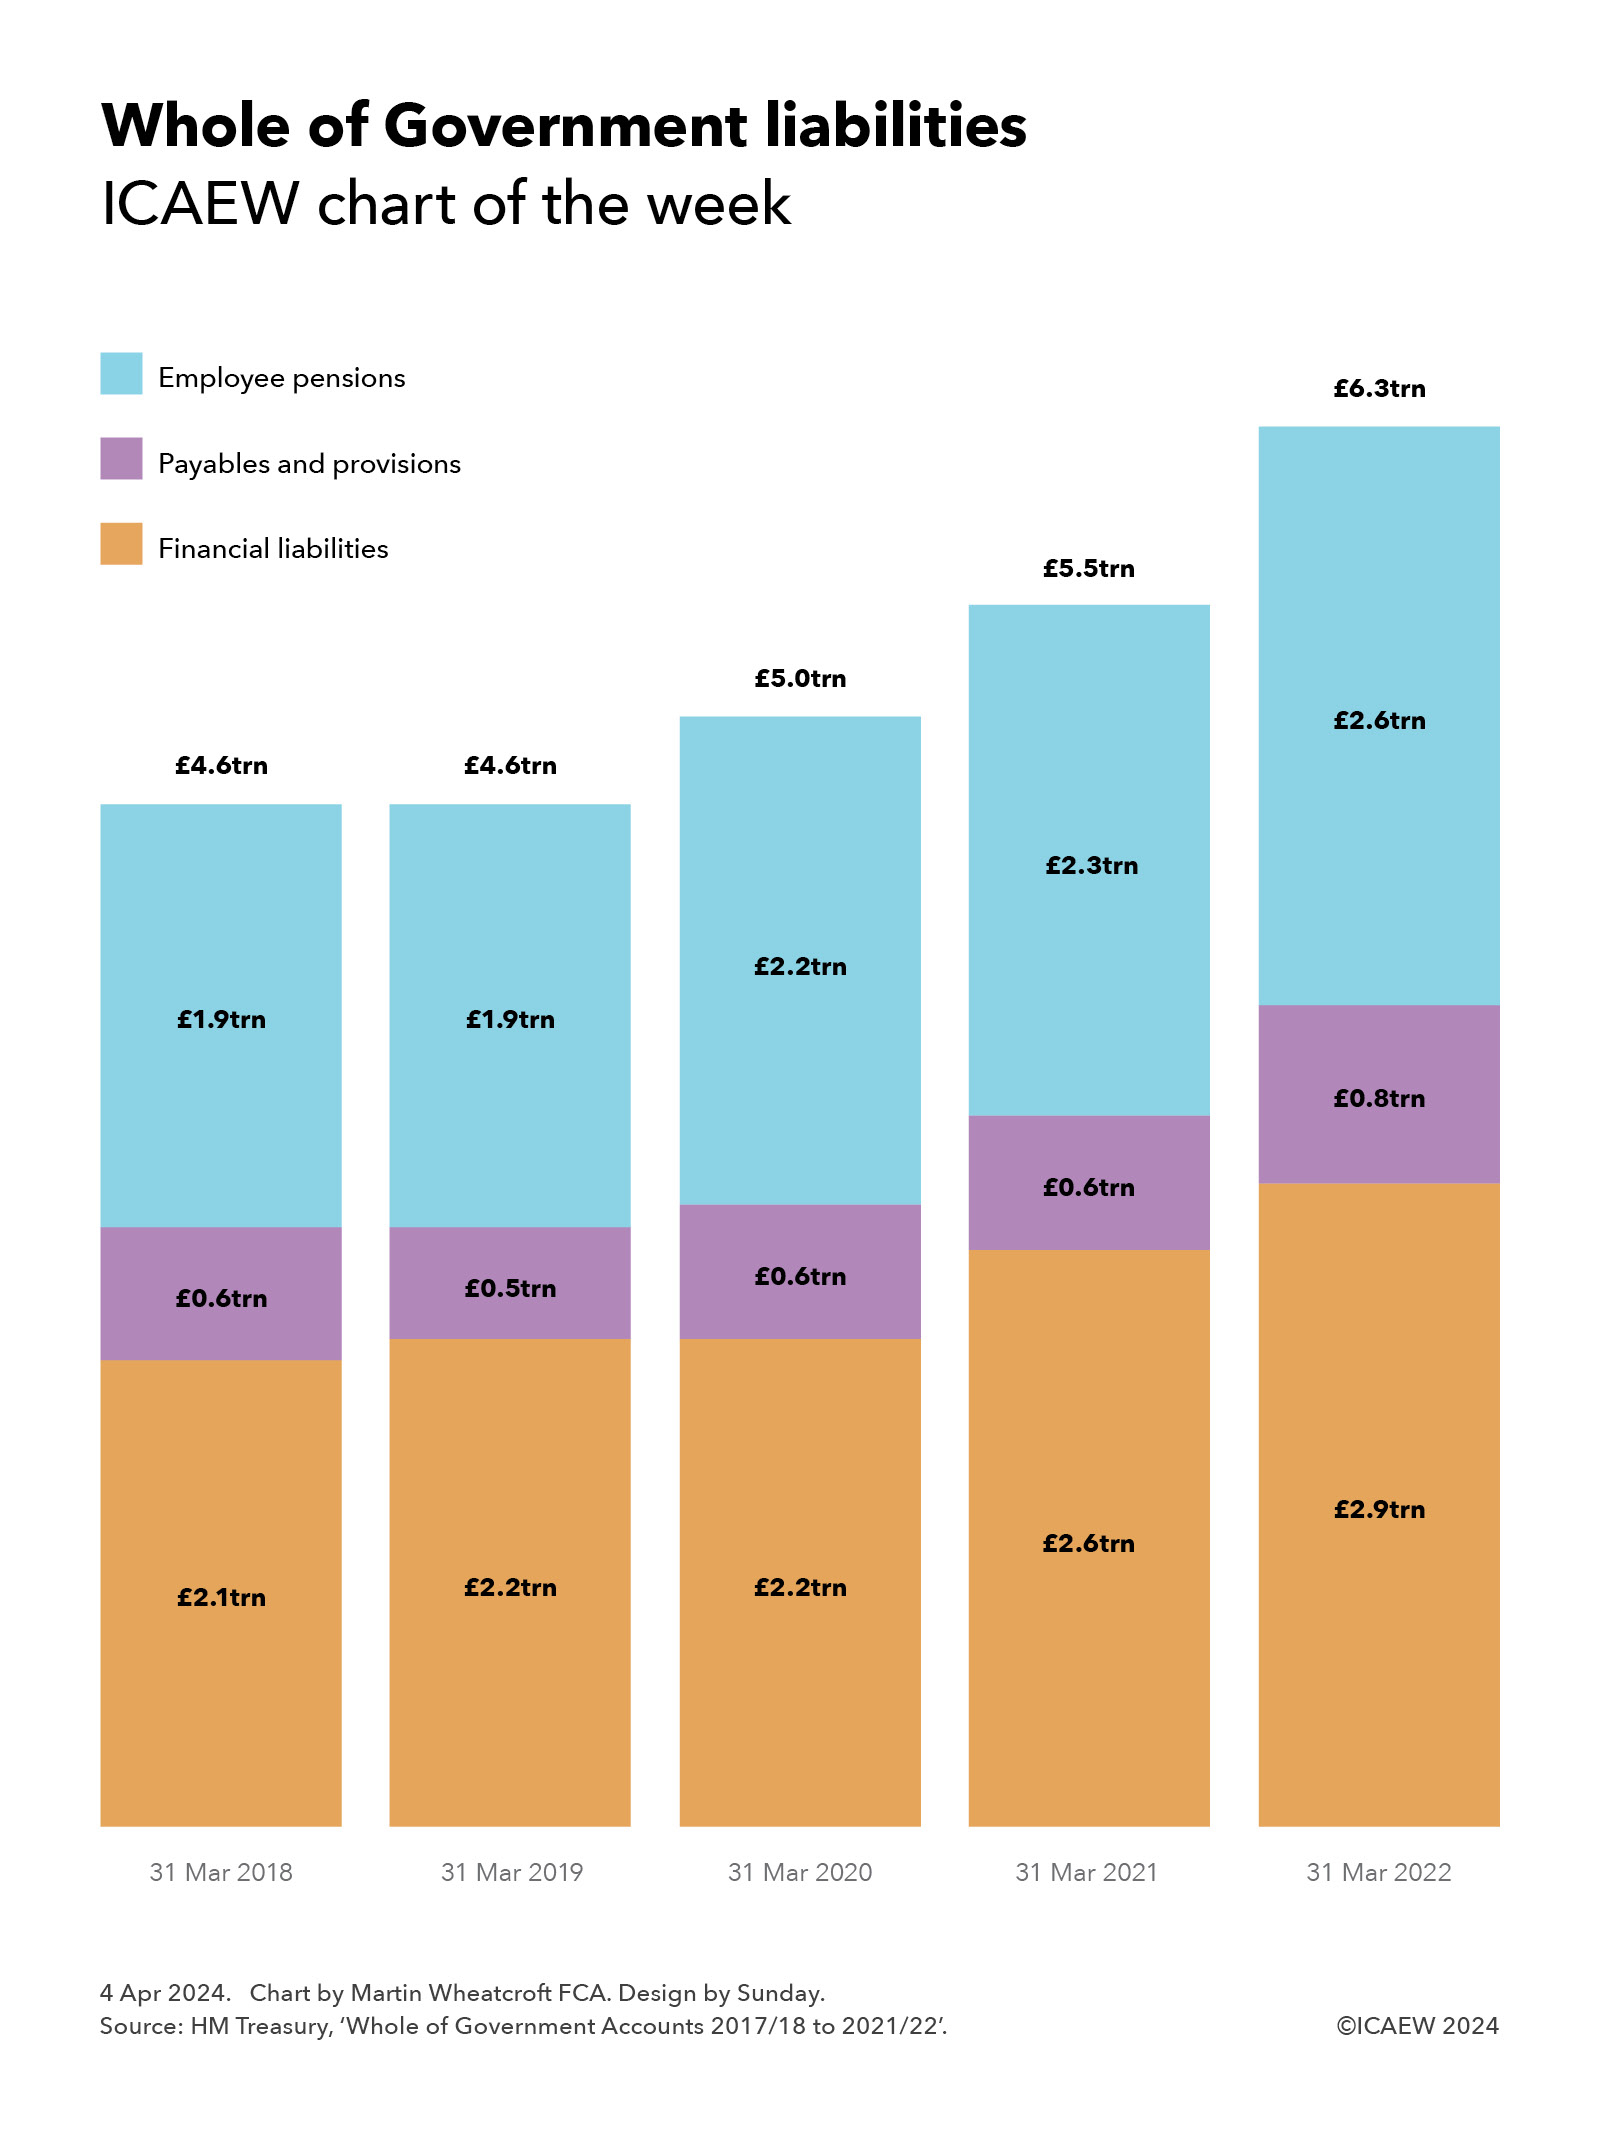
My chart for ICAEW this week looks at how liabilities in the UK’s public balance sheet have risen significantly over the five years to March 2022.

Column chart:

Whole of Government liabilities
ICAEW chart of the week

Employee pensions (blue)
Payables and provisions (purple)
Financial liabilities (orange)

31 Mar 2018: £2.1trn financial liabilities + £0.6trn payables and provisions + £1.9trn employee pensions = £4.6trn total

31 Mar 2019: £2.2trn + £0.5trn + £1.9trn = £4.6trn

31 Mar 2020: £2.2trn + £0.6trn + £2.2trn = £5.0trn

31 Mar 2021: £2.6trn + £0.6trn + £2.3trn = £5.5trn

31 Mar 2022: £2.9trn + £0.8trn + £2.6trn = £6.3trn


4 Apr 2024.
Chart by Martin Wheatcroft FCA. Design by Sunday.
Source: HM Treasury, 'Whole of Government Accounts 2017/18 to 2021/22'.

(c) ICAEW 2024.

HM Treasury published the Whole of Government Accounts (WGA) 2021/22 on 26 March 2024, just under two years after the balance sheet date. This is a significant improvement from the 27 months it took to publish the 2020/21 edition, but is still a lot longer than the nine or 10 months HM Treasury is aiming for in the medium term, or the four months or less that it generally takes listed companies to publish their consolidated financial statements.

WGA are consolidated financial statements for more than 10,000 or so organisations in the UK public sector, including central government departments, devolved administrations, regional and local authorities, the Bank of England and other public corporations, government agencies, schools, hospitals, police and fire services, transport authorities and other public bodies. They are prepared in line with international generally accepted accounting practice – International Financial Reporting Standards – different to the statistical standards used by governments to report fiscal numbers in National Accounts.

My chart for ICAEW illustrates how the liability side of the balance sheet has grown over the five-year period, from £4.6trn on 31 March 2018 and 2019 to £5trn on 31 March 2020, £5.5trn on 31 March 2021 and £6.3trn on 31 March 2022.

This reflects how debt liabilities increased from £2.1trn to £2.9trn over that time, with huge sums borrowed in 2020/21 and 2021/22 during the coronavirus pandemic. 

The other big liability in the balance sheet is the net pension obligation for public sector employees, which was £1.9trn on 31 March 2018 but had risen to £2.6trn by 31 March 2022, with falling discount rates a key factor in that rise. The latter comprises liabilities of £2.5trn for unfunded pension schemes and net liabilities of £0.1trn (£0.5trn liabilities less £0.4trn in assets) for local government and other funded pension schemes.

The balance sheet does not include the much larger commitment to pay the state pension, which as a welfare benefit is accounted for when incurred.

Total liabilities of £6.3trn on 31 March 2022 are equivalent to £93,000 per person in the UK, comprising £43,000 in financial liabilities, £11,000 in payables and provisions, and £39,000 in for public sector employee pensions.

Not shown in the chart is the asset side of the balance sheet, with assets of £2.4trn on 31 March 2022 or £36,000 per person, comprising fixed assets of £1.4trn (£20,500 per person), investments of £0.5trn (£7,000), receivables and other of £0.2trn (£3,500) and cash and other financial assets of £0.3trn (£5,000). This results in an overall net liability position of £3.9trn or £57,000 per person on 31 March 2022. 

The good news is that HM Treasury is working hard to reduce the delays in producing the WGA, which means it shouldn’t be too long before we discover what is in the 31 March 2023 balance sheet. This is expected to show an improvement, as although the government has continued to borrow, pushing up financial liabilities, the net present value of pension obligations and provisions should fall significantly as discount rates have risen sharply since March 2022.

This chart was originally published by ICAEW.

ICAEW chart of the week: Whole of Government Accounts 2019/20

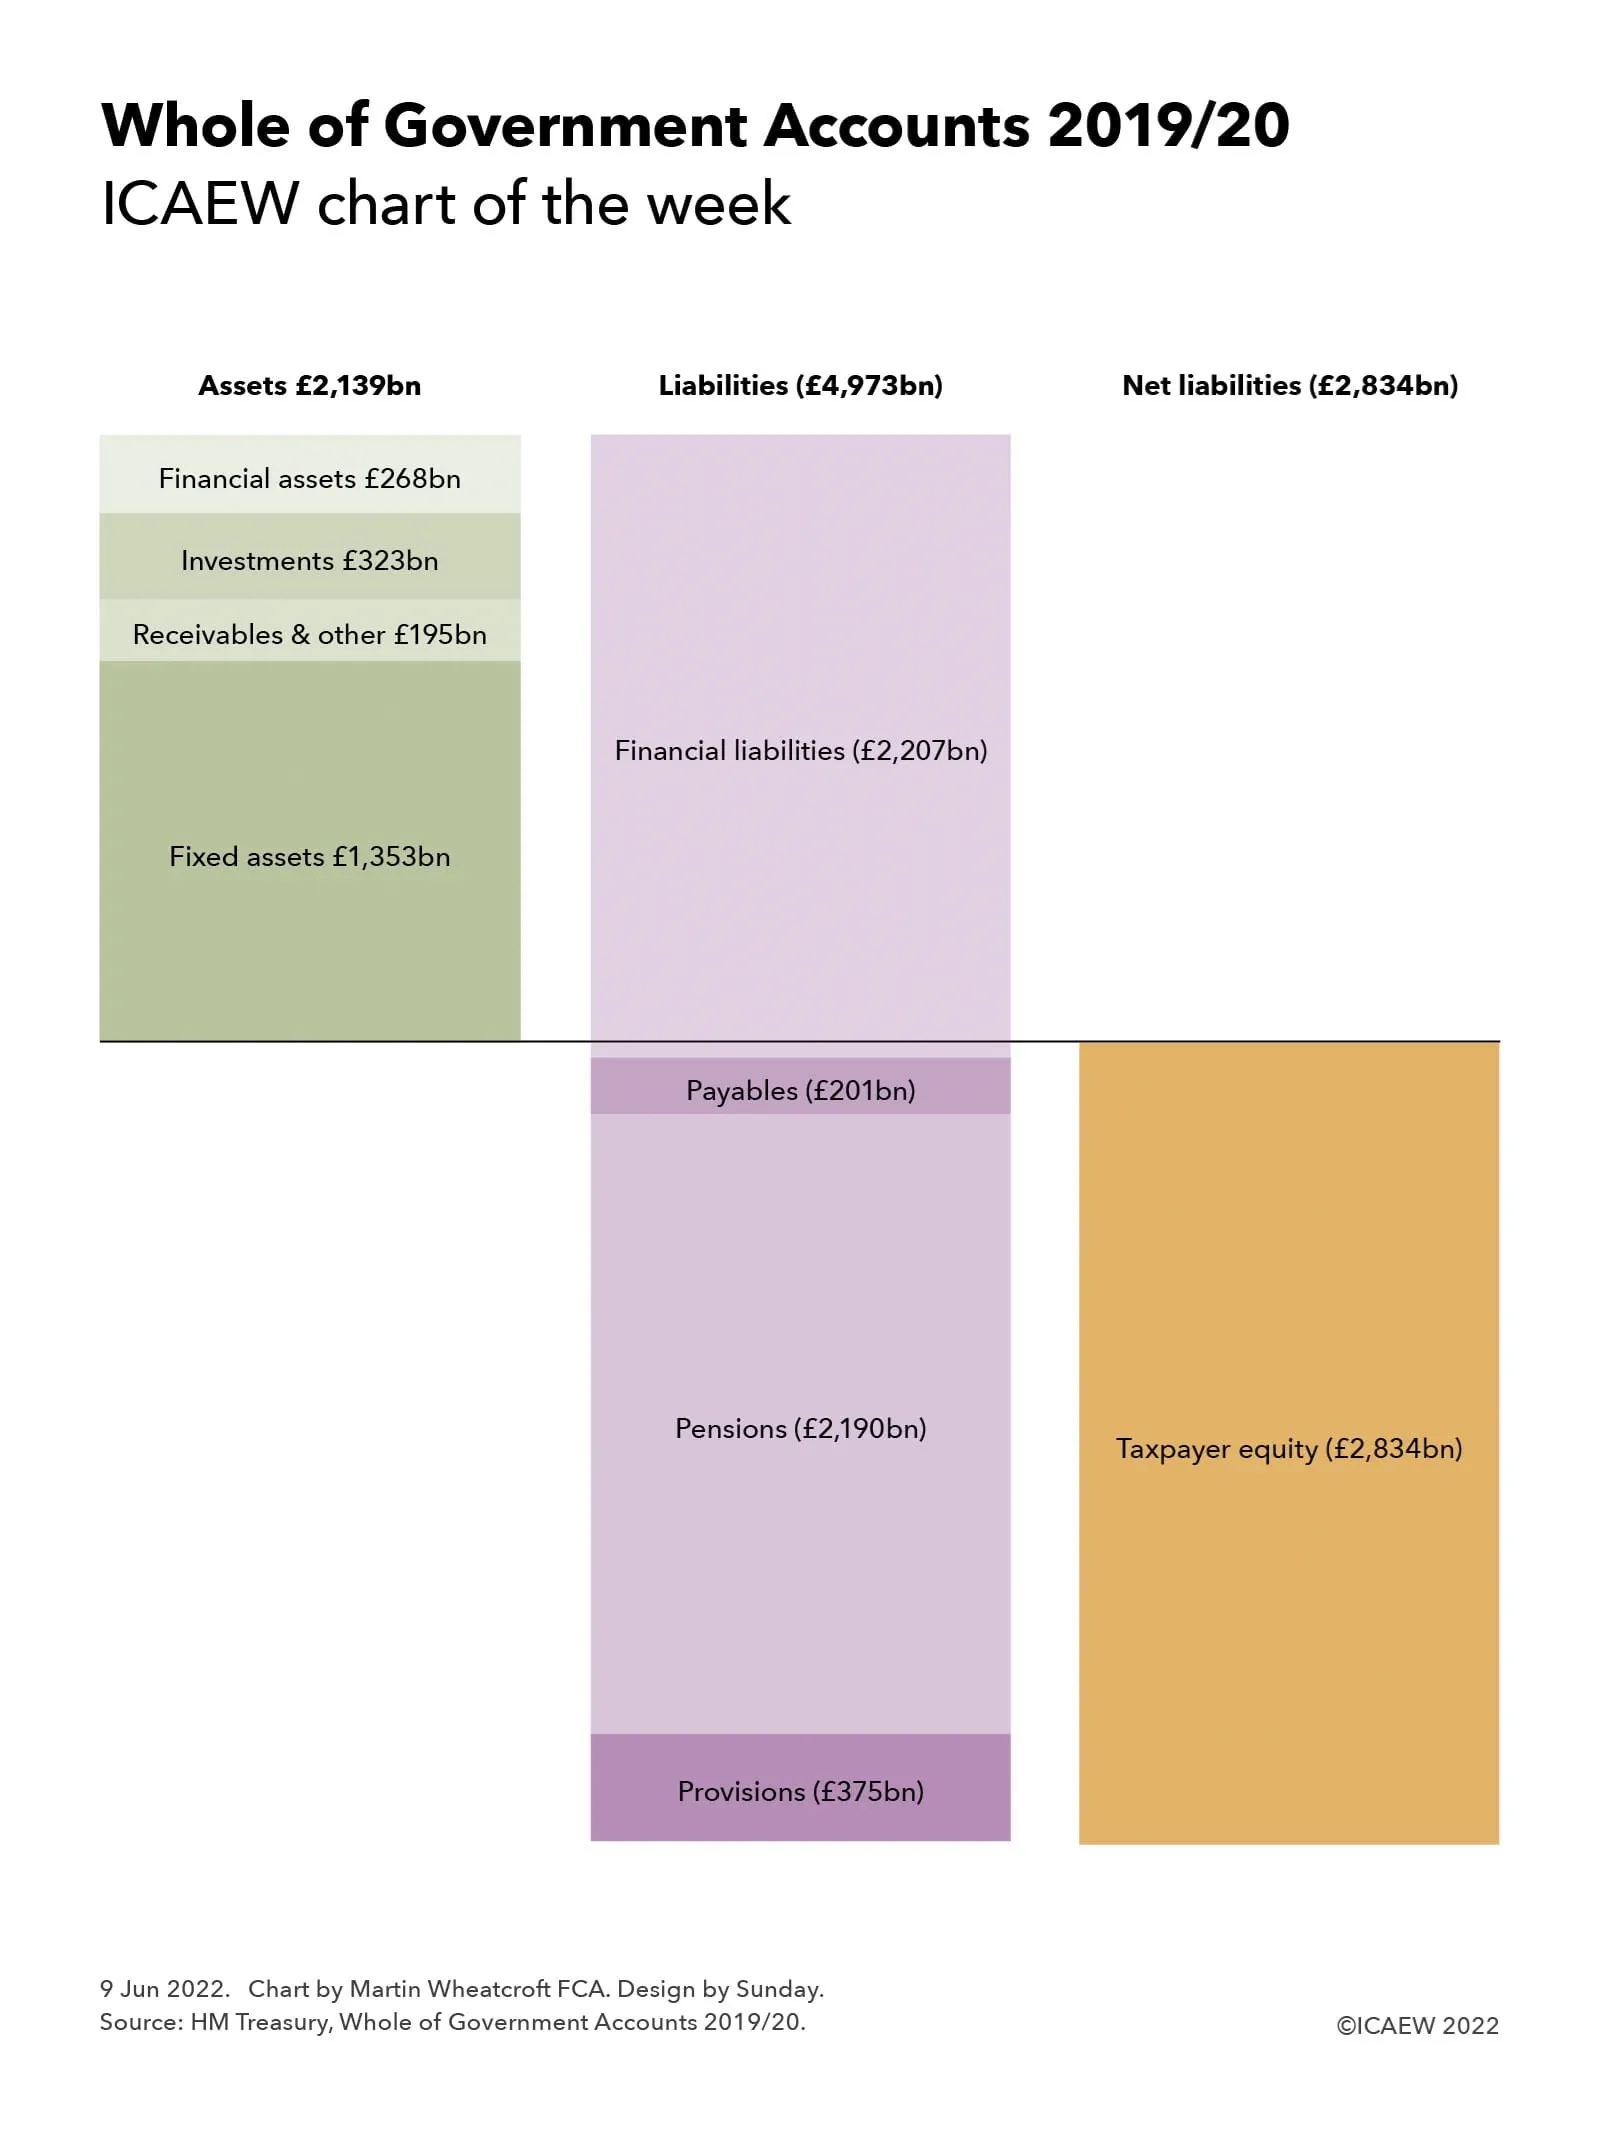
We take a look at the government balance sheet at 31 March 2020 this week, following publication by HM Treasury of the long-delayed 2019/20 audited financial statements for the UK public sector.

Step chart showing public assets £2,129bn, liabilities of (£4,973bn) and net liabilities of (£2,834bn).

Fixed assets £1,353bn, receivables & other £195bn, investments £323bn, financial assets £268bn.

Financial liabilities (£2,207bn), payables (£201bn), pensions (£2,190bn).

Taxpayer equity (£2,834bn).

HM Treasury was up in front of the Public Accounts Committee (PAC) this week to be grilled on the Whole of Government Accounts (WGA) for the year ended 31 March 2020. The first question posed by MPs was why it had taken more than 26 months to publish the audited financial statements for the UK public sector, unlocking a tale of woe regarding the pandemic, delays in central government reporting, even greater delays in local government, and problems in implementing a new consolidation system. 

For all that, the PAC expressed their appreciation for the contents of the WGA, which comprises a performance report, governance statements, financial statements prepared in accordance with International Financial Reporting Standards, an audit report and a reconciliation to the fiscal numbers reported by the Office for National Statistics. The UK is one of the leading governments around the world in preparing comprehensive financial reports similar to those seen in the private sector, and is the only one to attempt to incorporate local government as well as central government and public corporations.

Our chart summarises the balance sheet reported in the consolidated financial statements at 31 March 2020, when there were total assets of £2,139bn, total liabilities of £4.973bn and negative taxpayer equity of £2,834bn. These numbers do not reflect the more than half a trillion pounds borrowed since then which are likely to see the 2020/21 and 2021/22 WGA move even further into negative territory. 

On the positive side of the balance sheet were:

  • £195bn of receivable and other assets, comprising £160bn of trade and other receivables due within one year, £22bn of receivables due in more than year, £11bn of inventories and £2bn of assets held for sale;
  • £1,353bn of fixed assets, consisting of £676bn for infrastructure, £459bn of land and buildings, £77bn of assets under construction, £41bn of military equipment, £60bn of other tangible fixed assets, and £40bn of intangibles;
  • £323bn of investments, including £126bn of non-current loans and deposits, £77bn in student loans, £36bn in equity investments, £22bn invested in the IMF, £38bn in derivatives and other, and £24bn in investment property; and 
  • £268bn of current financial assets, of which £118bn were in debt securities, £74bn in loan balances due within one year, £38bn in cash and cash equivalents, £13bn in gold holdings, £13bn in IMF special drawing rights and £12bn in derivatives and other.

On the negative side, there were:

  • £2,207bn in financial liabilities, comprising £1,266bn in government securities (gilts and Treasury bills), £560bn of deposits owed to banks, £179bn owed to investors in National Savings & Investments, £78bn in bank and other borrowings, £74bn in banknotes and £50bn in derivatives and other financial liabilities;
  • £201bn of payables, including £66bn of accruals and deferred income, £55bn of trade and other payables, £42bn in lease obligations, £34bn in tax and duty refunds payable and £4bn in contract liabilities;
  • £2,190bn in net pension obligations, of which £2,062bn were for unfunded pension schemes (NHS £760bn, teachers £490bn, civil service £309bn, armed forces £233bn, police & fire £197bn, other £73bn) and £128bn for funded schemes (local government £359bn less £253bn = £106bn, and other funded schemes £106bn less £84bn = £22bn). This balance does not include the state pension, which is treated as a welfare benefit and not a liability for accounting purposes; and
  • £375bn in provisions for liabilities and charges, including £157bn for nuclear decommissioning, £86bn for clinical negligence, £39bn for EU liabilities, £31bn for the pension protection fund and £62bn in other provisions.

Net liabilities therefore amounted to £2,834bn, reflecting the general policy decision taken by successive governments not to fund liabilities in advance, but instead to rely on future tax revenues and borrowing to provide cash as needed to settle liabilities and other financial obligations and commitments. As Sir Tom Scholar, Permanent Secretary at HM Treasury, informed the PAC, this minimises the investment risks the government might otherwise be exposed to if it were to invest in (say) the stock market.

Cat Little, Head of the Government Finance Function, set out plans to bring down the time to prepare the WGA, to within 24 months for the 2020/21 WGA and to within 20 months for the 2021/22 WGA. This remains a long way off the long-term objective of producing the WGA within nine months of the balance sheet date.

While the numbers in these financial statements are now more than two years old, they are still extremely valuable in providing a baseline for the financial position of the UK public sector as the country headed into the pandemic. It is well worth a read if you have the time.

The Whole of Government Accounts 2019/20 is available online.

This chart was originally published by ICAEW.