ICAEW chart of the week: A £3tn economy

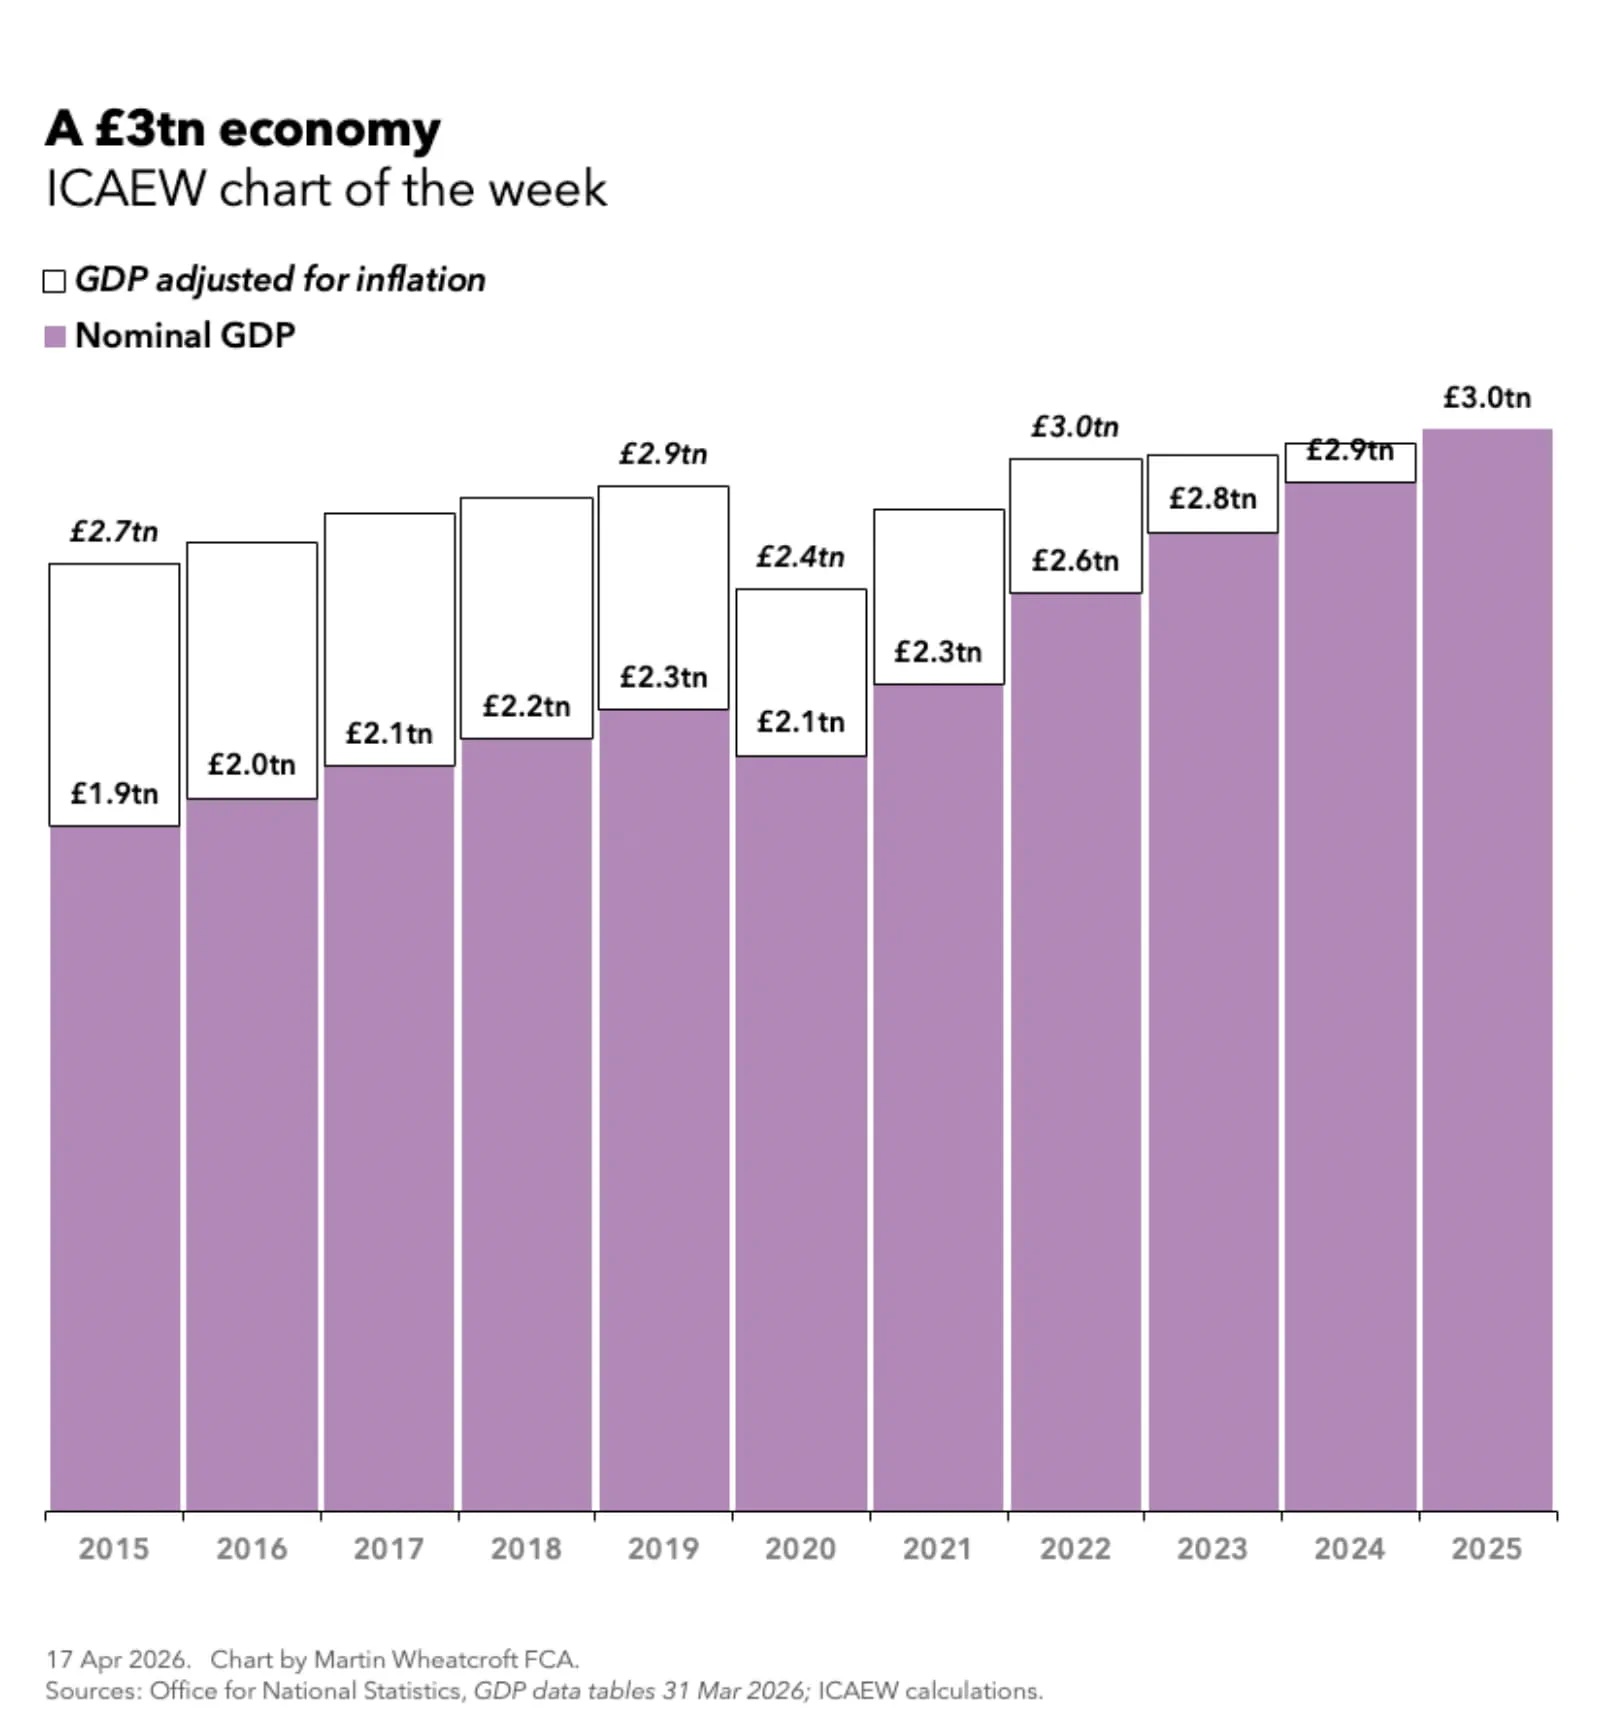
My chart this week for ICAEW is on how GDP for the UK reached £3.0tn for the first time in 2025. This is a 58% increase over the course of a decade, mostly driven by a combination of inflation and a rising population, resulting in a relatively small amount of per capita economic growth.
ICAEW chart of the week: A £3tn economy. 

A column chart showing nominal GDP (as solid purple bars) and GDP adjusted for inflation (transparent bars) between 2015 and 2025. 

Nominal GDP: £1.9tn in 2015, £2.0tn, £2.1tn, £2.2tn, £2.3tn, £2.1tn in 2020, £2.3tn, £2.6tn, £2.8tn, £2.9tn and £3.0tn in 2025. 

GDP adjusted for inflation (in 2025 values with only selected bars labelled): £2.7tn in 2015, £2.9tn in 2019, £2.4tn in 2020 and £3.0tn in 2022. 

17 Apr 2026. Chart by Martin Wheatcroft FCA. Sources: ONS, GDP data tables 31 Mar 2026; ICAEW calculations.

My chart of the week for ICAEW is on gross domestic product (GDP), the principal measure used by statisticians and economists to assess the size of the economy. 

The chart shows how nominal GDP (GDP at market prices in current values) was £1.9tn in 2015, rising to £2.0tn in 2016, £2.1tn in 2017, £2.2tn in 2018 and then £2.3tn in 2019. Nominal GDP fell to £2.1tn in 2020 (the first year of the pandemic) and then rose to £2.3tn in 2021, £2.6tn in 2022, £2.8tn in 2023, £2.9tn in 2024 and then £3.0tn in 2025.

This is a cumulative increase of 58% over 10 years (or 4.7% a year on average), based on nominal GDP of £1,928bn in 2015 and £3,040bn in 2025.

The chart also shows the increase is much less dramatic using GDP adjusted for inflation (GDP at market values on a chained volume basis or ‘real GDP’). Recalculated into 2025 values, GDP adjusted for inflation was £2.7tn in 2015, £2.9tn in 2019, £2.4tn in 2020 and just under £3.0tn in 2022.

As ever with economic statistics these numbers are all subject to revision as the ONS obtains new or updated data and, every so often, revises its methodology.

Analysing the increase

The 58% increase in nominal GDP over the 10 years to 2025 can be analysed as a cumulative 38% increase from inflation (using the GDP deflator ‘all economy’ measure of inflation) and cumulative economic growth of 14%, with the latter being further analysed into a cumulative 7% increase in the size of the population, and a cumulative 7% increase in average economic activity per person. 

This is equivalent to a 4.7% per year average annual increase in nominal GDP over the decade, comprising 3.3% per year in average annual inflation and 1.3% per year in economic growth. The latter comprises a 0.7% per year annual rise in population and a 0.7% increase in average per capita economic activity. 

Economic growth has been particularly weak over the past three years in particular, with a cumulative increase of 17.8% in nominal GDP comprising cumulative inflation of 14.6% and a cumulative increase of 2.8% in GDP adjusted for inflation (from £2,958bn in 2022 adjusted to 2025 prices to £3,040bn in 2025).

As the population is estimated to have increased by 2.7% between 2022 and 2025, per capita economic activity over the same period has in effect been flat over the last three years.

Unfortunately, the outlook for the economy is far from rosy given recent international developments and there is now a risk that nominal GDP could fall back below £3.0tn in 2026, despite what is likely to be a higher rate of inflation than previously anticipated.
This chart was originally published by ICAEW.

ICAEW chart of the week: Public investment

My chart for ICAEW this week looks at how public investment in assets is expected to increase over the next couple of years as the government seeks to stimulate the economy and “build build build”.

ICAEW chart of the week: Public investment. 

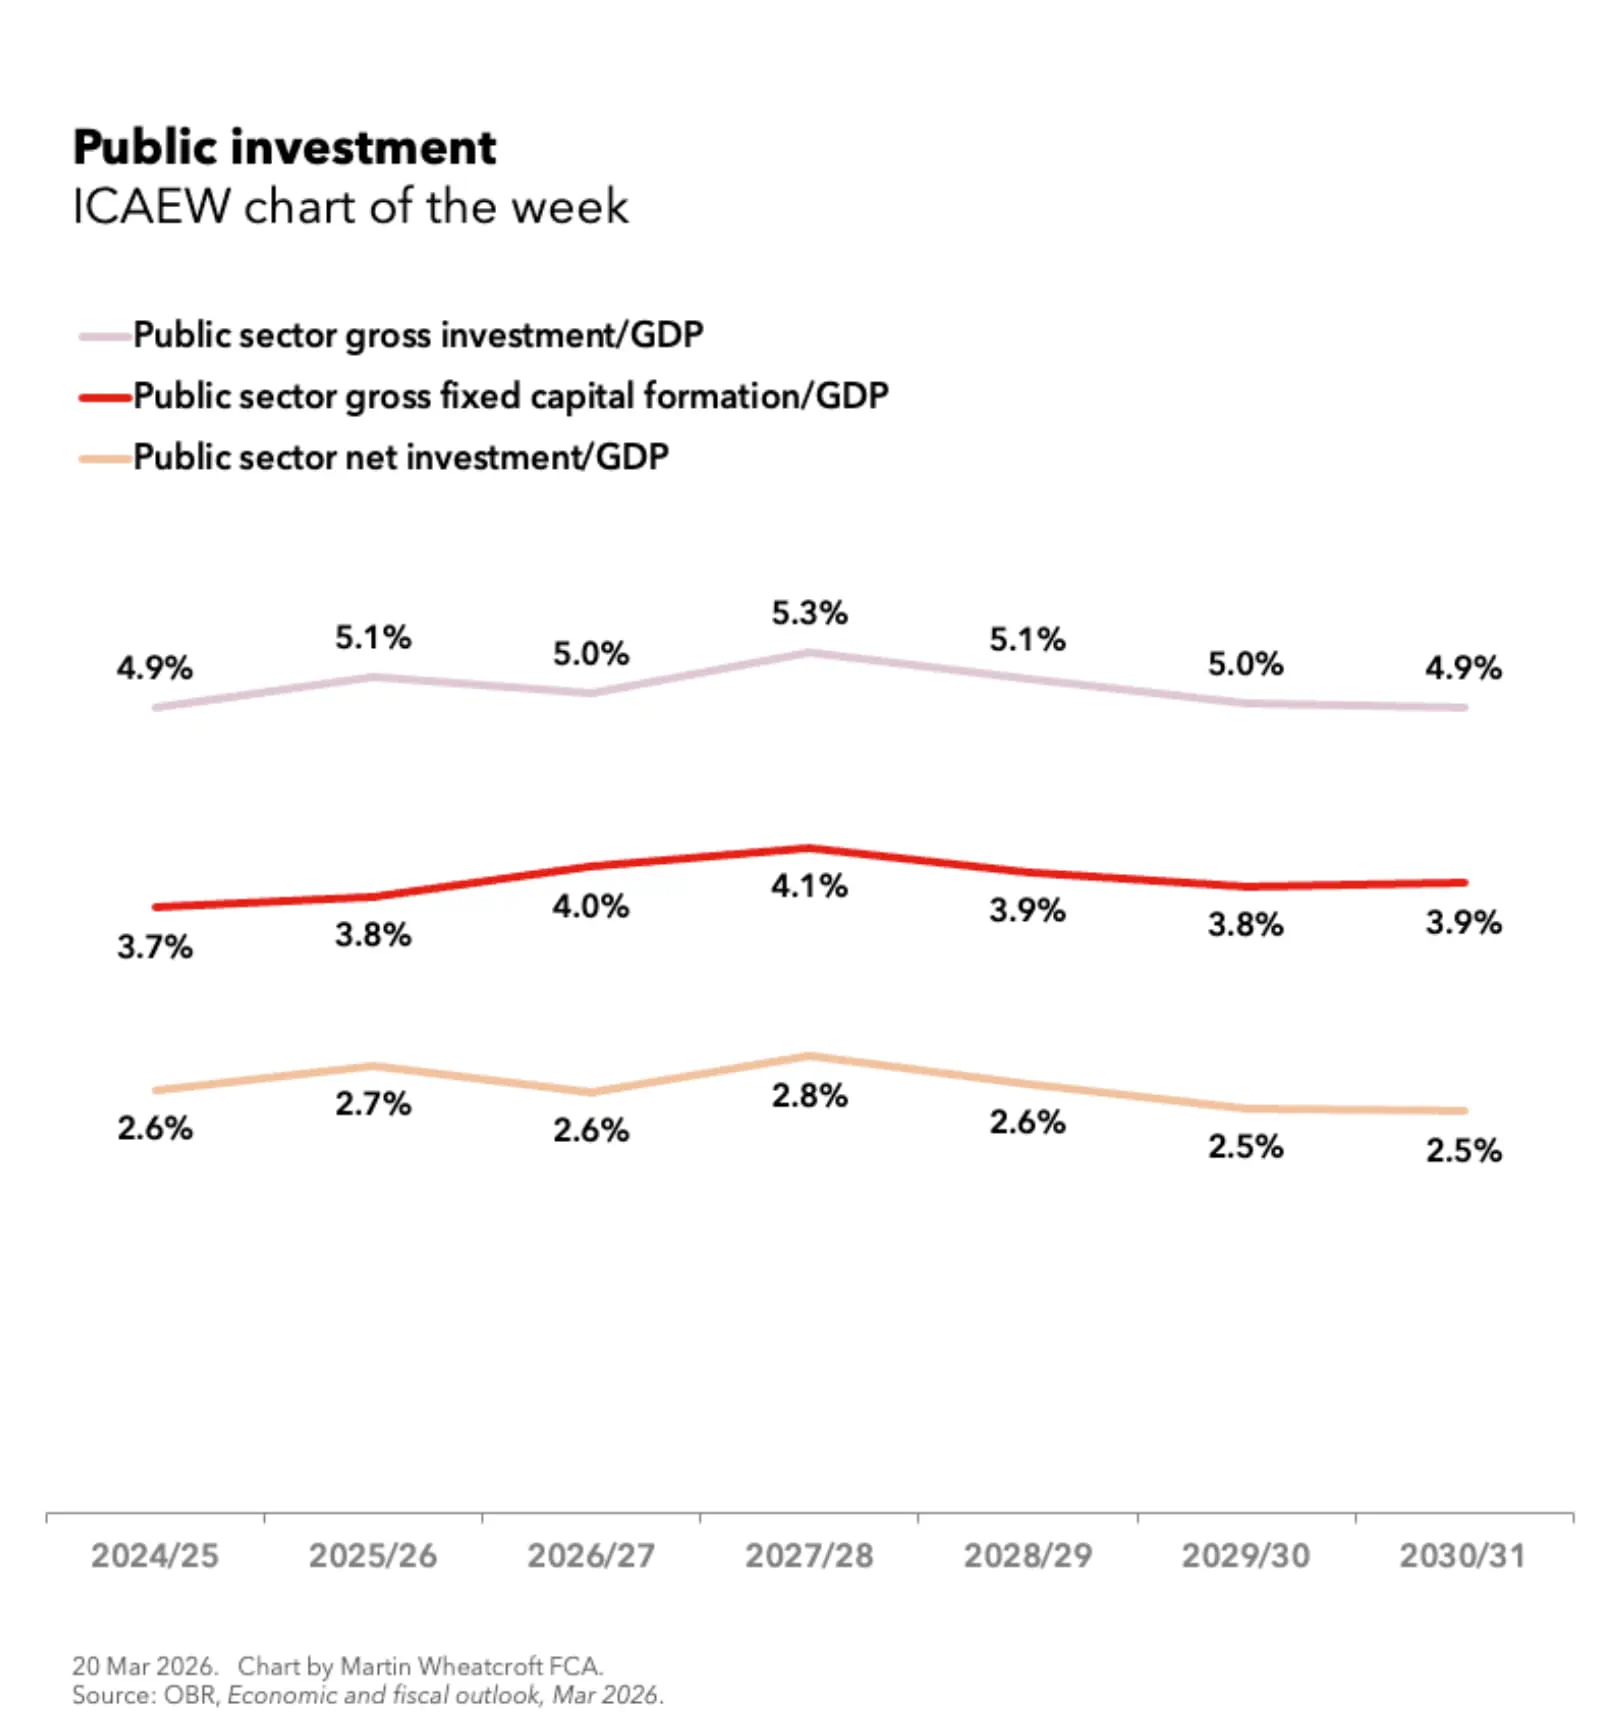
A line chart showing three measures of public sector investment in relation to the size of the economy between 2024/25 and 2030/31.

Public sector gross investment/GDP (in purple): 4.9%, 5.1%, 5.0%, 5.3%, 5.1%. 5.0% and 4.9%. 

Public sector gross fixed capital formation/GDP (in ICAEW red): 3.7%, 3.8%, 4.0%, 4.1%, 3.9%, 3.8% and 3.9%. 

Public sector net investment/GDP (in orange): 2.6%, 2.7%, 2.6%, 2.8%, 2.6%, 2.5% and 2.5%. 

20 Mar 2026. Chart by Martin Wheatcroft FCA. 
Source: OBR, Economic and fiscal outlook, Mar 2026.

According to the Office for Budget Responsibility’s latest fiscal forecasts, public sector gross capital formation – the statistical equivalent of capital expenditure – is expected to increase as a share of the economy from 3.7% and 3.8% of GDP in the years ending 31 March 2025 and 2026 (2024/25 and 2025/26 respectively) to 4.0% and 4.1% in 2026/27 and 2027/28, before falling to 3.9%, 3.8% and 3.9% in 2028/29, 2029/30 and 2029/31.

My chart for ICAEW this week shows this trend, together with the headline percentages of public sector gross investment/GDP and public sector net investment/GDP. The former is expected to bounce around 5% of GDP – going from 4.9% in 2024/25 to 5.1%, 5.0%, 5.3%, 5.1%, 5.0% and then 4.9% in 2030/31. The latter is expected to go from 2.6% in 2024/25 to 2.7%, 2.6%, 2.8%, 2.6%, 2.5% and 2.5% in 2030/31.

Public sector gross investment is higher than gross capital formation because it also includes capital grants, research and development funding, and student loan impairments in addition to capital expenditure on infrastructure and other fixed assets.

Public sector net investment is equal to public sector gross investment less depreciation, to give an idea of much is new investment after taking account of the usage of existing assets.

The increase in public sector gross fixed capital formation – from £116bn in 2025/26 to £125bn in the coming financial year starting on 1 April 2026 (2026/27) and then to £134bn in the following financial year (2027/28) – is a substantial expansion in the level of public sector capital expenditure. 

These increases, of 6% and 5% respectively over the next two years after adjusting for inflation, should be positive for an economy that needs every boost that it can get. If it can help unlock incremental private sector investment too, the economic benefit could be even greater.

The challenge is that while additional investment is welcome, this is not a transformative change, especially as the increase as a share of the economy is not expected to be sustained beyond the first couple of years of the forecast period.

The expectation of many commentators was that the Chancellor was hoping for improvements in the economy to allow her to pencil in further increases in 2028/29 and beyond. Recent events suggest this hope may be less likely than it once was.

This chart was originally published by ICAEW.