ICAEW chart of the week: A £3tn economy

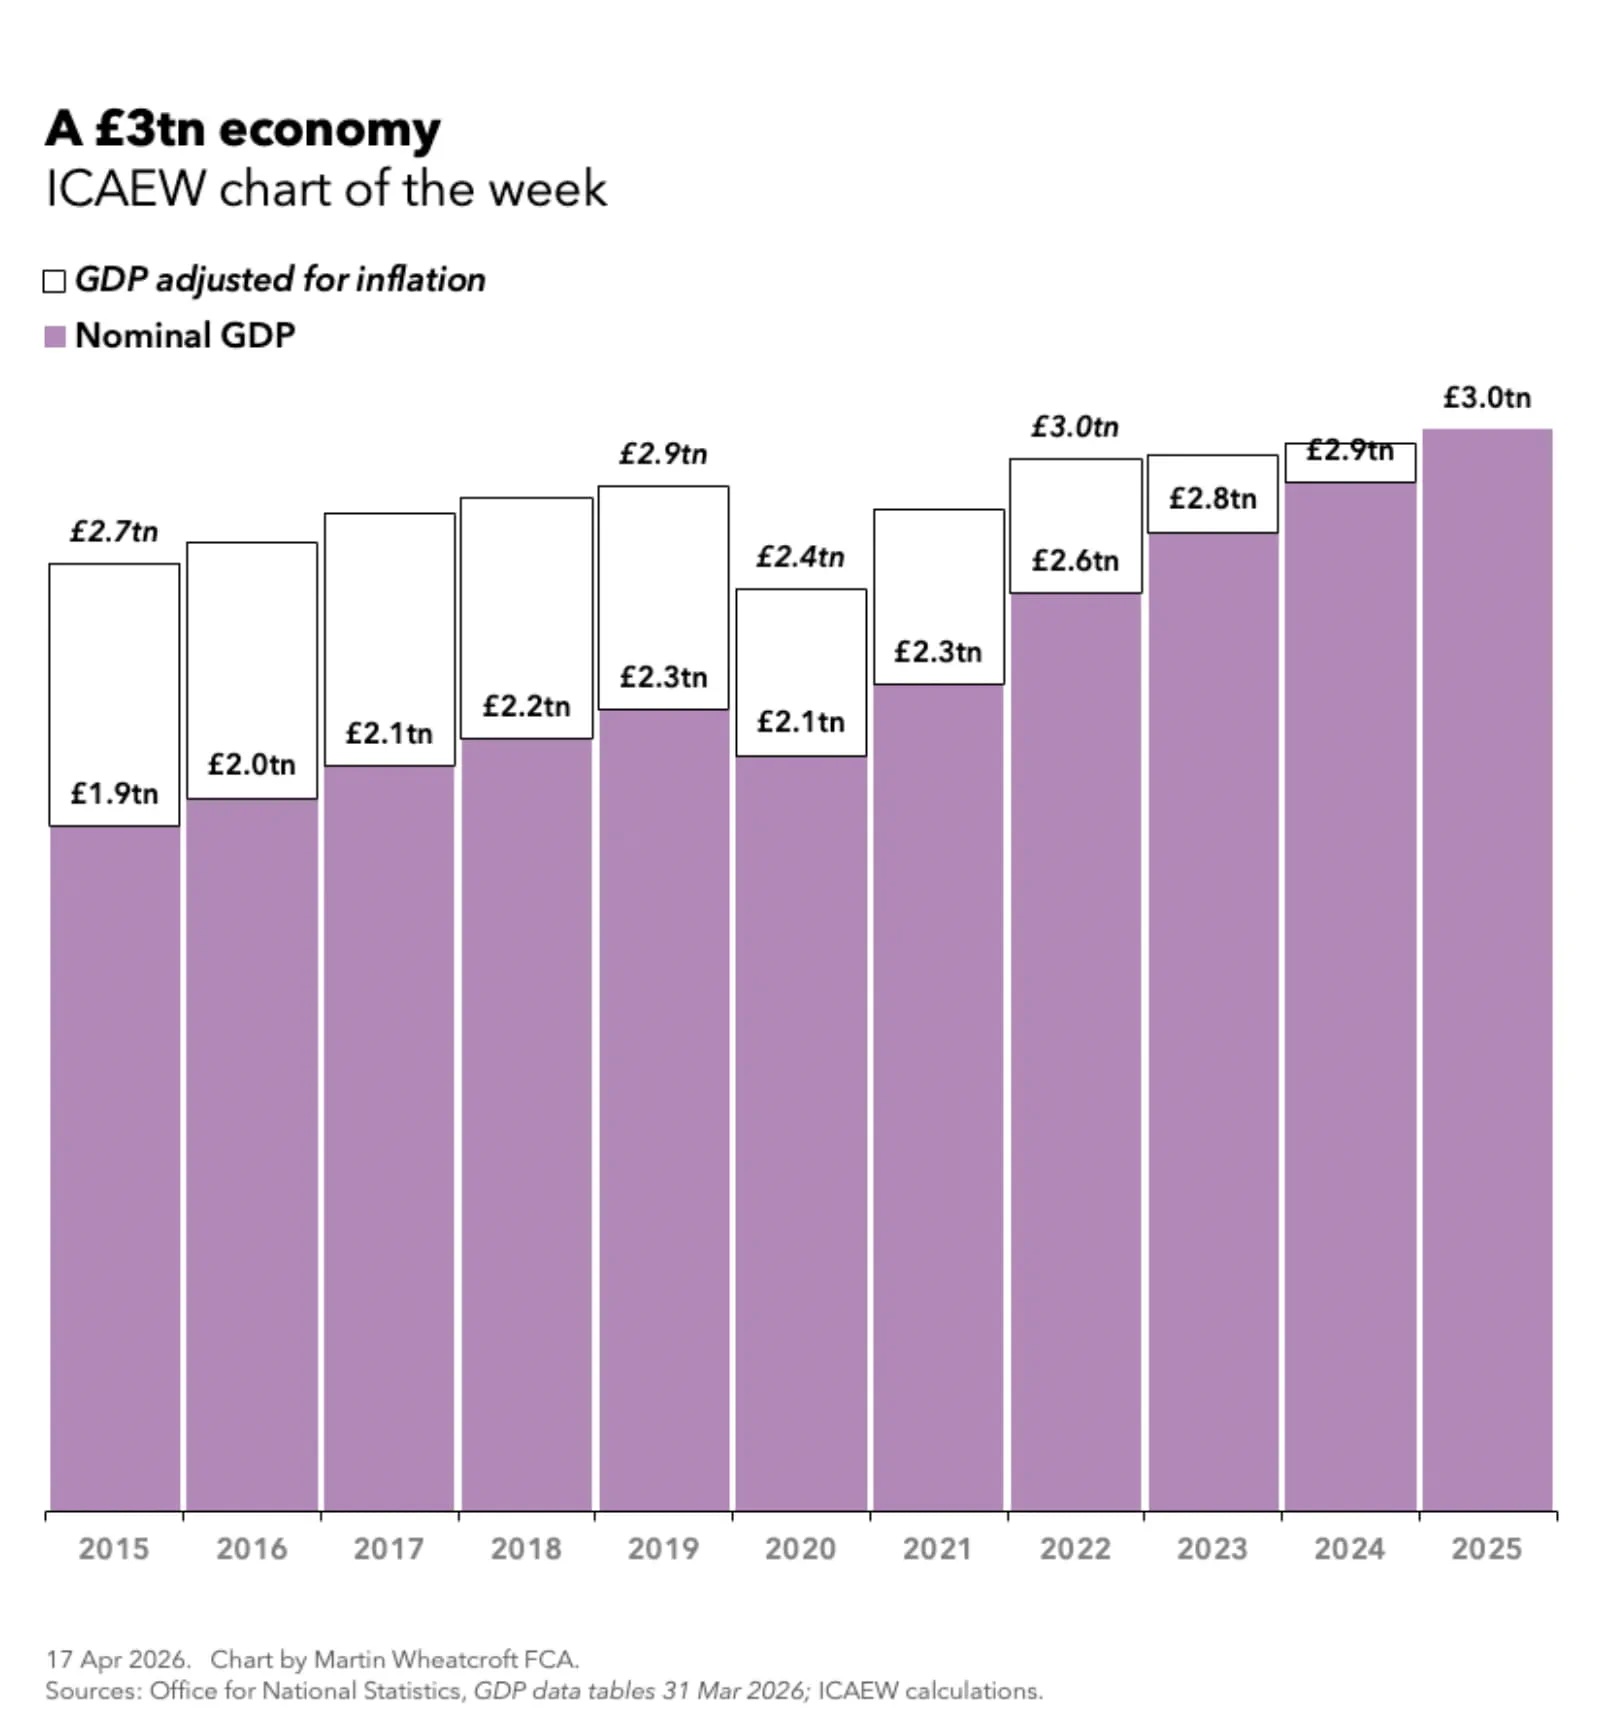
My chart this week for ICAEW is on how GDP for the UK reached £3.0tn for the first time in 2025. This is a 58% increase over the course of a decade, mostly driven by a combination of inflation and a rising population, resulting in a relatively small amount of per capita economic growth.
ICAEW chart of the week: A £3tn economy. 

A column chart showing nominal GDP (as solid purple bars) and GDP adjusted for inflation (transparent bars) between 2015 and 2025. 

Nominal GDP: £1.9tn in 2015, £2.0tn, £2.1tn, £2.2tn, £2.3tn, £2.1tn in 2020, £2.3tn, £2.6tn, £2.8tn, £2.9tn and £3.0tn in 2025. 

GDP adjusted for inflation (in 2025 values with only selected bars labelled): £2.7tn in 2015, £2.9tn in 2019, £2.4tn in 2020 and £3.0tn in 2022. 

17 Apr 2026. Chart by Martin Wheatcroft FCA. Sources: ONS, GDP data tables 31 Mar 2026; ICAEW calculations.

My chart of the week for ICAEW is on gross domestic product (GDP), the principal measure used by statisticians and economists to assess the size of the economy. 

The chart shows how nominal GDP (GDP at market prices in current values) was £1.9tn in 2015, rising to £2.0tn in 2016, £2.1tn in 2017, £2.2tn in 2018 and then £2.3tn in 2019. Nominal GDP fell to £2.1tn in 2020 (the first year of the pandemic) and then rose to £2.3tn in 2021, £2.6tn in 2022, £2.8tn in 2023, £2.9tn in 2024 and then £3.0tn in 2025.

This is a cumulative increase of 58% over 10 years (or 4.7% a year on average), based on nominal GDP of £1,928bn in 2015 and £3,040bn in 2025.

The chart also shows the increase is much less dramatic using GDP adjusted for inflation (GDP at market values on a chained volume basis or ‘real GDP’). Recalculated into 2025 values, GDP adjusted for inflation was £2.7tn in 2015, £2.9tn in 2019, £2.4tn in 2020 and just under £3.0tn in 2022.

As ever with economic statistics these numbers are all subject to revision as the ONS obtains new or updated data and, every so often, revises its methodology.

Analysing the increase

The 58% increase in nominal GDP over the 10 years to 2025 can be analysed as a cumulative 38% increase from inflation (using the GDP deflator ‘all economy’ measure of inflation) and cumulative economic growth of 14%, with the latter being further analysed into a cumulative 7% increase in the size of the population, and a cumulative 7% increase in average economic activity per person. 

This is equivalent to a 4.7% per year average annual increase in nominal GDP over the decade, comprising 3.3% per year in average annual inflation and 1.3% per year in economic growth. The latter comprises a 0.7% per year annual rise in population and a 0.7% increase in average per capita economic activity. 

Economic growth has been particularly weak over the past three years in particular, with a cumulative increase of 17.8% in nominal GDP comprising cumulative inflation of 14.6% and a cumulative increase of 2.8% in GDP adjusted for inflation (from £2,958bn in 2022 adjusted to 2025 prices to £3,040bn in 2025).

As the population is estimated to have increased by 2.7% between 2022 and 2025, per capita economic activity over the same period has in effect been flat over the last three years.

Unfortunately, the outlook for the economy is far from rosy given recent international developments and there is now a risk that nominal GDP could fall back below £3.0tn in 2026, despite what is likely to be a higher rate of inflation than previously anticipated.

This chart was originally published by ICAEW.

ICAEW chart of the week: Real average pay in the UK

Our chart this week illustrates how UK average total pay fell by 0.2% in real terms over the 12 months to December 2025, following much stronger growth in the previous two years.

According to an Office for National Statistics (ONS) release on 17 February 2026, real average weekly earnings adjusted for consumer price inflation fell by 0.2% in the 12 months to December 2025, following increases of 1.9% and 3.6% over the course of 2023 and 2024 respectively.

After converting the ONS data from weekly to monthly and scaling up to December 2025 pound values, our chart this week illustrates these changes, showing how average weekly total pay (including overtime and bonuses) in real terms increased from £3,029 in December 2022 (in December 2025 values) to £3,086 and £3,198 in December 2023 and 2024 respectively, before falling to and £3,192 in 2025.

Our chart also shows how actual total pay (ie, not adjusted for inflation) increased from £2,760 to £2,919, £3,099 and £3,192 over that same period, increases of 5.8%, 6.2% and 3.0% respectively.

The increases in real pay over the course of 2023 and 2024 partly reflect a catch-up from the 4.9% real-terms fall seen in 2022 and the large minimum wage increases implemented in April 2024 that boosted pay for lower earners, while the real-terms fall in 2025 reflects a spike in inflation that eroded the value of pay awards over the course of the year. 

The good news for many employees is that average pay rises during 2026 are expected to be more than the 3.0% experienced last year just as inflation is coming down. This should in theory mean (at least on average) more disposable income that can be either spent or saved.

The Chancellor for one will be hoping that people go out and spend their pay rises this year, as she really needs a boost to the economy if she is to stay on course with her fiscal plans.

This chart was originally published by ICAEW.

ICAEW chart of the week: Business births and deaths in the UK

My chart for ICAEW this week looks at the cycle of business life since 2017, as the number of business births exceeded business deaths in 2025 for the second year in succession.

According to the Office for National Statistics (ONS), the number of businesses on the Inter-Departmental Business Register (IDBR) grew by 28,470 in 2025, comprising 313,715 business births less 285,245 business deaths. 

The IDBR is a database of 2.76m businesses in the UK that are registered for VAT or PAYE or which report turnover in their company filings, business credit reports or are otherwise identified as actively trading.

On 31 March 2025, when it stood at 2.73m, the register comprised 2,096,600 active companies, 380,520 sole proprietor enterprises, 160,865 partnerships, 84,000 charities and other not for profit organisations, and 12,630 public sector organisations.

Business births arise when businesses are added to the register, while deaths occur when businesses are dissolved, their turnover or employment falls to zero for several periods, or the ONS is otherwise notified that they are no longer trading.

As our chart this week illustrates there were a net 13,340 business creations in 2017 (338,625 business births – 325,285 business deaths), 35,275 in 2018 (340,150 – 304,875), 44,270 in 2019 (355,725 – 311,455), 13,665 in 2020 (321,990 – 308,325) and 9,385 (354,280 – 344,895) in 2021. There were a net 47,990 business destructions in 2022 (327,510 – 375,500) and 26,265 in 2023 (307,145 – 333,410), followed by net additions to the IDBR of 14,800 in 2024 (310,615 – 295,815) and 28,470 in 2025 (313,715 – 285,245).

These are equivalent to net changes of +0.5%, +1.3%, +1.6%, 0.5%, 0.3%, -1.7%, -1.0%, +0.5% and +1.0% in 2017 through to 2025 respectively. In 2025, this was made up of an increase of 11.5% less a decrease of 10.5% compared with the start of the year, highlighting the level of churn in the business register.

The net increase of 28,470 in 2025 comprised net increases of 5,035 professional, scientific and technical businesses, 4,400 in the real estate sector, 4,270 in accommodation and food services, 3,355 in retail, 3,000 in construction, 2,785 in transportation and storage, 2,615 in health and social care, 2,515 in arts, entertainment, recreation and other services, 1,645 in education, 1,420 in motor trades, 1,145 in business administration and support services, and 615 in finance and insurance. There were net reductions of 10 in wholesale businesses, 440 in information and communication, 790 in production, and 3,090 in agriculture, forestry and fishing.

The good news is that the number of UK businesses is starting to grow again, which may be a small spark of hope for the UK economy as we enter the second quarter of the 21st century.

This chart was originally published by ICAEW.

ICAEW chart of the week: Global stock markets

Our chart looks at how the top 10 stocks from nine companies made up more than a fifth of global stock market values on 31 December 2025.

Our chart this week is on equity markets around the world, illustrating how the 10,077 shares in the FTSE Global All Cap Index had a total market capitalisation of $103.6tn on 31 December 2025.

This can be analysed as $80.7tn (78% of the total) excluding the top 10 stocks and $22.9tn (22%) for the top 10 stocks.

Excluding the top nine US stocks, the Americas had a total market capitalisation of $46.9tn (45%). In Asia Pacific, excluding the largest non US stock, the total was $17.2tn (17%). Europe, the Middle East and Africa (EMEA) accounted for $16.2tn (16%).

The top 10 stocks are led by Nvidia, valued at $4.4tn (4.2% of the total global stock market capitalisation on 31 December 2025), followed by Apple at just over $3.9tn (3.8%), Microsoft on $3.6tn (3.5%), Alphabet A and C shares combined $3.3tn (3.2%), Amazon on $2.2tn (2.1%), Broadcom on $1.6tn (1.5%), Meta A shares on $1.4tn (1.4%), and Tesla on $1.3tn (1.2%).

The tenth stock (and ninth company) is that of Taiwan Semiconductor Manufacturing (TSM), which had a market capitalisation of $1.2tn (1.2% of the global total) on 31 December 2025.

The market capitalisations for Alphabet and Meta shown exclude the values of their non-traded B shares, which means their total equity values were closer to $4.0tn and $1.7tn respectively on 31 December 2025. The FTSE Global All Cap Index also doesn’t include the $1.6tn estimated market value of Saudi Aramco as less than 2.5% of this stock is traded.

If the top 10 stocks are included with their respective regions, the chart would show the Americas with a market capitalisation of $68.9tn (66% of the total), Asia-Pacific with $18.4tn (18%) and EMEA unchanged at $16.2tn (16%).

Not shown in the chart is how market capitalisations are distributed within each global region. The Americas comprise the US with $43.0tn (41.0%) excluding the top nine US stocks, or $64.7tn (62.0%) if they are included, Canada with $3.2tn (3.1%) and Latin America countries with $0.8tn (0.7%).

The market capitalisation of Asia-Pacific country stocks is led by Japan $5.8tn (5.6%), followed by China including Hong Kong with $3.9tn (3.7%), India $2.1tn (2.0%), Australia and New Zealand $1.8tn (1.7%), Korea $1.6tn (1.5%), Taiwan excluding TMS is $1.2tn (1.2%) and ASEAN nations $0.9tn (0.9%). Taiwan including TMS is $2.4tn (2.3%).

In EMEA, EU member country stocks add up to $9.3tn (9.0% of the total), the UK $3.4tn (3.3%), EFTA countries $2.3tn (2.2%), Middle East $1.1tn (1.1%) and Africa $0.4tn (0.4%).

As everyone investing in stock markets should know, individual share values can go down as well as up, which is why diversifying your investments often makes good sense.

However, in the case of global stock markets – and the US in particular – the total value of listed equities around the world are highly dependent on the fortunes (or otherwise) of just nine companies.

Be careful out there.

This chart was originally published by ICAEW.